

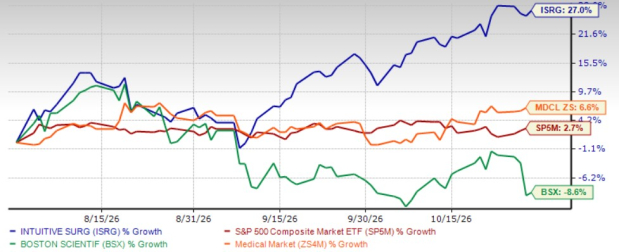
Over the past three months, Intuitive Surgical ISRG has gained 27%, while Boston Scientific BSX has declined 8.6%. ISRG outperformed both the Zacks Medical sector, which advanced 6.6%, and the S&P 500, which rose 2.7%, whereas BSX lagged both benchmarks.
Intuitive Surgical benefits from expanding robotic-assisted surgery adoption and recurring instruments revenue, whereas Boston Scientific relies on a diversified portfolio of minimally invasive cardiovascular and endoscopic devices. For the remainder of 2026, ISRG’s established growth trajectory contrasts with BSX’s challenges in electrophysiology (EP) and WATCHMAN, despite opportunities for eventual recovery.
ISRG delivered a strong third-quarter performance, with revenues increasing 22% to approximately $3.05 billion and adjusted EPS rising 25% to $3.00. Total procedures grew 15%, reflecting sustained demand across da Vinci and Ion platforms. Adjusted operating margin reached 42%, or 41% excluding a $28 million tariff refund, demonstrating robust operating leverage.
BSX reported organic revenue growth of 1.5%, while adjusted earnings per share declined 3% to 73 cents. A cybersecurity disruption reduced revenue growth by an estimated 300 basis points and EPS by 7 cents. Although this explains part of the weakness, underlying pressures in EP and WATCHMAN indicate that recovery will require more than normalization of operations.
Three-Month Price Comparison
Image Source: Zacks Investment Research
Revenue Growth
ISRG’s revenue growth accelerated from 19% in the second quarter to 22% in the third quarter, supported by system placements, product mix and higher recurring sales. Management narrowed its 2026 da Vinci procedure growth outlook to 14-15%, reflecting continued confidence in adoption.
In contrast, BSX’s organic growth slowed from 7% in the second quarter to 1.5% in the third quarter. Management now expects approximately 3.75% full-year organic growth, with fourth-quarter revenues projected to decline 1-3%. The revised outlook reflects mounting near-term challenges that have tempered the company's earlier expectations.
Profitability & Margins
ISRG’s adjusted operating margin of 42% reflects the economics of a growing installed base and recurring sales. However, product mix, tariffs and higher investment costs partially offset margin gains. BSX’s adjusted gross margin fell 300 basis points to 68%, while adjusted operating margin contracted 150 basis points to 26.5%, primarily because of cyber-related manufacturing disruption. Its second-quarter adjusted operating margin was 28.4%, underscoring the recent deterioration.
Growth Catalysts
ISRG is extending its competitive moat through AI-enabled workflows, telepresence, a voice-activated interface and automated fourth-arm control, with broader AI-controlled surgical motion currently in development. BSX’s opportunities center on cardiovascular innovation, including AGENT drug-coated balloons, FARAPULSE-based ablation and WATCHMAN. However, the timing and success of product launches will determine how quickly these opportunities translate into renewed growth.
Intuitive Surgical: Robotic Surgery Adoption Drives Growth
ISRG exited the third quarter with more than 13,200 da Vinci and Ion systems installed. Da Vinci placements increased 28%, with da Vinci 5 and SP accounting for 65% of placements. SP procedures grew 55%, while instruments and accessories revenues increased 18% to $1.8 billion. Ion procedures rose 31%, and international da Vinci procedures expanded 20%, reinforcing the opportunity to grow through broader clinical adoption and geographic expansion.
Boston Scientific: Product Innovation Offers Recovery Potential
BSX retains important growth assets, but the third-quarter results exposed uneven performance. Interventional Cardiology grew 19%, supported by imaging, coronary therapies and AGENT, which were used to treat more than 400,000 patients. WATCHMAN sales declined 6%, while EP sales fell 5% amid intensifying competition that weighed on the company's share of the pulsed-field ablation market. FARAWAVE Ultra is expected in early 2028, leaving a gap before the potential recovery catalyst arrives.
Valuation
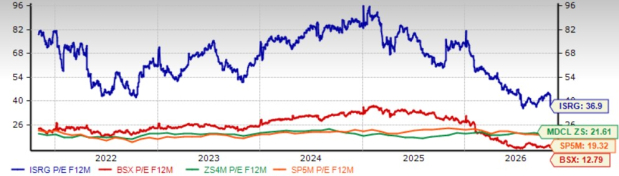
ISRG’s forward 12-month P/E of 36.5X exceeds the sector’s 20.93X, reflecting its growth premium. However, it is trading below its five-year median of 66.94X. BSX trades at 11.33X, below both the sector and its five-year median of 25.08X, offering a substantial valuation discount. Yet, slower growth and earnings pressure complicate the case for a recovery-driven re-rating.
Image Source: Zacks Investment Research
Sales and EPS Estimates
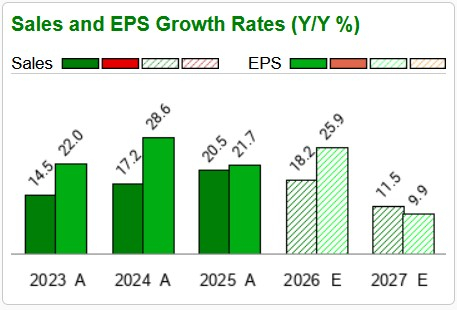
ISRG’s 2026 sales and EPS estimates of $11.89 billion and $11.24, respectively, imply growth of 18.2% and 25.9%. EPS estimates have improved 4.5% over the past 60 days.
Image Source: Zacks Investment Research
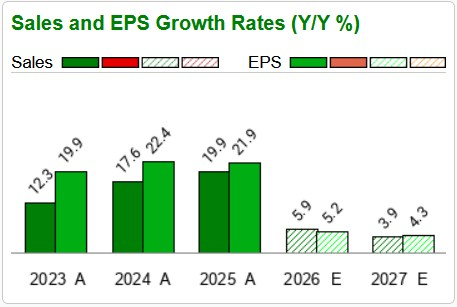
BSX's sales and EPS estimates of $21.26 billion and $3.22, respectively, indicate growth of 5.9% and 5.2%. The EPS estimate has been revised downward by 2.4%.
Image Source: Zacks Investment Research
A simple forward P/E-to-EPS-growth comparison is approximately 1.4 for ISRG versus 2.2 for BSX, suggesting that ISRG’s growth may better justify its premium.
Conclusion
Both companies offer exposure to minimally invasive procedures, but their investment profiles differ meaningfully. BSX’s lower valuation creates potential upside if WATCHMAN stabilizes, EP regains competitiveness and its newer cardiovascular products deliver sustained growth.
Nevertheless, management’s weaker 2026 outlook and expectations for continued pressure into 2027 make that recovery less certain. ISRG combines 15% procedure growth, 22% revenue expansion, an 84% recurring revenue mix and a growing installed base with opportunities in SP, Ion and AI-enabled surgical technology. Its valuation premium is a clear risk, but improving EPS estimates and stronger operating momentum offer greater visibility into future performance.
ISRG appears to be the more attractive investment choice at present, backed by its Zacks Rank #2 (Buy) compared with BSX’s Zacks Rank #4 (Sell), especially for investors seeking sustainable growth rather than a potential turnaround.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Boston Scientific Corporation (BSX): Free Stock Analysis Report
Intuitive Surgical, Inc. (ISRG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).