

BP p.l.c. BP used its third-quarter 2026 earnings call to emphasize further balance sheet strengthening, disciplined capital allocation and portfolio simplification despite substantial progress in reducing debt.
Management also outlined plans to address remaining Deepwater Horizon liabilities, defended its integrated business model and identified December's strategy update as a key milestone for defining future financial priorities.
The company delivered quarterly EPS of $3.26, which topped the Zacks Consensus Estimate of $2.66. Revenues of $69.88 billion also surpassed the consensus mark of $66.19 billion.
BP p.l.c. Price, Consensus and EPS Surprise
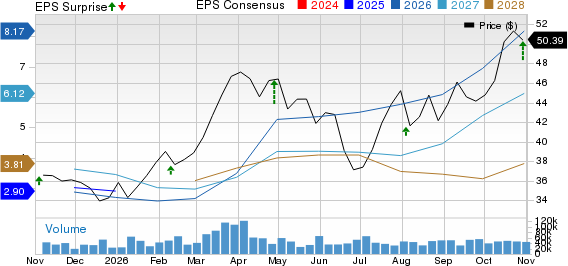
BP p.l.c. price-consensus-eps-surprise-chart | BP p.l.c. Quote
BP Prioritizes Further Balance Sheet Repair
CEO Meg O'Neill emphasized that financial resilience remains BP's foremost priority. Net debt declined $8.4 billion sequentially to $13.9 billion, supported by strong cash generation amid favorable commodity prices.
However, O'Neill cautioned that financial obligations remain excessive. During questioning from Wolfe Research, she stressed the importance of designing a capital structure capable of withstanding weaker oil and gas prices.
CFO Kate Thomson reinforced that perspective, indicating that dividends remain the first call on capital. Increased buybacks will depend on further strengthening the company's overall financial position.
Deepwater Horizon Obligations Remain in Focus
BP intends to prioritize excess cash flow toward fully addressing its remaining Deepwater Horizon settlement liabilities, following an agreement with Louisiana to accelerate settlement commitments.
Responding to RBC Capital Markets, Thomson explained that eliminating these obligations would improve financial resilience and reduce BP's cash flow breakeven. She declined to specify the execution mechanism.
Thomson noted that annual payments exceeding $1 billion have historically constrained cash availability. Management intends to disclose further details as the liability reduction process advances.
BP Accelerates Portfolio Simplification
O'Neill highlighted ongoing divestments intended to concentrate investment on businesses generating competitive returns. The Gelsenkirchen refinery sale was completed, while the Castrol transaction was approaching closure.
The Castrol divestment is expected to release $6 billion for balance-sheet strengthening. BP also agreed to sell its Austrian mobility and convenience business.
During questioning from Bank of America, O'Neill acknowledged challenges selling Lightsource BP because of its scale and complexity. She described the North Sea disposal process as competitive, while the Archaea process remains at an earlier stage.
Fourth-Quarter Outlook Points to Softer Conditions
Thomson outlined several expected fourth-quarter headwinds, including lower upstream production, reduced refining throughput, softer commodity prices and seasonally weaker customer volumes.
Responding to Morgan Stanley, she identified additional fourth-quarter capital expenditure of approximately $1 billion to $1.5 billion versus the third quarter, alongside $800 million higher cash tax payments.
Trading also faces a more subdued environment. Thomson emphasized that fourth-quarter trading activity typically experiences lower volatility and liquidity, although BP remains positioned to optimize its global LNG portfolio.
BP Cost Reductions Face Execution Challenges
Thomson confirmed that BP has delivered $4 billion in structural cost reductions since 2023. However, inflation, acquisitions and operational activity have offset much of the improvement.
During questioning from Rothschild & Co Redburn, she explained that inflation contributed approximately $1.5 billion in additional costs, while acquisitions added around $800 million.
Management nevertheless reiterated confidence in achieving an absolute cost base of approximately $18 billion in 2027, supported partly by the full-year effects of portfolio disposals.
BP Defends Integrated Operations and Capital Discipline
O'Neill rejected suggestions of board discussions concerning a potential breakup during questioning from Wolfe Research. She emphasized the value generated by combining upstream production, refining, trading and customer operations.
Operational improvements supported that position. Upstream production remained approximately 2.2 million barrels of oil equivalent daily, while refining availability improved to 96.5%.
Management also acknowledged shortcomings in historical investment decisions following $4 billion in quarterly impairments, primarily affecting transition businesses. O'Neill and Thomson emphasized stronger downside stress testing and more rigorous investment evaluations.
December Update to Define BP's Direction
O'Neill reiterated that BP's strategic direction centers on financial resilience, operational accountability and disciplined investment rather than expanding capital spending simply because more opportunities are available.
The December 15 strategy update will provide additional details on financial frameworks, investment priorities and performance targets, while management continues emphasizing consistent execution across commodity cycles.
BP’s Zacks Rank and Style Scores Signal Positive Prospects
BP currently sports a Zacks Rank #1 (Strong Buy), indicating favorable near-term prospects under Zacks' earnings estimate revision methodology. Its Value Score of A highlights attractive valuation characteristics, while Growth and Momentum Scores of B indicate favorable attributes in both categories. You can see the complete list of today’s Zacks #1 Rank stocks here.
The stock also holds a VGM Score of A, reflecting strong combined value, growth and momentum characteristics. This combination complements its top Zacks Rank, although the ranking remains subject to change as analysts revise earnings estimates following the latest quarterly results.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BP p.l.c. (BP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).