

BorgWarner Inc. BWA is expanding beyond traditional automotive markets through investments in data center power infrastructure, electrification and battery storage. Its growing award pipeline, disciplined cost management and strong cash generation support its long-term prospects. However, weak global vehicle production, particularly in China, continued battery business challenges and customer concentration create uncertainty around its growth outlook.
Let's examine the factors shaping BWA's investment outlook.
BWA's Growth Opportunities Support Long-Term Prospects
BorgWarner is expanding into data center power generation, energy storage and power conversion through its agreement with TurboCell, a subsidiary of Endeavour. The agreement targets more than $300 million in 2027 launch-year sales. Its North Carolina assembly facility is complete, with production trials expected by year-end 2026. Subsystem UL certification was largely completed, while system certification progressed. Customer interest includes multiple hyperscalers, providing an opportunity to diversify beyond cyclical automotive markets.
Its automotive award pipeline is also expanding. Following 12 awards in the first quarter and seven in the second quarter of 2026, BorgWarner secured nine additional awards in the third quarter. These include three turbocharger conquest programs beginning in 2027, an engine control module contract starting in 2029, four eMotor awards in China and a next-generation high-voltage inverter program with a global OEM.
Electrification is another growth avenue. Third-quarter light-vehicle eProduct sales increased 33% year over year to $630 million, while PowerDrive Systems revenues rose to $705 million from $582 million. Its adjusted operating loss narrowed to $5 million from $35 million. Partnerships with FinDreams Battery and onsemi, alongside the Eldor acquisition, further strengthen its electrification portfolio.
BWA's Cost Controls and Cash Generation Support Returns
BorgWarner's disciplined cost management continues to support profitability despite softer automotive production. Third-quarter 2026 adjusted operating margin improved 20 basis points (bps) year over year to 10.9%, while GAAP operating margin expanded 180 bps to 8.7%. Adjusted operating income was $381 million. Management expects a full-year adjusted operating margin of 10.7-10.9% compared with 10.7% in 2025.
Strong cash generation further supports its financial flexibility. The company reduced gross debt by $864 million, repurchased approximately $175 million of shares and paid $35 million in dividends during the third quarter. Year-to-date share repurchases totaled $425 million. With cash, cash equivalents and restricted cash of $1.58 billion and expected full-year free cash flow of $900 million-$1.1 billion, BorgWarner remains positioned to fund investments and shareholder returns. An additional $1 billion share repurchase authorization reinforces this commitment.
Weak Automotive Markets and Battery Business Weigh on Growth
BorgWarner remains heavily dependent on automotive markets, with more than 80% of sales tied to light vehicles. Third-quarter 2026 net sales declined 2.9% year over year to $3.49 billion, while organic sales fell 3.1%. Management expects weighted light-vehicle production to decline 1-2% in 2026 and full-year organic sales to fall 2.5-4%. Revenue guidance was narrowed to $14 billion-$14.2 billion from $14 billion-$14.3 billion.
China presents additional challenges, with management expecting light-vehicle production to decline 6-8% in 2026. Prolonged weakness could pressure order volumes, delay program ramp-ups and weigh on regional revenues. Inflation, commodity volatility and supply-chain uncertainty also remain concerns. Despite improved margins, adjusted operating income declined to $381 million from $385 million a year earlier.
The Battery Energy Systems business remains another drag. Third-quarter revenue declined approximately 41% year over year to $78 million from $132 million. Management expects an approximately $250 million reduction in full-year battery sales, representing a 170-bp drag on organic growth. Although restructuring and the charging-business exit narrowed the segment's adjusted operating loss to $3 million from $7 million, it has yet to return to profitability.
Customer concentration adds to these risks. Volkswagen accounted for approximately 13% of 2025 sales, and Ford represented 12%, while the ten largest customers generated 71% of total revenue. This exposes BorgWarner to changes in major automakers' production schedules, sourcing decisions and vehicle-platform strategies.
BorgWarner is building new growth avenues through data center infrastructure, electrification and a stronger award pipeline, while disciplined cost controls support margins and cash generation. However, weak automotive production, battery business losses and customer concentration continue to temper these positives. Until these challenges ease and new opportunities translate into sustained growth, the stock merits a cautious outlook.
BorgWarner Inc. Price and Consensus
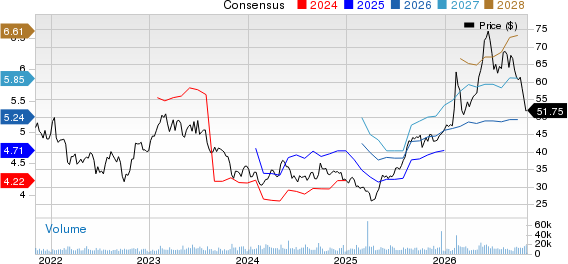
BorgWarner Inc. price-consensus-chart | BorgWarner Inc. Quote
BWA's Zacks Rank & Key Picks
BorgWarner currently carries a Zacks Rank #3 (Hold).
Some better-ranked stocks in the Auto space are Honda Motor HMC, Lucid Group, Inc. LCID and Toyota TM. HMC, LCID and TM carry a Zacks Rank #2 (Buy). You can see the complete list of today's Zacks #1 (Strong Buy) Rank stocks here.
The Zacks Consensus Estimate for HMC's current-year earnings is pegged at $2.32 per share, indicating a 210% year-over-year increase. The estimate for earnings has moved northward over the past 60 days.
The Zacks Consensus Estimate for LCID's current-year loss is pegged at $12.15 per share. Its earnings missed the Zacks Consensus Estimate in each of the trailing four quarters, with the average negative earnings surprise being 30.3%.
The Zacks Consensus Estimate for TM's current fiscal-year earnings is pegged at $21.18 per share, indicating an 8.01% year-over-year increase. The estimate for earnings has moved down over the past 30 days.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BorgWarner Inc. (BWA): Free Stock Analysis Report
Toyota Motor Corporation (TM): Free Stock Analysis Report
Honda Motor Co., Ltd. (HMC): Free Stock Analysis Report
Lucid Group, Inc. (LCID): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).