

GE HealthCare Technologies Inc. GEHC raised its 2026 outlook after stronger third-quarter execution, while executives emphasized productivity improvements and growing demand for precision diagnostics.
The earnings call also exposed investor concerns about fourth-quarter growth, tariff exposure and the sustainability of the recovery in Patient Care Solutions.
GEHC Raises Its 2026 Targets
Chief financial officer William Grogan said improved execution supported a higher adjusted earnings outlook of $4.95-$5.05 per share, up from $4.80-$5.00. GE HealthCare now expects organic revenue growth of approximately 4%, versus its previous 3%-4% range.
Management also raised its adjusted EBIT margin guidance to 15.5%-15.7% and expects free cash flow above $1.6 billion.
In response to a JPMorgan analyst's question about implied fourth-quarter softness, Grogan attributed the expected 3%-4% growth primarily to a difficult Patient Care Solutions comparison, rather than weakening demand.
GE HealthCare Defends Its Orders Pipeline
Chief executive officer Peter Arduini described hospital imaging capital spending as resilient despite macroeconomic concerns. Responding to a BofA Securities analyst, he said large equipment installations are planned well in advance and customer opportunities remain strong.
Organic orders rose 4%, while book-to-bill reached 1.03 times. Backlog was $23.7 billion, up 12% year over year.
Asked about quarterly order volatility, Arduini pointed to the timing of large contracts and said the fourth-quarter order pipeline looked stronger than the third quarter's.
GEHC Sees Productivity Supporting Margins
Grogan attributed margin improvement to higher volume, pricing, cost productivity and lower tariff expense, partially offset by inflation in memory chips and supply-chain costs.
Adjusted EBIT margin reached 16.6%, up 180 basis points year over year. Adjusted earnings of $1.34 per share exceeded the Zacks Consensus Estimate of $1.21, while $5.51 billion in revenue topped the $5.36 billion estimate.
During questions from BTIG, Arduini identified potential Section 232 tariffs as an important uncertainty for 2027. Grogan maintained that pricing and supplier initiatives could help manage persistent inflation and tariffs.
GE HealthCare Technologies Inc. Price, Consensus and EPS Surprise
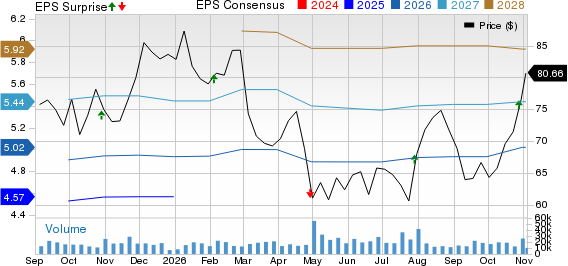
GE HealthCare Technologies Inc. price-consensus-eps-surprise-chart | GE HealthCare Technologies Inc. Quote
GE HealthCare Expands Its Diagnostics Ambitions
Arduini highlighted Pharmaceutical Diagnostics as a cornerstone of the company's precision-care strategy. The segment delivered 13.8% organic revenue growth, supported by contrast media and radiopharmaceuticals.
He said Flyrcado adoption was progressing toward management's $500 million exit revenue run-rate target for 2028. Weekly doses reached approximately 680 for the week ended Oct. 23.
The planned $945 million acquisition of SOFIE Biosciences would extend GE HealthCare's U.S. PET radiopharmaceutical production and distribution capabilities. Asked by a BMO Capital Markets analyst, Arduini emphasized broader supply-chain control and future tracer opportunities over an immediate acceleration in Flyrcado sales.
GEHC's Patient Care Recovery Faces Another Test
Patient Care Solutions posted 8.8% organic revenue growth as improved supplier execution and backlog conversion helped reverse earlier operational challenges.
Arduini credited daily management under the Heartbeat operating system for better product availability. He told a JPMorgan analyst that delayed monitoring installations and supplier improvements should continue supporting operations into 2027.
However, Grogan noted that the fourth quarter faces a comparison against a roughly $45 million product-hold release benefit in the prior year. Arduini also confirmed that the segment's leadership transition would not delay its strategic assessment.
GE HealthCare Maintains Its Medium-Term Focus
Arduini reaffirmed confidence in the company's 2028 growth and margin objectives, emphasizing differentiated new products, disciplined pricing and operating simplification.
He also cautioned that tariff policy remains unsettled. Management plans to provide formal 2027 guidance in February, with product launches and productivity measures central to its outlook.
GEHC's Zacks Rank and Style Scores
GEHC carries a Zacks Rank #2 (Buy), indicating a favorable earnings-estimate revision profile. Its Value Score of B and VGM Score of B complement that ranking, reflecting relatively attractive characteristics under the Zacks scoring framework. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Its Growth Score of C and Momentum Score of D provide a more mixed picture across individual investment styles. The Zacks Rank and Style Scores are complementary indicators rather than guarantees of performance, and the Rank may change as analysts revise estimates following the latest results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
GE HealthCare Technologies Inc. (GEHC): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).