

DENTSPLY SIRONA Inc. XRAY is scheduled to release third-quarter 2026 results on Nov. 5, before the opening bell.
In the last reported quarter, the company’s earnings beat the Zacks Consensus Estimate by 44.44%. It delivered an average earnings surprise of 4.88% in the past four quarters.
XRAY’s Q3 Estimates
The Zacks Consensus Estimate for revenues is pegged at $856 million. The consensus mark for earnings is pinned at 30 cents per share.
Our model estimates for revenues and adjusted EPS are pinned at $857.9 million and 31 cents, respectively.
Factors to Note Ahead of XRAY’s Q3 Results
DENTSPLY SIRONA is likely to have continued grappling with operational headwinds and subdued demand in the third quarter of 2026, although progress under its Return-to-Growth Action Plan may have partially offset these challenges. Management expects revenues to have declined sequentially due to normal seasonality and anticipates third-quarter earnings below the second-quarter level, excluding the 17 cents per share benefit from tariff refunds. Performance across Connected Technology Solutions (“CTS”), Essential Dental Solutions (“EDS”), Orthodontic & Implant Solutions (“OIS”) and Wellspect Healthcare is likely to have remained mixed.
The tariff-related costs, geopolitical uncertainty and continued investments in sales, marketing and R&D are likely to have constrained third-quarter profitability. The impact of the $44 million tariff refund received in the second quarter also creates an unfavorable sequential earnings comparison.
Connected Technology Solutions
CTS is likely to have benefited from continued growth in imaging equipment, particularly in EMEA, and double-digit growth in APAC milling systems. The expansion of the dealer network and improving execution in select Asian markets should also have supported demand. However, CAD/CAM weakness in the Americas, alongside delayed capital equipment purchasing decisions in parts of EMEA amid Middle East geopolitical uncertainty, likely continued to hurt performance.
DS Core's expanding adoption among European dental service organizations should have supported customer engagement, although meaningful revenue contributions from additional digital functionalities are likely to have taken longer. Our model estimates segmental revenues to decrease 7.5% organically to $245.1 million
Essential Dental Solutions
EDS sales are likely to have remained under pressure from lower volumes in the Americas and Europe. Distributor inventory reductions in EMEA, particularly among certain private-equity-owned dealers, likely continued to create a gap between sell-in and underlying demand. While sell-through trends remained relatively stable, inventory normalization may have hurt sales growth.
Management's efforts to strengthen endodontic and restorative portfolios through increased R&D, clinical education and improved commercial execution are expected to support recovery over time. Our model estimates segmental revenues to decrease 7% organically to $341.7 million
Orthodontic & Implant Solutions
OIS is likely to have remained a significant drag, with the Byte business exit and continued softness in U.S. SureSmile demand weighing on results. Premium implant volumes in the Americas could also have remained subdued.
However, stronger value implant performance in EMEA, particularly through MIS, may have partially offset weakness. Investments in implant salesforce training, clinical education and commercial capabilities should have supported customer engagement, although their financial benefits are likely to emerge gradually. Our model estimates segmental revenues to decrease 12.7% organically to $183.3 million
Wellspect Healthcare
Wellspect is expected to have remained a bright spot, supported by new product launches, geographic expansion and improving product adoption. However, lower U.S. distributor inventory levels could have partially offset underlying demand strength. Our model estimates segmental revenues to increase 2.1% organically to $87.8 million.
DENTSPLY SIRONA Inc. Price and EPS Surprise
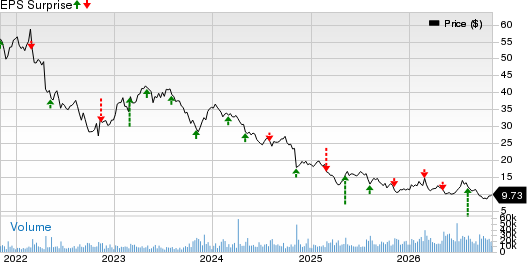
DENTSPLY SIRONA Inc. price-eps-surprise | DENTSPLY SIRONA Inc. Quote
What the Zacks Model Unveils for XRAY
Our proven model does not conclusively predict an earnings beat for XRAY this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an earnings beat. This is not the case here, as you will see below.
XRAY’s Earnings ESP: Earnings ESP, which represents the difference between the Most Accurate Estimate and the Zacks Consensus Estimate, is 0.00%. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
XRAY’s Zacks Rank: DENTSPLY SIRONA currently has a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank stocks here.
Stocks to Consider
Some stocks worth considering from the broader medical space are Glaukos GKOS, Becton, Dickinson and Company BDX and Globus Medical GMED.
Glaukos, currently sporting a Zacks Rank #1, reported third-quarter 2026 earnings per share of 47 cents, which beat the Zacks Consensus Estimate by 491.67%. Revenues of $211 million surpassed the Zacks Consensus Estimate by 24.99%.
Glaukos has an estimated earnings growth rate of 268.8% for 2027. GKOS’ earnings surpassed estimates in three of the trailing four quarters and missed once, the average surprise being 138.6%.
Becton, Dickinson and Company, currently carrying a Zacks Rank #2, reported second-quarter 2026 adjusted EPS of $3.23, which beat the Zacks Consensus Estimate by 2.87%. Revenues of $4.98 billion surpassed the Zacks Consensus Estimate by 1.81%.
Becton, Dickinson and Company has an estimated long-term earnings growth rate of 1.1%. BDX’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 2.94%.
Globus Medical, carrying a Zacks Rank of 2 at present, reported a second-quarter fiscal 2026 adjusted EPS of $1.34, which beat the Zacks Consensus Estimate by 19.6%. Revenues of $790 million missed the Zacks Consensus Estimate by 0.35%.
Globus Medical has an estimated long-term earnings growth rate of 12.4%. GMED’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 27.88%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
DENTSPLY SIRONA Inc. (XRAY): Free Stock Analysis Report
Becton, Dickinson and Company (BDX): Free Stock Analysis Report
Globus Medical, Inc. (GMED): Free Stock Analysis Report
Glaukos Corporation (GKOS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).