

monday.com MNDY is scheduled to report its third-quarter 2026 results on Nov. 9, 2026.
For the third quarter 2026, monday.com currently expects total revenues of $368 million to $370 million, suggesting year-over-year growth of 16% to 17%.
The Zacks Consensus Estimate for MNDY’s third-quarter revenues is pegged at $368.34 million, indicating 16.25% year-over-year growth.
The consensus mark for earnings is pegged at $1.43 per share, unchanged over the past 30-day period. The estimate indicates a 23.28% year-over-year decline.
MNDY beat the Zacks Consensus Estimate for earnings in each of the trailing four quarters, with an average surprise of 23.56%.
Let us see how things have shaped up for the upcoming announcement.
monday.com Ltd. Price and EPS Surprise
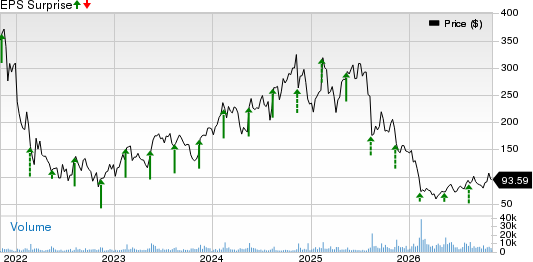
monday.com Ltd. price-eps-surprise | monday.com Ltd. Quote
Key Factors Expected to Shape MNDY's Q3 Results
monday.com’s third-quarter 2026 results are likely to reflect an AI-led transition. For the third quarter, the company guided non-GAAP operating income to be between $57 million and $59 million, implying a margin of roughly 16%. The outlook assumed no rebound in performance marketing and net dollar retention (NDR) of nearly 108%.
AI Work Platform and work management are likely to have been key drivers. AI product ARR doubled sequentially in the second quarter and represented 17% of net new ARR, while the seat-plus-credit pricing model launched in May is expected to aid third-quarter results as customers topped up credits. In July, total ARR crossed $1.5 billion. In September, monday.com unveiled the Elevate ‘26 program, featuring Elevate Labs, where attendees build working AI agents, and its first Done Awards, which recognize customer-built agents and vibe apps and are likely to have deepened agent adoption.
In CRM and service, both received dedicated product development, go-to-market teams and investment roadmaps after second-quarter results in August, which are likely to have sharpened execution. However, monday dev’s strategy was being reworked as developer workflows changed, a probable drag. Enterprise momentum is expected to have helped, as customers above $100,000 in ARR rose 37% to 2,019 in the second quarter, while current remaining performance obligations of $750 million, up 27%, offered visibility.
On costs, the roughly 20% global workforce reduction announced on July 22 is expected to have delivered annualized savings of nearly $100 million, mostly reinvested in talent, product and AI, though restructuring execution risk is likely to have weighed.
Capex stayed modest, with property and equipment purchases of $3.8 million and capitalized software of $1.1 million in the second quarter, supporting 2026 adjusted free cash flow guidance of $280-$290 million. Exhaustion of the $870 million buyback is likely to have boosted per-share metrics, while 196,829 shares were donated to the monday.com Foundation in the third quarter.
Headwinds persisted. A stronger shekel is expected to have hurt operating margin by 100-200 basis points, given Israel-based R&D costs. NDR is likely to have faced modest pressure while lapping 2024-2025 price increases. Top-of-funnel volatility, softer down-market conditions, below-expected tier upgrades and longer enterprise sales cycles are expected to have weighed, while non-GAAP gross margin dipped to 89% in the second quarter.
Overall, AI monetization, enterprise strength and leaner costs are likely to have largely outweighed these near-term pressures in the third quarter of 2026.
What Our Model Says About MNDY Stock
Our proven model does not conclusively predict an earnings beat for Take-Two this time around. According to the Zacks model, the combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy), or 3 (Hold) increases the odds of an earnings beat. However, this is not the case here, as you can see below.
MNDY has an Earnings ESP of 0.00% and a Zacks Rank #2 at present. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Stocks to Consider
Here are some stocks worth considering, as our model shows that these have the right combination of elements to beat earnings this season.
Analog Devices, Inc. ADI presently has an Earnings ESP of +2.23% and a Zacks Rank #2. ADI’s shares have surged 52.2% year to date. ADI is set to report its third-quarter 2026 results on Nov. 24. You can see the complete list of today’s Zacks #1 Rank stocks here.
Microchip Technology MCHP has an Earnings ESP of +3.31% and a Zacks Rank #2 at present. MCHP’s shares have gained 19.5% year to date. MCHP is set to report its second-quarter fiscal 2027 results on Nov. 5, 2026.
NVIDIA Corporation NVDA currently has an Earnings ESP of +3.46% and carries a Zacks Rank #2. NVDA’s shares have returned 8.4% year to date. NVDA is set to report its third-quarter fiscal 2027 results on Nov. 17, 2026.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
monday.com Ltd. (MNDY): Free Stock Analysis Report
Analog Devices, Inc. (ADI): Free Stock Analysis Report
NVIDIA Corporation (NVDA): Free Stock Analysis Report
Microchip Technology Incorporated (MCHP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).