

Sterling Infrastructure, Inc. STRL combines rapid earnings growth and expanding mission-critical demand with a more complicated margin and cash-conversion picture. The investment question is whether that growth can translate into durable returns as the business mix changes.
The valuation has become more supportive, but execution remains central. Investors must balance a discounted earnings multiple, a net cash position and favorable Zacks signals against lower E-Infrastructure margins and heavier working-capital needs.
Sterling's Growth Case Is Powerful but Uneven
Third-quarter revenues surged 127% year over year to $1.56 billion, while adjusted earnings climbed 118% to $7.58 per share and beat the Zacks Consensus Estimate by 24.9%. E-Infrastructure Solutions generated 83% of quarterly revenues, making mission-critical site development and electrical work the core growth driver.
Sterling Infrastructure, Inc. Price and Consensus
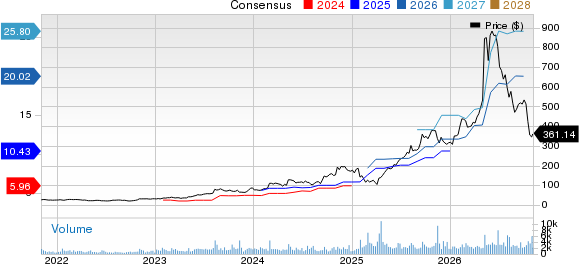
Sterling Infrastructure, Inc. price-consensus-chart | Sterling Infrastructure, Inc. Quote
Quanta Services, Inc. PWR also serves load-center and energy infrastructure markets and reported record total backlog in its latest quarter. EMCOR Group, Inc. EME operates across mechanical and electrical construction and mission-critical data-center services, providing relevant context for the broader infrastructure spending cycle.
STRL's Valuation Looks Discounted to Its History
STRL trades at 14.5X forward 12-month earnings, below the Zacks sub-industry’s 20.49X multiple and its own five-year median of 18.51X. That discount improves the valuation case after the stock’s decline.
The Value Score of C keeps the discount in perspective. Sterling screens cheaper than its sub-industry and historical median, but the mid-range score suggests valuation is not an unambiguous strength. Continued earnings delivery remains important to justify the lower multiple.
Sterling's CEC Expansion Brings Margin Trade-Offs
CEC expands Sterling’s mission-critical electrical capabilities and broadens the scope it can pursue alongside site development. The business generated $425.6 million of third-quarter revenues, and management sees CEC potentially exceeding $1 billion of revenues in 2026.
The trade-off is margin mix. E-Infrastructure operating margin fell to 22.6% from 25.6% a year earlier as CEC became a larger contributor. Electrical work carries more material content and structurally lower margins, while rapid hiring and project deployment add execution demands even as CEC’s own margins improve.
STRL's Balance Sheet Supports Strategic Flexibility
Sterling ended September with $216.9 million of cash and approximately $95.3 million of debt, leaving net cash of about $122 million. Operating cash flow reached $427.1 million in the first nine months of 2026. The company also had $267 million remaining under its share-repurchase authorization and access to a $1.5 billion revolving credit facility.
Cash conversion is the counterweight. Trailing cash-flow conversion of 110.5% was below Sterling’s 138.4% median, while free-cash-flow conversion of 85.8% trailed its 113.3% median. Accounts receivable also rose sharply as E-Infrastructure activity expanded, which could keep near-term cash generation uneven.
Sterling's Ratings Favor Momentum Over Value
The bottom line is constructive but not one-sided. Sterling’s growth, discounted forward multiple and financial flexibility support the case for the shares, while CEC-related margin dilution and weaker cash conversion argue for continued attention to execution rather than treating valuation alone as a buy signal.
STRL currently carries a Zacks Rank #2 (Buy). Its Momentum Score of A and VGM Score of A support a favorable near-term setup when paired with a top Zacks Rank, while the Growth Score of B aligns with the earnings profile. The Value Score of C is less emphatic, leaving margin improvement and cash conversion important to the investment decision.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Sterling Infrastructure, Inc. (STRL): Free Stock Analysis Report
Quanta Services, Inc. (PWR): Free Stock Analysis Report
EMCOR Group, Inc. (EME): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).