

Dycom Industries, Inc. DY is accelerating its acquisition-driven expansion beyond traditional fiber infrastructure, strengthening its presence in data center electrical systems, structured cabling and mission-critical infrastructure. Strategic acquisitions, particularly Power Solutions and National Technology Integrators (“NTI”), are transforming Dycom into a more diversified digital infrastructure services provider.
Can Acquisitions Unlock New Growth Opportunities?
The acquisition of Power Solutions has significantly expanded Dycom's electrical contracting capabilities, positioning it to capitalize on accelerating hyperscale data center investments. Meanwhile, the fiscal second-quarter 2027 acquisition of NTI strengthens its expertise in inside-plant structured cabling, advanced audiovisual systems and security solutions.
NTI contributed approximately $22.9 million in quarterly revenues, exceeding initial expectations. The acquisition also expands Dycom's geographic reach and creates cross-selling opportunities across Power Solutions and its Communications businesses.
The Building Systems segment illustrates the success of this diversification strategy. Second-quarter fiscal 2027 revenues reached $397.5 million, representing approximately 20% of consolidated revenues. Adjusted EBITDA totaled $97.2 million, with an impressive 24.5% margin, supported by operating leverage and favorable project execution.
Management raised its fiscal 2027 Building Systems revenue outlook to $1.58-$1.65 billion, reflecting stronger Power Solutions contributions and NTI's addition. Dycom is also actively pursuing further acquisitions to expand geographically and enter adjacent markets.
However, acquisition integration challenges, workforce constraints and increased financial leverage warrant attention. Notional net debt stood at approximately $2.50 billion at second-quarter end.
Nonetheless, strong data center demand, expanding service capabilities and acquisition synergies position Dycom to diversify revenue streams and strengthen long-term profitability beyond its core fiber operations.
How Are Competitors Expanding Beyond Core Infrastructure?
MasTec, Inc. MTZ is strengthening its presence in data center and mission-critical infrastructure through strategic acquisitions and diversified service offerings. MasTec's acquisition of The Superior Group for approximately $1.65 billion significantly expands its electrical contracting capabilities and exposure to hyperscale data center projects.
The transaction enhances MasTec's skilled workforce, customer relationships and opportunities across technology-intensive infrastructure markets. MasTec's diversified operations across communications, power delivery and energy infrastructure further support long-term growth.
Quanta Services, Inc. PWR is similarly accelerating expansion through strategic acquisitions targeting electrical, mechanical and specialized infrastructure services. Quanta's acquisitions of Phalcon and Enerfab strengthen its self-perform capabilities and geographic reach across growing data center and industrial markets. Quanta's earlier investments in Cupertino Electric and other specialized contractors further enhance its integrated infrastructure platform.
Strong demand for grid modernization, electrification and AI-related infrastructure supports Quanta's growth prospects. However, acquisition integration and execution risks remain important considerations for both companies.
DY Stock’s Price Performance & Valuation Trend
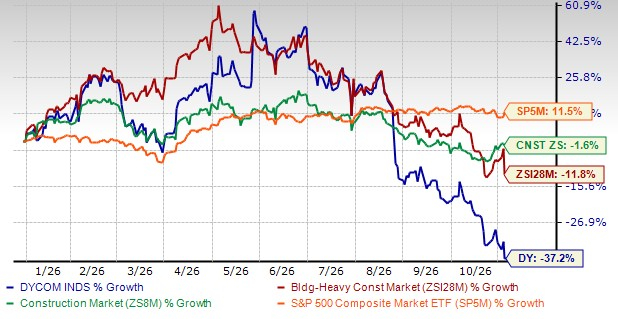
Shares of Dycom have lost 37.2% year to date (YTD), underperforming the Zacks Building Products - Heavy Construction industry, the broader Construction sector and the S&P 500 Index, as shown below.
DY Price Performance (YTD)
Image Source: Zacks Investment Research
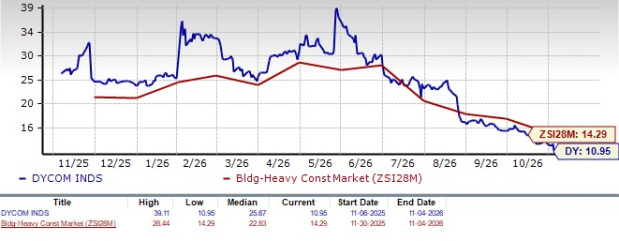
DY stock is currently trading at a discount compared with its industry peers, with a forward 12-month price-to-earnings (P/E) ratio of 10.95, as shown in the chart below.
DY Valuation (P/E F12M)
Image Source: Zacks Investment Research
Earnings Estimate Revision for DY
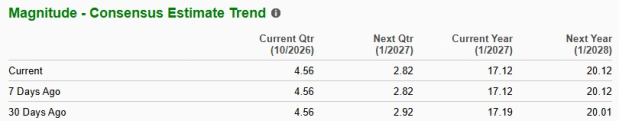
Dycom’s fiscal 2027 earnings estimates decreased to $17.12 per share but increased to $20.12 per share for fiscal 2028 over the past 30 days, as shown below. The estimates imply year-over-year earnings growth of 43% in fiscal 2027 and 17.5% in fiscal 2028.
Image Source: Zacks Investment Research
Dycom stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Dycom Industries, Inc. (DY): Free Stock Analysis Report
Quanta Services, Inc. (PWR): Free Stock Analysis Report
MasTec, Inc. (MTZ): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).