

Primo Brands Corporation PRMB reported third-quarter 2026 results, with both earnings and revenues surpassing the Zacks Consensus Estimates and increasing year over year.
PRMB posted adjusted earnings of 43 cents per share, up 4.9% from 41 cents a year ago and above the Zacks Consensus Estimate of 39 cents.
Net sales increased 3.1% year over year to $1,821 million, exceeding the consensus estimate of $1,812 million. Growth in premium brands and regional spring water supported revenues. Premium water sales surged 24.3%, while Direct Delivery and major retail channels registered growth.
Primo Brands Corporation Price, Consensus and EPS Surprise
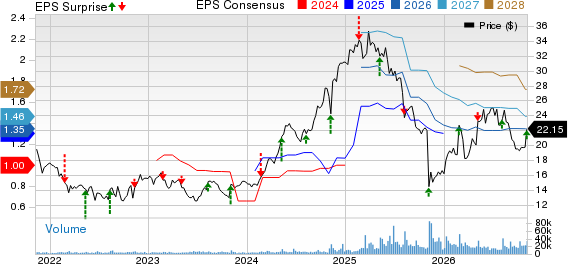
Primo Brands Corporation price-consensus-eps-surprise-chart | Primo Brands Corporation Quote
PRMB Sees Broad-Based Channel Growth
Primo Brands recorded comparable net sales growth of 3.3% year over year. Organic growth contributed 2.9 percentage points, while acquisitions added 0.4 percentage points. Favorable pricing and product mix contributed 5.9%, offsetting a 2.6% decline in volume.
Direct Delivery revenues increased 2.2% year over year to $689.3 million on a comparable basis. Grocery sales grew 3.1% to $355.3 million, while Club revenues advanced 7.5% to $310.1 million. Mass channel sales climbed 9.6% to $237.1 million, reflecting gains across major retail channels.
Away From Home revenues rose 3.9% to $139.9 million. However, Emerging-Specialty & Other sales declined 13.7% to $89.3 million, partially offsetting gains across the distribution network.
Primo Brands Benefits From Premium Water Demand
Regional spring water remained the largest category, with sales increasing 2.9% year over year to $911.5 million. Purified water revenues also grew 2.9% to $573.6 million.
Premium water delivered the strongest category growth, with revenues surging 24.3% to $122.1 million. Meanwhile, Other Water sales declined 3.6% to $31.8 million, and the Other category decreased 3.2% to $182 million on a comparable basis.
Management continues investing in premium offerings and production capabilities. The company highlighted new Mountain Valley Spring Water production capacity as part of its efforts to expand scale and improve productivity.
PRMB Reports Mixed Margin Trends
Gross profit increased 4.9% year over year to $553.9 million. Gross margin expanded 50 basis points to 30.4%, benefiting from revenue growth and lower non-recurring integration costs. Higher transportation expenses partially offset these improvements.
Selling, general and administrative expenses decreased 7.8% to $316.3 million, primarily reflecting lower marketing expenses and reduced amortization of definite-lived intangible assets. Operating income climbed to $248.9 million from $146.4 million a year earlier.
Adjusted EBITDA increased 1.6% year over year to $411 million. However, adjusted EBITDA margin contracted 30 basis points to 22.6%, despite the increase in revenues.
Primo Brands Generates Higher Free Cash Flow
Net cash provided by operating activities from continuing operations increased to $293.6 million from $283.4 million a year earlier. Capital expenditures and additions to intangible assets totaled $83 million compared with $132.7 million in the prior-year quarter.
Free cash flow improved to $210.6 million from $150.7 million. However, adjusted free cash flow declined to $274.2 million from $311.1 million, with lower acquisition, integration and restructuring cash-cost adjustments contributing to the difference.
For the nine months ended Sept. 30, 2026, operating cash flow totaled $625.3 million, while adjusted free cash flow reached $602.9 million.
PRMB Maintains Focus on Balance Sheet Strength
As of Sept. 30, 2026, total debt, excluding unamortized debt costs and discounts, was $5.25 billion. Unrestricted cash and cash equivalents totaled $477.2 million, resulting in net debt of $4.77 billion and a net leverage ratio of 3.32 times.
PRMB paid $43.5 million in cash dividends and spent $22.1 million on share repurchases during the quarter. The board authorized a new $300 million share repurchase program, replacing the previous authorization, which had approximately $41 million of unused capacity. It also declared a quarterly dividend of 12 cents per share.
Primo Brands Updates 2026 Financial Outlook
Primo Brands now expects 2026 comparable net sales growth near the midpoint of its previous 2-4% guidance range, corresponding to approximately 3% growth. The updated outlook follows the company's performance during the first nine months of the year.
The company expects adjusted EBITDA near the lower end of its previously projected $1,465-$1,515 million range. Management maintained base capital expenditure guidance at 4% of net sales and adjusted free cash flow guidance of $790-$810 million.
Primo Brands continues focusing on productivity initiatives, strategic pricing and supply-chain efficiencies to mitigate higher fuel, resin, labor and freight costs. Its capital allocation priorities include reinvesting in operations, reducing net leverage below 3 times and pursuing strategic bolt-on acquisitions.
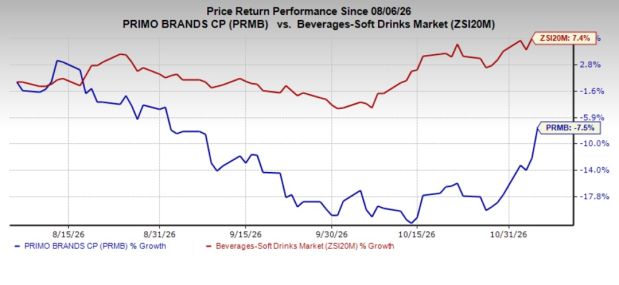
The Zacks Rank #5 (Strong Sell) company’s shares have lost 7.5% in the past three months against the industry’s 7.4% growth.
Image Source: Zacks Investment Research
Stocks to Consider
Some better-ranked stocks have been discussed below:
Lamb Weston Holdings, Inc. LW engages in the production, distribution and marketing of frozen potato products in the United States, Canada, Mexico and internationally. LW currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Lamb Weston's current fiscal-year sales indicates a decline of 0.5%, and the same for earnings indicates growth of 7.6% from the prior-year levels. Lamb Weston delivered a trailing four-quarter earnings surprise of 22.1%, on average.
The J. M. Smucker Company SJM operates as a health and wellness company that provides habit-based and coach-guided lifestyle solutions to address obesity and support a healthy life in the United States. SJM currently carries a Zacks Rank of 2 (Buy).
The Zacks Consensus Estimate for SJM's current fiscal-year sales indicates a decline of 0.02%, and the same for earnings indicates growth of 17.1% from the prior-year levels. SJM delivered a trailing four-quarter earnings surprise of 13.8% on average.
Embotelladora Andina S.A. AKO.B, together with its subsidiaries, produces, bottles, commercializes, and distributes Coca-Cola trademark beverages in Chile, Brazil, Argentina, and Paraguay. The company currently carries a Zacks Rank of 2.
The Zacks Consensus Estimate for AKO.B’s current fiscal-year sales and earnings indicates growth of 12.4% and 17.9%, respectively, from the year-ago reported figures. The company delivered a trailing four-quarter negative earnings surprise of 4.1%, on average.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Primo Brands Corporation (PRMB): Free Stock Analysis Report
The J. M. Smucker Company (SJM): Free Stock Analysis Report
Embotelladora Andina S.A. (AKO.B): Free Stock Analysis Report
Lamb Weston (LW): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).