

Expeditors International of Washington, Inc. (EXPD is generating faster earnings growth, better operating efficiency and broad demand across its logistics businesses. Those gains strengthen the investment case, but the stock’s premium valuation raises the bar for continued execution.
The key question is whether earnings momentum and productivity improvements can keep supporting the shares as investors pay more than Expeditors’ historical valuation and far more than comparable transportation benchmarks.
EXPD Earnings Growth Strengthens the Bull Case
The Zacks Consensus Estimate for 2026 earnings is $8.46 per share, up from $5.95 in 2025. That implies projected year-over-year growth of 42.2%, while the 2026 estimate has moved 9.2% higher over the past four weeks.
Expeditors International of Washington, Inc. Price and EPS Surprise
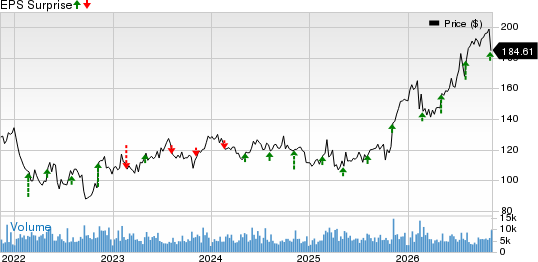
Expeditors International of Washington, Inc. price-eps-surprise | Expeditors International of Washington, Inc. Quote
The improvement follows a strong third quarter, when Expeditors reported earnings of $2.65 per share, up 61.6% year over year. Broader transportation results also show pockets of strength. XPO, Inc. (XPO) reported third-quarter revenue growth of 12.4% and a 75.6% increase in operating income, while North American less-than-truckload tonnage per day increased 5%.
Expeditors Efficiency Supports Margin Expansion
Expeditors’ third-quarter operating income climbed 54.6% to $445.4 million, and operating margin improved to 10.8% from 10% a year earlier. Headcount increased only 1% as revenues rose much faster, helping operating efficiency reach 36.7%.
Cost actions could add another layer of support. The Global Technology restructuring is expected to reduce annual costs by about $50 million, while investments in artificial intelligence, temperature-controlled facilities and logistics technology are intended to improve productivity and service capabilities.
EXPD Valuation Leaves Less Room for Error
EXPD trades at 24.09X forward 12-month earnings, above its five-year median of 22.33X. The multiple also exceeds 15.14X for the Zacks sub-industry, 15.18X for the Transportation sector and 18.83X for the S&P 500.
That premium makes continued earnings delivery important. Freight conditions can still support results, but they remain cyclical. Matson, Inc. (MATX) reported a 16% year-over-year increase in third-quarter China service container volume and cited strong demand and elevated freight rates, illustrating how favorable freight economics can boost transportation earnings while conditions remain supportive.
Expeditors Liquidity Supports Capital Returns
Expeditors ended September with $1.09 billion in cash and cash equivalents. It repurchased $197.3 million of shares during the third quarter and returned $946 million through dividends and buybacks during the first nine months of 2026.
Its $3 billion share-repurchase authorization provides additional flexibility. Still, trailing 12-month cash-flow conversion of 93.3% remains below its 108.1% median, while free-cash-flow conversion of 88.6% is below the 102.9% median as working-capital needs have absorbed cash.
EXPD Signals Favor Momentum Over Value
The bottom line is that EXPD combines rapid earnings growth, operating leverage and substantial capital returns with a valuation that already reflects considerable optimism. That mix can support the shares if execution remains solid, but the premium multiple leaves less room for disappointment.
EXPD currently carries a Zacks Rank #1 (Strong Buy). Its Momentum Score of A is favorable for investors focused on near-term trends, while the Value Score of D points to a less attractive valuation profile. The Growth Score of C and VGM Score of C are more neutral, so the broader Style Score picture is less supportive than the Rank and Momentum signals alone. You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Expeditors International of Washington, Inc. (EXPD): Free Stock Analysis Report
Matson, Inc. (MATX): Free Stock Analysis Report
XPO, Inc. (XPO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).