

Nu Holdings Ltd. NU will report its third-quarter 2026 results on Nov. 12, after market close.
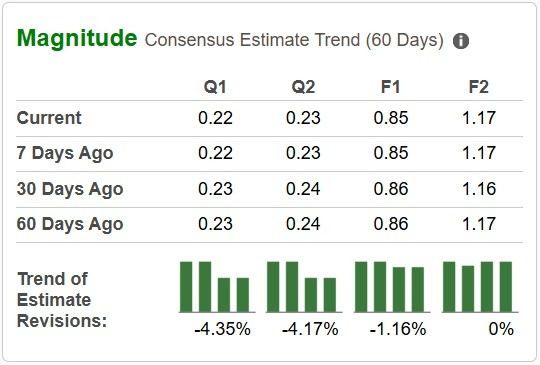
The Zacks Consensus Estimate for third-quarter earnings per share stands at 22 cents, indicating 29.41% year-over-year growth. The consensus estimate for revenues is pegged at $5.70 billion, suggesting a 36.60% year-over-year increase. There has been a slight downward revision in the to-be-reported quarter's earnings estimate in the past 30 days.
Image Source: Zacks Investment Research
NU has a strong history of earnings surprises. Earnings surpassed the Zacks Consensus Estimate in three of the trailing four quarters and missed in one, with the average earnings surprise being 5.97%.
Here Is What Our Quantitative Model Predicts for NU
Our proven model does not conclusively predict an earnings beat for NU this time. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat, which is not the case here. You can uncover the best stocks to buy or sell before they're reported with our Earnings ESP Filter.
NU has an Earnings ESP of -5.62% and a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.
Key Factors to Watch Ahead of NU’s Q3 Results
Nu Holdings is expected to report continued business growth in third-quarter 2026, supported by rising customer activity across its Latin American markets. The company entered the quarter with 139 million customers, an 83.5% monthly activity rate and average monthly revenue per active customer of about $17, providing a starting point.
Brazil is likely to have remained the primary earnings contributor, with deeper customer relationships supporting card spending, lending and fee income. The July launch of Croma, aimed at customers with higher banking needs, may have encouraged greater product usage during the quarter, although its immediate revenue contribution is likely to have been limited.
Loan growth is expected to have supported net interest income, building on June's $39.4 billion credit portfolio. Greater exposure to higher-yielding unsecured loans could have aided margins, while deposits likely have provided sufficient funding. Management's efforts to improve lending yields and funding costs may also have helped sustain profitability.
Credit quality remains an important watchpoint. The 90-day-plus delinquency rate rose to 6.9% in June, making third-quarter provisions and collection trends worth monitoring. Although underwriting improvements may have supported risk-adjusted returns, lending to riskier customers could have raised credit costs. Expansion-related spending is likely to have pressured operating efficiency.
Mexico and Colombia are also expected to have contributed additional customers and revenue. Mexico's move to full digital banking in August may have supported engagement, although broader financial benefits will take time. Nu also entered the United States in September, but that launch is unlikely to have materially affected quarterly earnings. Overall, profit growth appears achievable.
NU’s Price Performance & Valuation
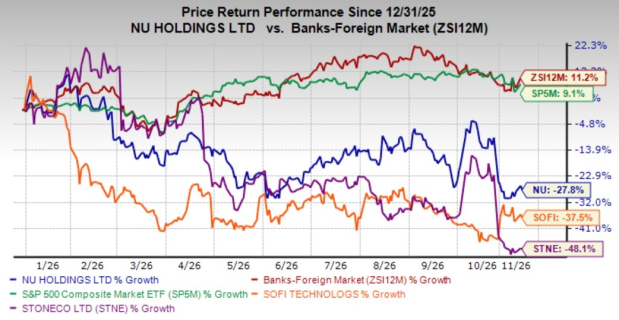
NU shares have declined 27.8% so far in the year, narrower than close fintech peers SoFi Technologies, Inc. SOFI and StoneCo Ltd. STNE over a comparable recent period. SoFi and StoneCo shares have plunged 37.5% and 48.1%, respectively. The comparison suggests that investors have shown relatively greater confidence in Nu’s performance and growth outlook, as its shares have held up better than those of close fintech peers amid broader sector weakness.
Image Source: Zacks Investment Research
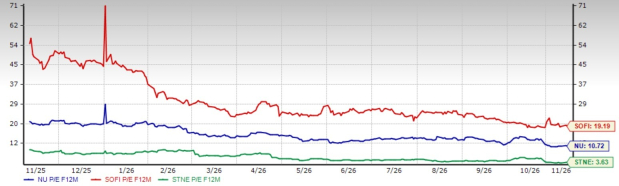
NU trades at approximately 10.72 times forward earnings. This is well below SoFi Technologies’ forward multiple of about 19.19 times but considerably above StoneCo’s 3.63 times.
NU’s discount to SOFI suggests a relatively attractive valuation, supported by its expanding customer base, improving monetization and strong profitability. Meanwhile, its premium over STNE appears justified by its larger digital banking platform, diversified geographic presence and stronger earnings growth prospects. However, rising credit costs, exposure to Latin American economic conditions and expansion-related expenses could limit valuation upside. NU’s relatively reasonable valuation supports a cautious but constructive investment stance ahead of its third-quarter results.
Valuation
Image Source: Zacks Investment Research
How to Play NU Stock Ahead of Q3 Earnings?
NU's investment case remains supported by a growing customer base, rising monetization of existing accounts and an efficient digital operating model. The company's expanding credit portfolio and deposit franchise offer room for income growth, while newer products in Brazil could help improve revenue per active customer. Mexico and Colombia add diversification, although their profitability and credit performance deserve close attention.
The main concern is whether faster lending growth, particularly in unsecured products, will translate into higher provisions as borrowers face financial pressure. Costs linked to new products and geographic expansion could moderate near-term earnings momentum. With encouraging operating trends balanced by credit risk and investment spending, retaining existing exposure to NU appears preferable to increasing positions until third-quarter results provide clearer evidence of sustainable growth.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Nu Holdings Ltd. (NU): Free Stock Analysis Report
StoneCo Ltd. (STNE): Free Stock Analysis Report
SoFi Technologies, Inc. (SOFI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).