

Onto Innovation Inc. ONTO continues to make progress in improving profitability, supported by operational efficiencies and strong demand across its product portfolio. In the third quarter of 2026, the company reported a non-GAAP gross margin of 57.6%, reflecting a sequential improvement of 60 basis points (bps). This represents an expansion of 300 bps compared with the fourth quarter of 2025, highlighting the effectiveness of its ongoing operational improvement initiatives.
The margin expansion reflects Onto Innovation’s continued focus on transitioning to an extended factory model, improving operational productivity and enhancing manufacturing efficiency. The company has benefited from operating in lower-cost labor markets, reducing exposure to duties and tariff-related risks, and localizing supply chains. These initiatives have also helped lower freight expenses by reducing the need to transport components across regions.
Strong revenue growth has accompanied these improvements. Third-quarter revenues reached approximately $410 million, increasing 19% sequentially and nearly 90% year over year. Advanced packaging and specialty device products recorded 35% sequential growth, supported by strong Dragonfly adoption and a recovery in power and specialty device inspection businesses.
Onto Innovation expects its gross margin expansion to continue in the fourth quarter. Management anticipates an additional 50-bp improvement, bringing gross margin slightly above 58%. This would represent a cumulative improvement of approximately 350 bps since the fourth quarter of 2025.
The company also raised its fourth-quarter revenue guidance to $430-$450 million, representing sequential growth of more than 7% at the midpoint. Operating margin is projected to reach 34% at the midpoint of guidance compared with 32.6% in the third quarter.
Management expects further gross margin expansion in 2027, indicating that an average quarterly improvement of approximately 50 bps is a reasonable expectation. However, rising component costs and supply-chain pricing pressures remain challenges. Onto Innovation is addressing these headwinds through design modifications, reduced memory usage and additional productivity improvements, while maintaining its focus on sustained margin expansion.
Taking a Look at ONTO’s Competitors
KLA Corporation’s KLAC non-GAAP gross margin reached 62.7% in the first quarter of fiscal 2027, slightly exceeding the midpoint of management’s guidance. Non-GAAP operating margin improved 240 bps sequentially to a record 46.1%, driven by higher revenues and operating leverage. However, elevated memory component costs continue to pressure margins, while optics lead times and a less favorable business mix remain additional headwinds. For the second quarter of fiscal 2027, management expects non-GAAP gross margin of 62.5%, plus or minus 1 percentage point. Cost-reduction measures, memory optimization and pricing initiatives are expected to support a return to the 63-64% gross margin target by mid-to-late 2027 into 2028.
Applied Materials’ AMAT margins are benefiting from value-based pricing, improved cost efficiency and growing demand for advanced semiconductor technologies. In the third quarter of fiscal 2026, non-GAAP gross margin expanded 150 bps year over year to 50.4%, marking the 13th consecutive quarter of year-over-year growth. Semiconductor Systems' non-GAAP gross margin increased to 55.4% from 53.5% a year ago. Non-GAAP operating margin improved to 34% from 30.7%, reflecting stronger operating leverage. The company expects fourth-quarter non-GAAP gross margin of approximately 50.4%, supported by a favorable product mix and increasing demand for higher-value AI-related applications, alongside continued cost improvements.
ONTO Price Performance, Valuation and Estimates
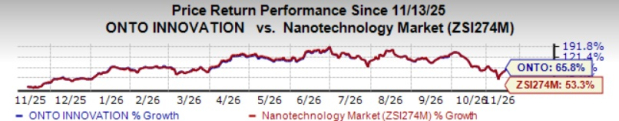
ONTO’s shares have gained 65.8% in the past year, outperforming the Zacks Nanotechnology industry’s growth of 53.3%.
Image Source: Zacks Investment Research
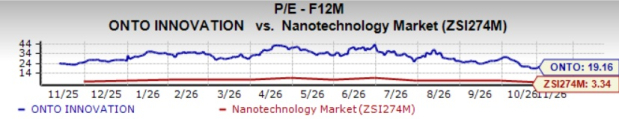
On a forward price-to-earnings basis, ONTO’s shares trade at 19.16X, higher than the industry’s 3.34X.
Image Source: Zacks Investment Research
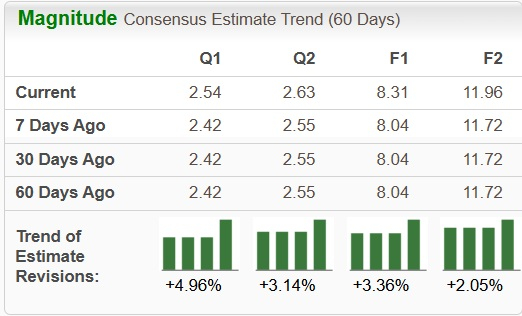
The Zacks Consensus Estimate for ONTO has been revised upward for 2026 over the past 60 days.
Image Source: Zacks Investment Research
Onto Innovation currently has a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Onto Innovation Inc. (ONTO): Free Stock Analysis Report
KLA Corporation (KLAC): Free Stock Analysis Report
Applied Materials, Inc. (AMAT): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).