

OPKO Health, Inc. OPK is well-positioned for growth, supported by Global Products revenue growth, partnered product contributions and pipeline progress. However, clinical and regulatory risks, pressure on partner-product economics and slow RAYALDEE expansion in China remain key concerns.
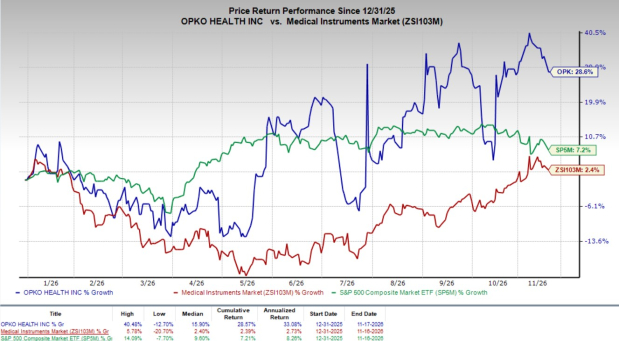
Shares of this Zacks Rank #3 (Hold) company have gained 28.6% in the year-to-date period, outperforming the industry's 2.4% growth and the S&P 500’s 7.2% rise.
This renowned multinational biopharmaceutical and diagnostics company has a market capitalization of $1.20 billion. OPK predicts 30% bottom-line growth for 2026. The company’s earnings surpassed estimates in three of the trailing four quarters and met in one, the average surprise being 39.7%.
Image Source: Zacks Investment Research
Factors Favoring OPK Stock
Strengthening Global Products Business: OPKO Health’s Global Products business is benefiting from growth in its pharmaceutical portfolio. In the third quarter of 2026, the segment’s product revenues increased 11% year over year to $41.8 million, led by OPKO Iberia America and continued growth in RAYALDEE. NGENLA is also expanding globally through Pfizer, gaining share in the U.S. market, maintaining its position in Japan and retaining its leadership in Europe. The ongoing shift from daily to weekly growth hormone therapies and potential label expansions could further support NGENLA’s growth.
Growing Contributions From Partnered Products: OPKO Health is benefiting from its collaborations with major pharmaceutical companies. Its collaboration with Eli Lilly generated $5.8 million in mazdutide royalties during the third quarter, reflecting continued commercialization by Innovent in China. Pfizer’s global commercialization of NGENLA continues to support OPKO’s Innovative Biotech business. The company’s collaborations with Regeneron, Merck, Entera Bio and BARDA also provide opportunities to advance its programs and generate future development and commercialization milestones.
Progress Across a Broad Clinical Pipeline: OPKO Health’s Innovative Biotech portfolio is advancing across oncology, immunology, infectious diseases and endocrinology. ModeX continued clinical development of its multispecific antibody candidates, with 41 patients enrolled in the Phase I study of MDX-2001 and 16 patients enrolled in the MDX-2004 study as of September 2026. MDX2003 received approval to begin trials in Europe, with eight additional sites in Spain and Italy expected by early 2027. The company completed enrollment in the planned Phase I cohorts for MDX-2301 and is targeting mid-2027 for first-in-human studies of its in vivo CAR-T candidate, MDX3001. Additional programs, including OPKO 88006 and its acromegaly candidate, could provide further clinical catalysts in 2027.
Factors That May Offset OPK’s Gains
Clinical and Regulatory Risks Across Pipeline Programs: Several of OPKO Health’s pipeline candidates remain in early-stage development and must demonstrate safety and efficacy in clinical trials. Management acknowledged that the tolerability of subcutaneous dosing for MDX2001 and MDX2004 remains unproven, with further development dependent on clinical findings. The first-in-human timeline for MDX3001 shifted to mid-2027 due to new regulatory requirements in China. MDX2004's optimal tumor indications remain undetermined, while the timing of Merck's potential Phase II Epstein-Barr virus vaccine study depends on its development decisions.
Headwinds in Partner-Product Economics: Despite NGENLA’s global progress, OPK’s Innovative Biotech segment continues to face pressure from the daily growth hormone market. Pfizer's NGENLA-related gross profit share was affected by negative gross-to-net adjustments for Genotropin in the U.S. market, partially offsetting NGENLA's expanding sales. This offset could temper the benefits of NGENLA’s ongoing market-share gains.
Slow Progress in RAYALDEE’s China Expansion: Although RAYALDEE continues to contribute to Global Products growth, its expansion in Greater China remains gradual. OPK’s partner, Nicoya, is currently marketing the product through an economic zone in Macau while awaiting Chinese FDA approval for broader national coverage. Management expects sales to increase following approval, but the timing remains uncertain, potentially delaying the contribution from this market.
OPKO Health, Inc. Price
OPKO Health, Inc. price | OPKO Health, Inc. Quote
Estimate Trends of OPK
OPKO Health is witnessing a positive estimate revision trend for 2026. In the past 30 days, the Zacks Consensus Estimate for its loss per share has narrowed by 3 cents to 20 cents.
The Zacks Consensus Estimate for the company’s fourth-quarter 2026 revenues and loss per share is pegged at $67.7 million and 7 cents, respectively. The estimate for revenues indicates a 54.4% fall from the year-ago quarter’s reported number, while that for loss implies a 75% decline.
Stocks to Consider
Some better-ranked stocks from the broader medical space are Glaukos GKOS, Intuitive Surgical ISRG and West Pharmaceutical Services WST.
Glaukos, currently flaunting a Zacks Rank #1 (Strong Buy), reported third-quarter 2026 adjusted earnings per share (EPS) of 47 cents, which surpassed the Zacks Consensus Estimate by 491.7%. Revenues of $211 million beat the Zacks Consensus Estimate by 25%. You can see the complete list of today’s Zacks #1 Rank stocks here.
GKOS has an estimated earnings growth rate of 155.6% for 2026. The company’s earnings beat estimates in three of the trailing four quarters and missed once, the average surprise being 138.6%.
Intuitive Surgical, currently carrying a Zacks Rank #2 (Buy), reported third-quarter 2026 adjusted EPS of $3.00, which beat the Zacks Consensus Estimate by 13.6%. Revenues of $3.05 billion surpassed the Zacks Consensus Estimate by 4.9%.
Intuitive Surgical has a long-term estimated growth rate of 15.5%. ISRG’s earnings surpassed estimates in each of the trailing four quarters, the average surprise being 15.1%.
West Pharmaceutical, currently carrying a Zacks Rank #2, reported a third-quarter 2026 adjusted EPS of $2.66, which surpassed the Zacks Consensus Estimate by 22%. Revenues of $874.5 million beat the Zacks Consensus Estimate by 5.9%.
WST has an estimated long-term earnings growth rate of 17.4%. The company’s earnings beat estimates in each of the trailing four quarters, the average surprise being 18.6%.
Discover the Stocks Our Experts Want to Own This Quarter
Each quarter, four Zacks editors compile their favorite stocks into one report. As a sign of the times, three of this quarter's picks can potentially cash in on the massive AI boom. One grew its commercial revenue more than 140% last quarter.
The fourth stock is an online retailer posting its most significant growth since the pandemic. Its shares jumped more than 25% after its last earnings report, then pulled back, giving investors a chance to capitalize on what could be a longer-term bullish trend.
Get Your Free Ultimate Four Report >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
OPKO Health, Inc. (OPK): Free Stock Analysis Report
Intuitive Surgical, Inc. (ISRG): Free Stock Analysis Report
West Pharmaceutical Services, Inc. (WST): Free Stock Analysis Report
Glaukos Corporation (GKOS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).