

Valued at a market cap of $56.4 billion, Baker Hughes Company (BKR) is a global energy technology company that provides equipment, services, and digital solutions across the oil and gas and broader industrial sectors. Headquartered in Houston, it operates through two primary segments: Oilfield Services & Equipment (OFSE) and Industrial & Energy Technology (IET), in more than 120 countries
Companies worth between $10 billion and $200 billion are typically classified as “large-cap stocks,” and BKR fits the label perfectly, with its market cap exceeding this threshold, underscoring its size, influence, and dominance within the oil & gas equipment & services industry. The company is also expanding beyond traditional oilfield services through technologies such as AI-driven automation, digital oilfield solutions, LNG infrastructure, geothermal, and carbon capture.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
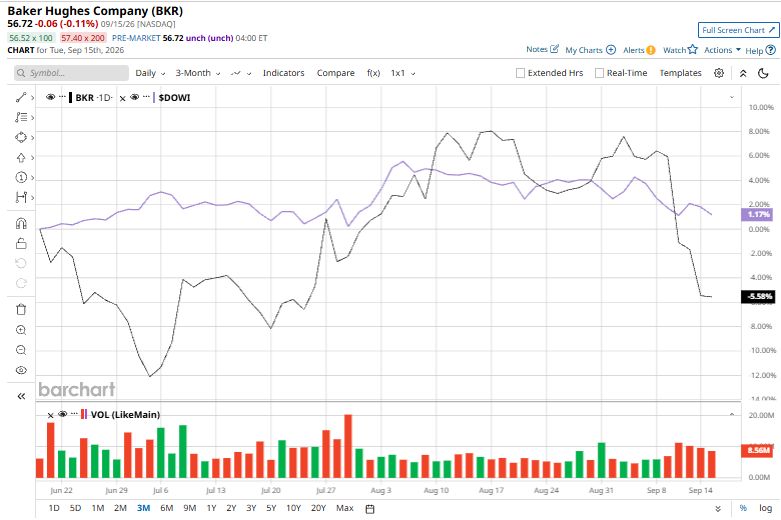
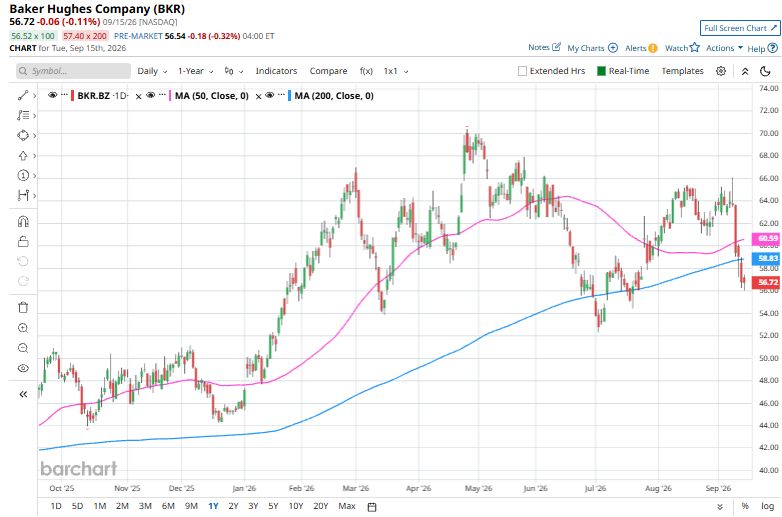
However, Baker Hughes may have lost some momentum lately. The energy giant is currently trading 19.4% below its 52-week high of $70.41, reached on Apr. 27. Over the past three months, it has declined 9.2%, trailing the Dow Jones Industrial Average’s ($DOWI) marginal uptick during the same time frame.
 www.barchart.com
The recent pullback, however, contrasts sharply with BKR’s longer-term gains. The stock is up 24.6% year to date, nearly tripling the Dow’s 8.4% advance. Over the past 52 weeks, BKR has climbed 22.6%, comfortably ahead of the index’s 13.5% gain.
Still, the stock’s technical picture has recently turned less favorable. BKR has recently fallen below both its 50-day and 200-day moving averages, suggesting the stock’s recent momentum may be losing steam.
 www.barchart.com
BKR’s strong performance over the past year has been fueled by robust demand for energy infrastructure and technology, with particular strength across LNG, gas infrastructure, and oilfield services. At the same time, Baker Hughes has been pushing deeper into higher-value digital, AI, and automation technologies, giving investors another reason to look beyond its traditional oilfield-services business.
That growth story has been reinforced by a string of major contracts. On Sept. 4, Baker Hughes secured a significant offshore stimulation services contract from BP p.l.c. (BP) to support new wells and boost recovery from mature fields across the UK North Sea. The company will deploy its vessel-based StimFORCE™ technology to improve production, reduce downtime, and give bp greater operational flexibility. The award strengthens Baker Hughes’ long-standing presence in the UK’s offshore energy market.
The company is also deepening its footprint in the Middle East. Last month, Baker Hughes secured a multi-year contract with Kuwait Oil Company to accelerate technology innovation across Kuwait’s upstream energy sector. As part of the deal, Baker Hughes will establish a research and technology development center at KOC’s Ahmadi Innovation Valley, focusing on digital, AI, and automation solutions to improve production, reduce costs, and boost recovery. The partnership further strengthens Baker Hughes’ 40-plus-year presence in Kuwait.
But the momentum has hit a near-term bump. On Sept. 10, Baker Hughes shares fell 6.5% after CEO Lorenzo Simonelli warned that integration costs and lower margins from its Chart Industries acquisition could weigh on near-term profitability and cash flow. The company subsequently lowered its 2026 free cash flow conversion target to 40%–45%, prompting investor concerns about margin pressure during the integration period.
Baker Hughes has delivered a solid run, but it still trails oilfield-services heavyweight, SLB N.V. (SLB), whose shares have gained 55.9% over the past 52 weeks and 41.2% in 2026.
Still, Wall Street sees further room for BKR to climb. The stock has a consensus rating of "Moderate Buy” from the 21 analysts covering it, and the mean price target of $73.180 suggests a 29% premium to its current price levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Maybe You Should Skip That Parlay: New Data Says Sports Betters Have 41% Less Money in Their Bank Accounts Washington’s AI Safety Push Meets Anthropic CEO Amodei’s Call to Slow AI Development. What That Means for Nvidia and Chip Stocks. The Case for Selling CrowdStrike Stock Seagate Stock Has Already Exploded. Here’s What Could Send It 99% Higher to $1,600.