

Domino's Pizza (DPZ) stock keeps falling. DPZ is at least 30% too cheap, based on its strong free cash flow (FCF) and high FCF margins. Two attractive plays are to sell short out-of-the-money (OTM) put options with near-term expiration dates, as well as buy long-dated in-the-money (ITM) calls.
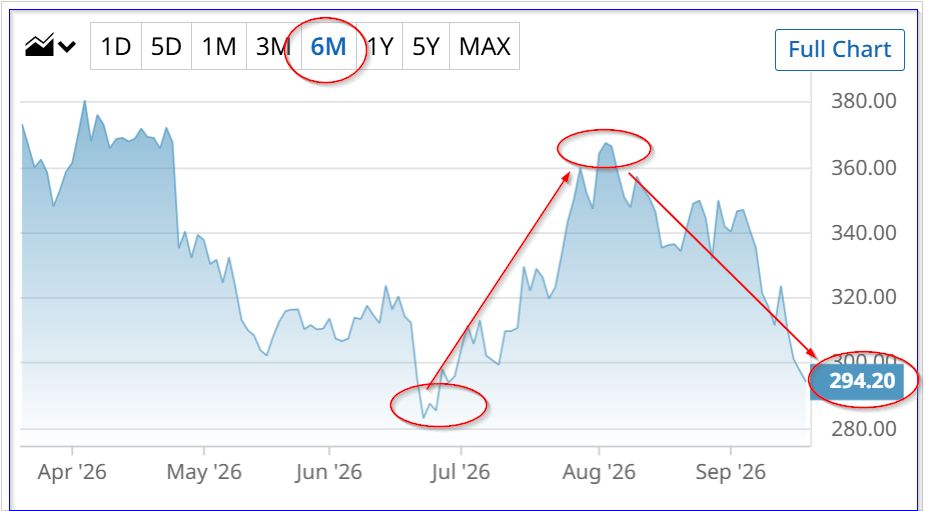
DPZ dropped to $294.20 on Friday, Sept. 18, near its 6-month low price of $283.03 on June 23. This was about a month before its July 23 Q2 earnings release.
Can’t Get Enough Options?: Join the list for Barchart’s daily unusual options report, delivered free.
 DPZ stock - last 6 months - Barchart - Sept. 18, 2026
Why is DPZ So Cheap?
After that, DPZ floated higher. Maybe that same pattern will return, as Q3 earnings are due out on Oct. 13.
Moreover, the stock is well below both analysts' price targets. In addition, DPZ is well below historical forward price/earnings (P/E) metrics. More on that below.
However, one reason why it is weak may be that analysts have slightly lowered their revenue projections. For example, 2026 revenue forecasts are now $5.18 billion, down from $5.2 billion as reported in my July 21 Barchart article ("Domino's Pizza Delivers Strong FCF and FCF Margins - Is DPZ Stock Too Cheap?")
In addition, analysts are forecasting $5.30 billion for 2027, down from $5.37 billion in prior average forecast surveys. Some are concerned Domino's faces weak demand, increasing competition, and is closing stores faster than expected.
Nevertheless, its FCF is still strong. Last quarter it generated a 14% FCF margin, and its trailing 12-month (TTM) margin was 13% of sales.
What is DPZ Worth?
That implies that over the next 12 months (NTM), its average $5.24 billion in sales could generate 4681 million in FCF.
So, using a 5% FCF yield metric, its market value should be $13.6 billion ($5.24b/0.05), compared to its existing $9.733 billion market cap. That implies a price target (PT) 40% higher, or $411.88 per share.
Other analysts also see significantly higher PTs: $381.11 (Yahoo! Finance), $383.21 (Barchart), and $411.93 (AnaChart).
Moreover, a third valuation metric is its forward P/E ratio. Over the last 5 years, DPZ has had an average forward P/E of 24.46x according to Morningstar, and 26.76x (Seeking Alpha).
So, using a rough average multiple of 25x and applying analysts' 2026 EPS forecast of $19.04, DPZ's value is $476 per share. Even at a 25% discount to the average forward P/E, the PT is $357.00, or 21% higher.
The bottom line is that DPZ is worth between $357 and $412, with an outlier of $476, with upside of between 21% and 40%, or 30% on average. Moreover, its upcoming Q3 earnings may be a good catalyst.
Shorting OTM Puts and Buying ITM Calls
Two ways to play this are to sell short near-term out-of-the-money (OTM) puts, as well as to buy longer-expiry in-the-money (ITM) calls. Here's an example of how this works.
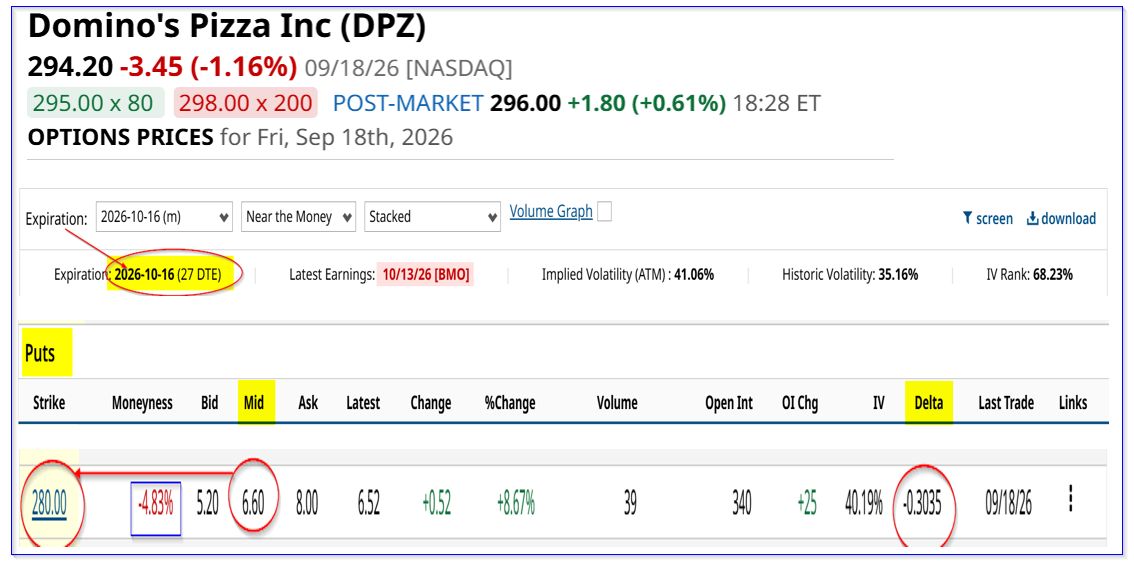
The Oct. 16, 2026, expiry option chain, a little less than a month away, shows that the $280.00 put strike price has a midpoint premium of $6.60. That represents an expected yield to expiry of 2.357% (i.e., $6.60/$280.00), for a strike price that's a little less than 5% lower (i.e., 4.83% out-of-the-money or OTM).
 DPZ puts expiring Oct. 16 - Barchart - As of Sept. 18, 2026
Moreover, the investor can repeat this play each month and keep collecting income, although it may vary. That could help finance a long purchase of in-the-money (ITM) calls.
For example, if this short-put play could be repeated each month for 6 months, the investor may be able to accumulate $39.60 (i.e., $6.60 x 6), without getting assigned to buy DPZ shares.
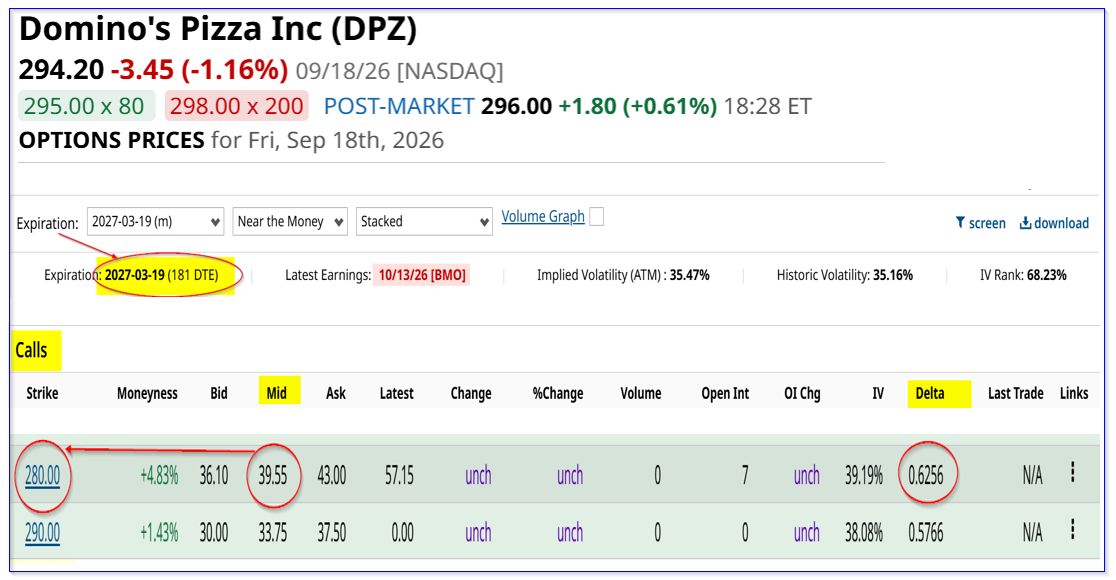
That could finance the upfront purchase of a 6-month call option. For example, the March 19, 2027, expiry period shows that the same $280.00 strike price, but as a call option, costs $39.55 today.
 DPX calls expiring March 19 - Barchart - Sept. 18, 2026
This essentially means that, although the investor has to pay $3,955 upfront today for 1 call option at $280.00 expiring March 19, the investor can finance this by collecting $660 each month (no guarantee) by shorting one-month out-of-the-money (OTM) puts at the same strike price or higher (i.e., $660 x 6 = $3,960).
So, after owning the call option for free, any upside in DPZ stock will go straight to the bottom line. For example, at $357 in 6 months, the call option would have an intrinsic value of $77 ($357-$280) x 100 = $7,770.
That would be a huge return for the investor, depending on how much of the call option was paid for by monthly OTM short-put plays.
The bottom line is that DPZ is dirt cheap, at least 30% undervalued. Two ways to play it are shorting OTM puts and buying ITM calls.
On the date of publication, Mark R. Hake, CFA did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Domino's Pizza Stock Is Dirt Cheap, With 30% Potential Upside - What's the Best Play? IonQ's Options Are the Cheapest They've Been All Year. Here's the Trade That Takes Advantage. Warby Parker’s Unusual Options Activity Points to a Covered Call Bet: Bullish on Growth, Cautious on Valuation Alphabet Stock Stays Flat - Ideal for GOOGL Short Put and Put Credit Spread Plays