

As tech giants have continued to pour billions of dollars into the current artificial intelligence (AI) landscape, skepticism has grown over when those massive investments will start paying dividends — or whether there will be any dividends at all. Today, however, the market narrative is shifting as companies start demonstrating viable revenue streams from AI. Meta Platforms (META) is one such company that has unveiled plans for AI-related revenue.
Meta Platforms is a global tech and social media powerhouse operating platforms such as Facebook, Instagram, WhatsApp, Threads, and more under its “Family of Apps.” Headquartered in Menlo Park, California, Meta has also started to aggressively pivot toward the use of artificial intelligence, custom silicon, and consumer AI products like Muse and Meta AI. Let's take a closer look.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Meta Stock Bounces Back
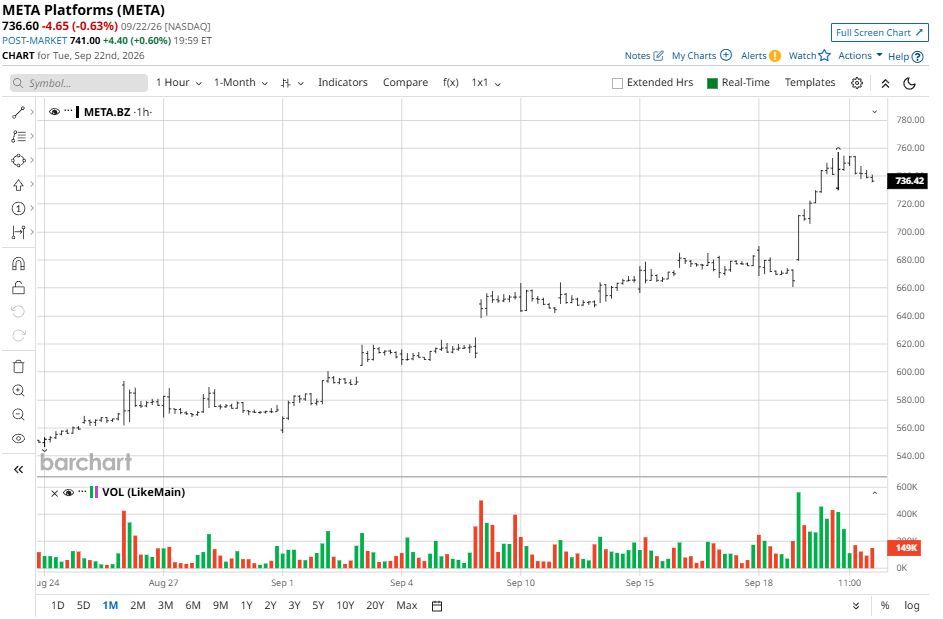
META stock has staged a dramatic comeback after experiencing some turbulence in the market in 2026. On Sept. 21, the stock shot higher by more than 11%, then set a new 52-week high of $779.82 on Sept. 24 after months of underperformance.
Shares of META were falling on a year-to-date (YTD) basis earlier this year, weighed down by soaring AI investments and disappointing second-quarter figures. However, the launch of Muse AI has helped ignite a powerful rally in the stock, with shares now up 14% YTD.
By comparison, the S&P 500 Communications Services Sector ($SRTS) — which includes major telecom and media names — has posted modest gains for much of the year. Meta’s recent spike and AI-driven rally have helped the stock outperform even its own sector, underscoring investment sentiment.
 www.barchart.com
Meta Reports Q2 Results
Meta Platforms reported its second-quarter 2026 results on July 29. The company showed revenue of $60.8 billion, up 28% year-over-year (YOY) and edging past the $60.2 billion analyst consensus estimate. However, diluted EPS came in at $6.18, missing the $7.22 estimate by more than 14% and snapping a streak of earnings beats as surging AI-related costs overwhelmed strong top-line growth.
Total costs and expenses surged 55% YOY to $42.03 billion, including $2.4 billion in legal charges and $1.18 billion in severance tied to an 8,000-employee headcount reduction, compressing Meta's GAAP operating margin to 31% from 43% a year earlier. Advertising revenue climbed 27% YOY to $59.36 billion, with ad impressions up 14% and average price per ad up 12%. Meanwhile, free cash flow plunged 91% YOY to just $784 million as capital expenditures hit $31.1 billion for the quarter.
Management guided Q3 revenue to $61 billion to $64 billion, while Wall Street estimates revenue of about $63 billion for the quarter. The company also narrowed its full-year 2026 capex guidance to $130 billion to $145 billion. CEO Mark Zuckerberg said that AI is "accelerating our core business today […] and opening the door to entirely new enterprise opportunities," while executives highlighted early traction from Meta's new enterprise AI cloud offering and the viral consumer adoption of Muse as key emerging monetization pathways.
Meta Gears up AI Monetization
Shares of Meta Platforms spiked more than 11% on Monday following investor enthusiasm surrounding the company’s AI monetization strategy. The rally outpaced the broader tech space even as the S&P 500 Communications Services Sector popped nearly 4%, the Invesco QQQ Trust (QQQ) gained close to 3%, and rival firms like Alphabet (GOOGL), Reddit (RDDT), Netflix (NFLX), and Pinterest (PINS) made similar small gains.
Meta’s recent spike continued its rally from early September, when it jumped following the initial Muse AI rollout and its acquisition of Swedish startup Stilla.ai.
Analysts have increasingly linked these catalysts to Meta's potential to unlock revenue streams beyond traditional digital advertising, including subscriptions, transactions, and business messaging monetization across WhatsApp, Messenger, and Instagram. That's reinforcing growing confidence that Meta's massive AI investments are beginning to translate into tangible, diversified growth.
Should You Buy META Stock?
Meta Platforms' explosive rally around Muse and broader AI monetization prospects has reignited investor confidence that the company's massive AI investments are finally translating into diversified revenue streams beyond advertising.
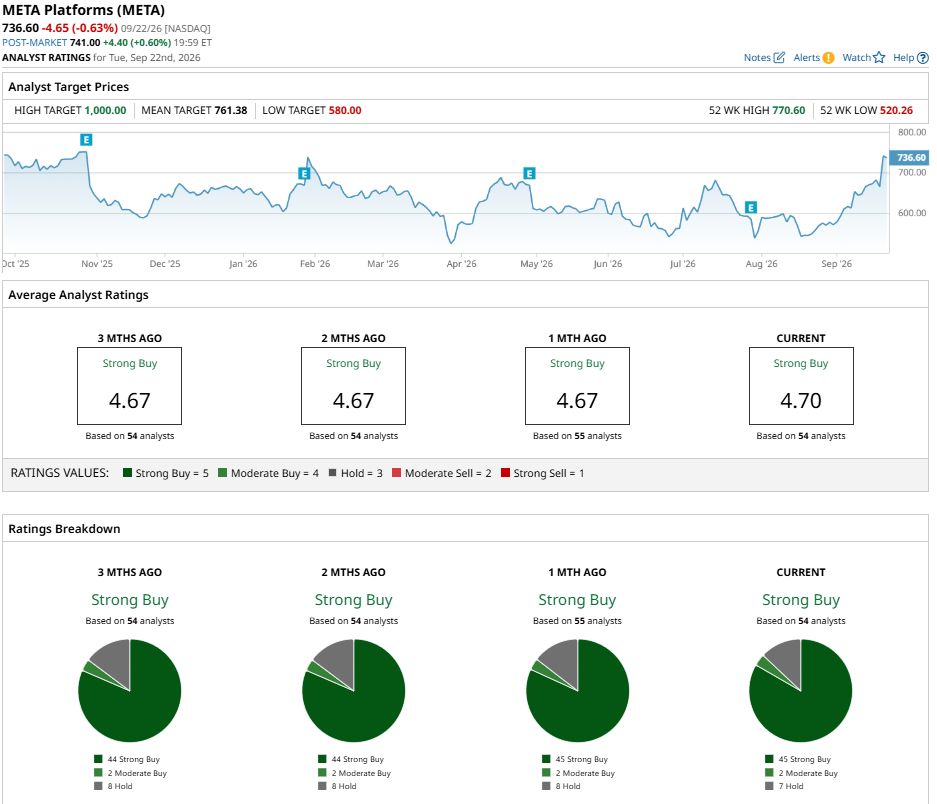
Wall Street remains overwhelmingly bullish. Overall, META stock holds a consensus "Strong Buy" rating from 54 analysts with coverage. Out of those analysts, 45 have a "Strong Buy" rating, two have a “Moderate Buy" rating, and seven have a "Hold" rating. The average price target of $786.74 implies modest potential upside of about 4% from current levels, suggesting the recent surge has largely caught up to analyst expectations even as long-term AI-monetization optimism remains strong.
 www.barchart.com
On the date of publication, Ruchi Gupta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.