

Truist Financial Corporation (TFC), headquartered in Charlotte, North Carolina, is a leading financial services provider specializing in banking and trust services. Valued at $56.7 billion by market cap, the company provides a diverse array of services, encompassing retail, small business, and commercial banking, asset management, capital markets, commercial real estate, corporate and institutional banking, insurance, mortgage, payments, and specialized lending and wealth management solutions. The leading commercial bank is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Friday, Oct. 16.
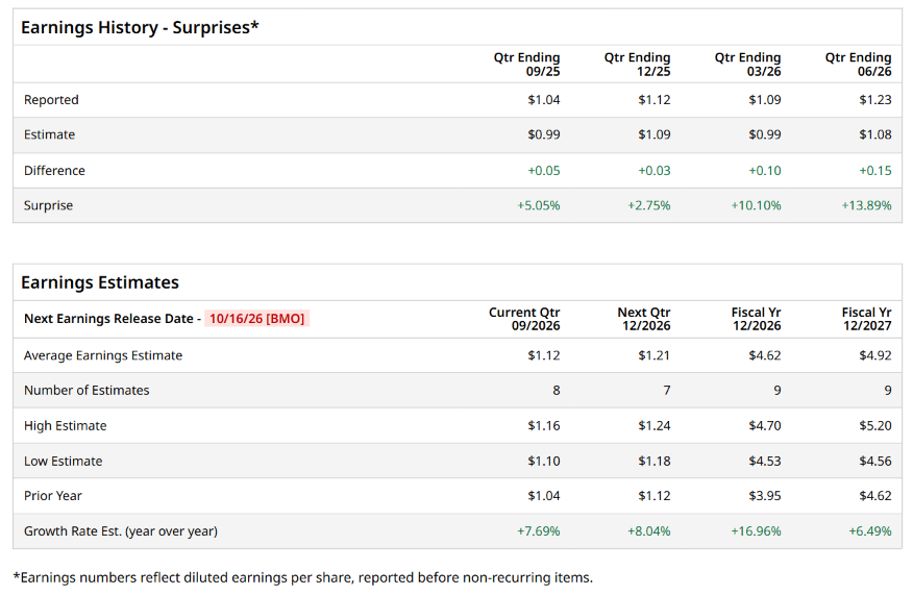
Ahead of the event, analysts expect Truist Financial to report a profit of $1.12 per share on a diluted basis, up 7.7% from $1.04 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect Truist Financial to report EPS of $4.62, up 17% from $3.95 in fiscal 2025. Its EPS is expected to rise 6.5% year over year to $4.92 in fiscal 2027.
 www.barchart.com
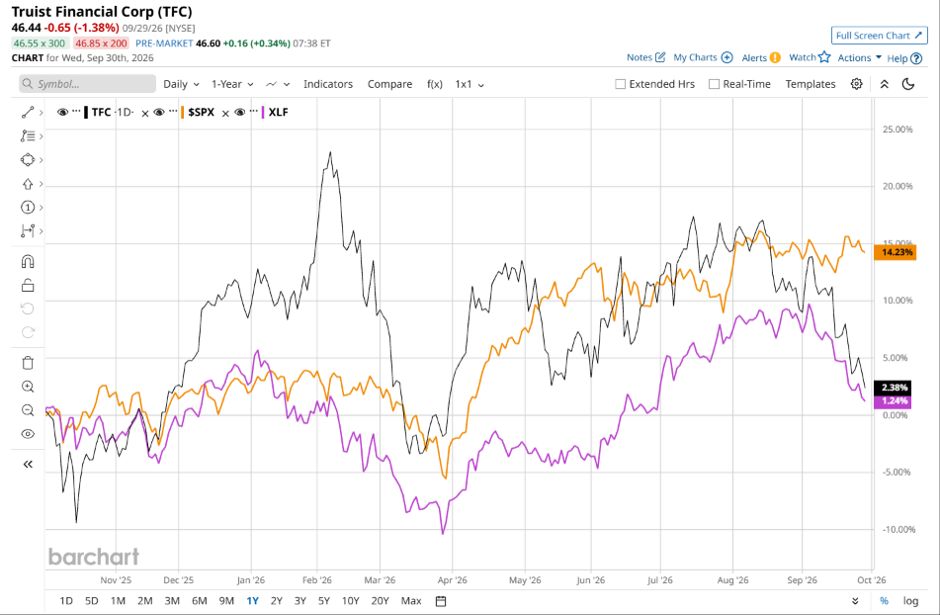
TFC stock has underperformed the S&P 500 Index’s ($SPX) 15.2% gains over the past 52 weeks, with shares up 1.9% during this period. However, it outpaced the State Street Financial Select Sector SPDR ETF’s (XLF) marginal losses over the same time frame.
 www.barchart.com
TFC posted a mixed performance as strong operational turnaround momentum was counterbalanced by portfolio reshuffling and persistent margin headwinds. On the positive side, Truist generated solid earnings growth, delivering improved net profit margins near 30% and consecutive quarterly earnings beats in 2026 driven by disciplined expense control and positive operating leverage. However, the stock’s total upside remained constrained compared to broader market averages and top regional banking peers. Top-line growth was weighed down by strategic exits from non-core, lower-yielding consumer lending businesses, such as prime auto and marine loans, which reduced annual loan production by billions. Additionally, modest compression in net interest margins, near-term yield pressure from hedging swaps, and broader economic uncertainty over loan demand and deposit mix continued to cap investor enthusiasm.
Analysts’ consensus opinion on TFC stock is cautious, with a “Hold” rating overall. Out of 21 analysts covering the stock, four advise a “Strong Buy” rating, one suggests a “Moderate Buy,” 13 give a “Hold,” one recommends a “Moderate Sell,” and two advocate a “Strong Sell.” TFC’s average analyst price target is $54.37, indicating a potential upside of 17.1% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Anthropic Just Made a CRISPR-Like Discovery. What It Actually Means for CRSP Stock Investors. If You Love Speculating, You Should Keep a Close Eye on Novo Nordisk Stock Google's AI Chips Are Set to Be Sent to Space. What This Means for GOOGL Stock. What You Need to Know Ahead of EQT’s Earnings Release