

Wall Street just handed Netflix (NFLX) another potential lifeline. Veteran bank Deutsche Bank recently turned bullish on the streaming giant, upgrading Netflix stock to a “Buy” rating from a “Hold” and setting a $95 price target, down from $100. The firm also lowered its operating income and free cash flow estimates after the company’s second-quarter results.
The new price target represents about 40% potential upside from Netflix’s latest closing price, putting the upgrade in focus after a difficult year for NFLX stock. Let's take a closer look.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Deutsche Bank Sees an Opportunity Wall Street May Be Missing
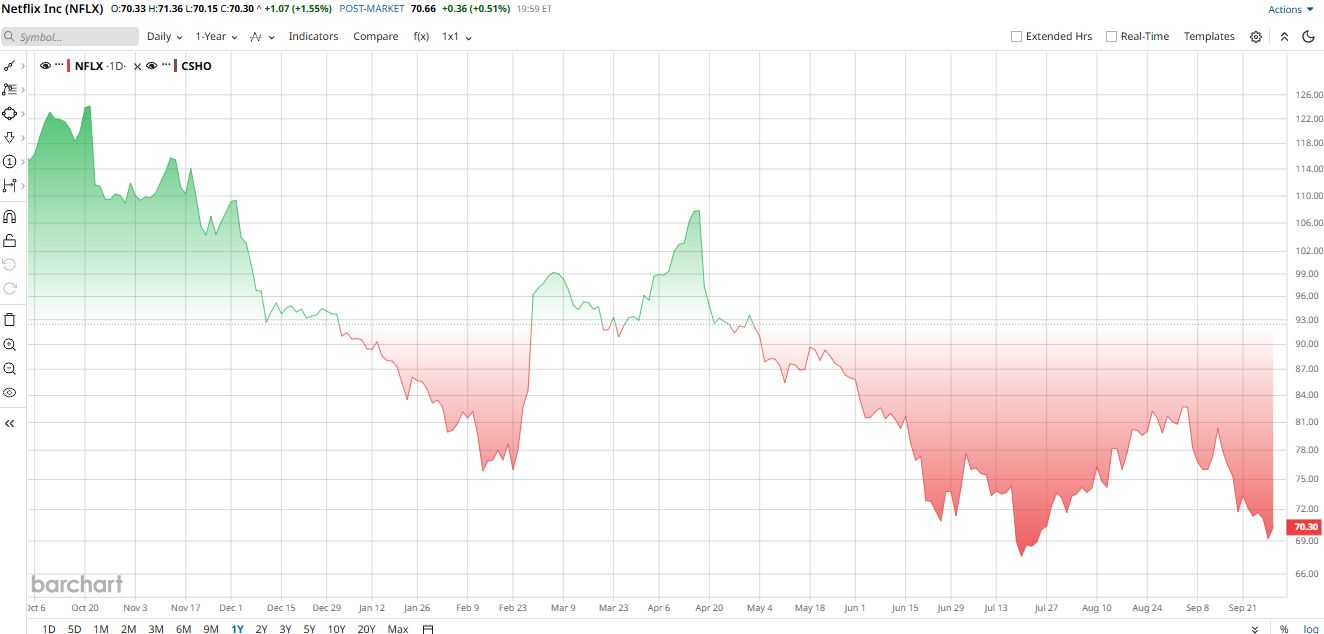
Netflix shares are down about 28% year-to-date (YTD) in 2026. This comes as investors have shown concern over softer U.S. engagement, slower subscriber growth, and the fallout from a failed Warner Bros. Discovery (WBD) deal.
The selloff has changed the conversation around NFLX stock. Rather than paying a premium for uninterrupted streaming growth, investors are now questioning whether Netflix can create its next leg of expansion.
That is where Deutsche Bank’s upgrade is important. The firm argues that Wall Street may be concentrating too heavily on U.S. viewing time while overlooking the company’s international opportunity. International engagement has increased year-over-year (YOY) in each of the past four six-month periods, according to analyst Bryan Kraft.
Kraft believes Netflix’s global scale, brand, and production expertise could support a broader “Netflix As A Platform” opportunity over time.
 www.barchart.com
What the ‘Buy’ Upgrade Means for NFLX Stock
Deutsche Bank’s call suggests the current share price may already reflect many of the concerns weighing on sentiment.
NFLX stock trades at about 18 times Kraft's 2027 earnings forecast. That's an improvement from the 40 times forward earnings it traded at in June 2025. The lower multiple provides analysts with ample room, Kraft says, if the company's international growth is healthy.
Another aspect of the bull case is artificial intelligence (AI). For Kraft, the true power of AI is in its capacity to assist in creating content, personalizing it, and delivering advertising. AI could help Netflix become more efficient and promote even more means of generating revenue for its huge international audience. Still, investors are not removing the risks.
Netflix Delivers Strong Revenue Growth, But Cash Flow Slips
Netflix's revenue continued to grow at a solid pace in the second quarter of 2026, while the streaming giant's cash generation turned negative. Revenue was $12.56 billion in Q2, an increase of 13% YOY. Adjusted EPS came in at $0.80, while net income increased 9% to $3.4 billion. The results indicate that Netflix is continuing to add to its bottom and top lines as the company expands its presence with its global subscriber base and advertising business.
Growth was widespread across regions. The top earner was the U.S. and Canada with $5.43 billion in revenue, followed by Europe, the Middle East and Africa (EMEA) with $4.03 billion. Latin America accounted for $1.58 billion in revenue while Asia Pacific (APAC) saw revenue of $1.51 billion.
That said, free cash flow is an important consideration. Netflix reported $1.52 billion for the quarter, compared to $2.3 billion last year. The company had cash and equivalents of $9.1 billion at the end of the period.
Looking forward, management predicted a 12% YOY rise in Q3 revenue to $12.86 billion. Netflix also trimmed its full-year 2026 revenue guidance to a range of $51 billion to $51.4 billion, while holding its planned 31.5% operating margin unchanged. The current Wall Street consensus is for full-year earnings of $3.59 per share in fiscal 2026.
Wall Street Is Split on Netflix Stock
In addition to Deutsche Bank, Morgan Stanley kept an “Overweight” rating on NFLX stock in July but lowered its target to $83 from $90. Similarly, BMO Capital Markets recently maintained a “Buy” rating with a $135 target, while Bernstein kept its “Buy” rating with a price target of $95 per share.
Wells Fargo recently took the opposite view on NFLX stock, downgrading Netflix to an “Underweight” rating from “Equal Weight” and cutting its price target to $57. The firm cited concerns over engagement trends.
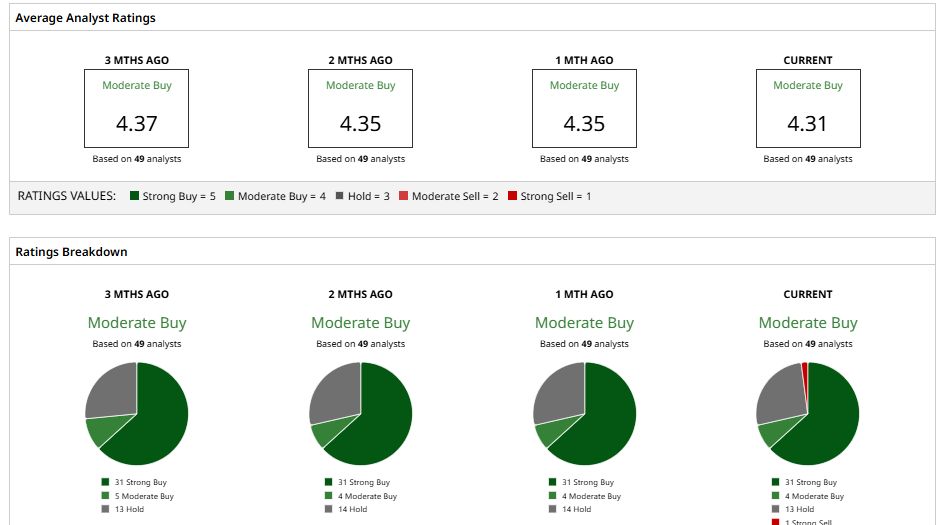
Overall, Netflix has a consensus “Moderate Buy” rating on Wall Street. The average price target of $94.36 suggests the stock could climb as much as 39% from current levels.
The next major test comes with Netflix’s Oct. 20 earnings report. With the quarterly release, investors will get another read on international engagement, advertising growth, and the company’s broader growth trajectory.
 www.barchart.com
On the date of publication, Nauman Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Netflix Stock Just Got a Stunning Upgrade After a Brutal 2026 Selloff Dividend Stocks Are Not a Lost Cause Even as Treasury Yields Rise Over 5% Robinhood’s New AI Agents Are Helping Turn Everyday Investors Into Mini Quant Fund Operators United Therapeutics Just Sent Liquidia Stock Lower After Patent Battle