

Tesla, Inc. (TSLA), headquartered in Austin, Texas, is a company specializing in electric vehicles (EVs), energy storage, and clean energy solutions. Valued at $1.5 trillion by market cap, the company designs, manufactures, and sells a range of innovative products including luxury EVs like the Model S, Model X, and Model Y, as well as clean energy solutions like solar panels, solar roofs, and energy storage systems. The EV giant is expected to announce its fiscal third-quarter earnings for 2026 after the market closes on Wednesday, Oct. 21.
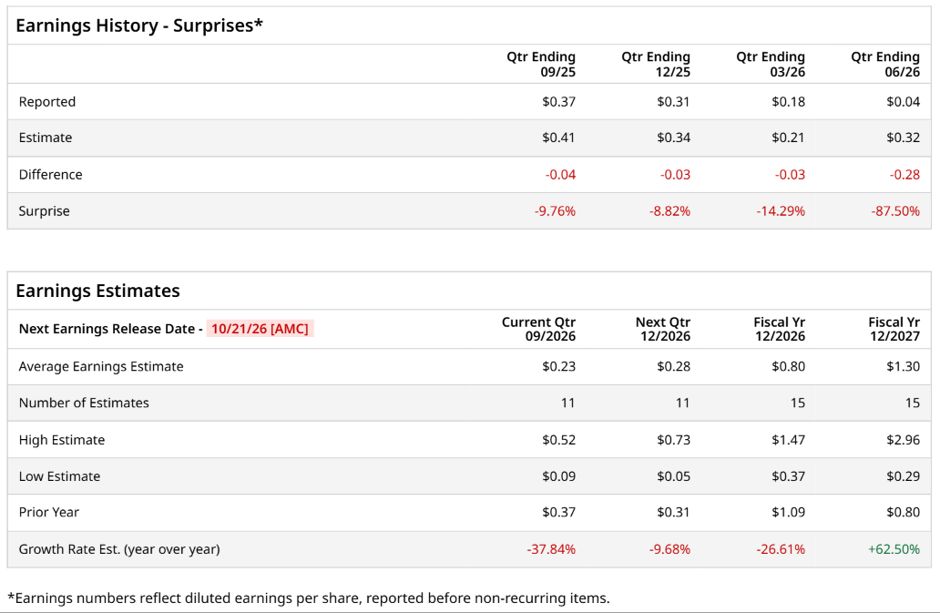
Ahead of the event, analysts expect Tesla to report a profit of $0.23 per share on a diluted basis, down 37.8% from $0.37 per share in the year-ago quarter. The company missed the consensus estimates in each of the last four quarters.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For the full year, analysts expect Tesla to report EPS of $0.80, up 26.6% from $1.09 in fiscal 2025. However, its EPS is expected to rise 62.5% year over year to $1.30 in fiscal 2027.
 www.barchart.com
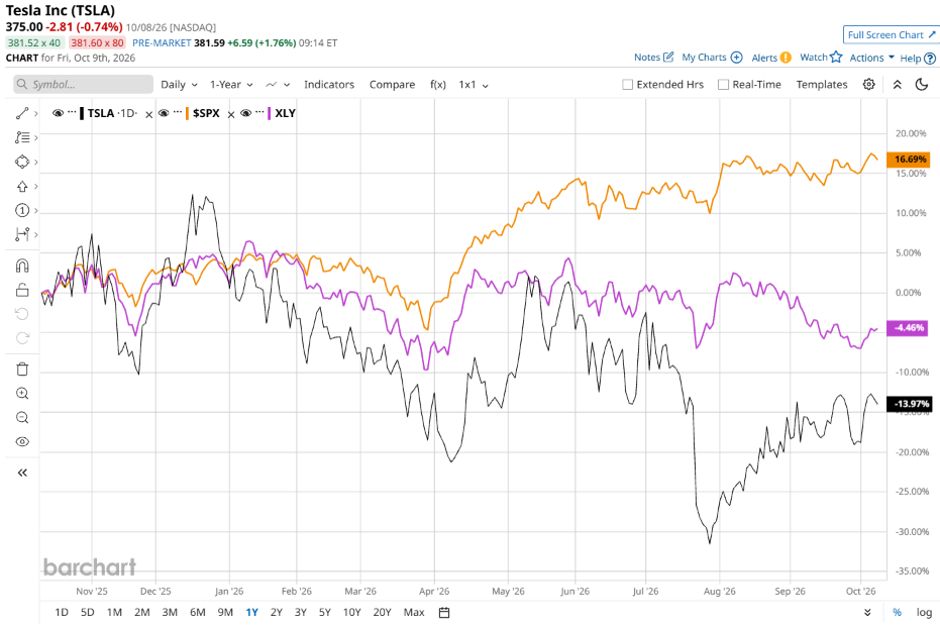
TSLA stock has underperformed the S&P 500 Index’s ($SPX) 15% gains over the past 52 weeks, with shares down 11% during this period. Similarly, it underperformed the State Street Consumer Discretionary Select Sector SPDR ETF’s (XLY) 4.7% losses over the same time frame.
 www.barchart.com
Despite near-term growth and margin pressures, higher geopolitical tensions and elevated gasoline prices have positioned electric vehicles as an appealing cost-effective alternative, helping Tesla’s quarterly deliveries exceed production and ease immediate demand fears. However, persistent demand softness across major markets, previously flagged by analysts like The Goldman Sachs Group, Inc. (GS) could force further pricing cuts and pressure automotive margins. Trading at an exceptionally high forward P/E multiple, Tesla’s valuation already factors in significant long-term growth across AI, autonomous driving, Robotaxis, and robotics, making its near-term risk-reward less compelling as capital expenditures rise and market competition intensifies.
Analysts’ consensus opinion on TSLA stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 41 analysts covering the stock, 16 advise a “Strong Buy” rating, two suggest a “Moderate Buy,” 19 give a “Hold,” and four recommend a “Strong Sell.” TSLA’s average analyst price target is $406.38, indicating a potential upside of 8.4% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
‘Don’t Spend It. Save It. Invest It. Let It Compound’: Kevin O’Leary’s Millionaire Rule Needs $850 a Month, and the Worst 40 Years on Record Still Produced $4.1 Million Trump's Former AI Czar David Sacks Slams A New York Bill That Will Cost Families '$664 More Per Year' According to a Group Amazon Gave $5 Million Big Tech Needs Power. Constellation Just Found a $1 Billion Buyer in Google. Uber’s ezCater Acquisition Looks Like a Smart Move to Diversify Revenue Streams