

Valued at a market cap of $32.7 billion, The Hershey Company (HSY) is a leading confectionery manufacturer that produces and sells chocolate, candy, salty snacks, and pantry products across the United States and international markets. Headquartered in Hershey, Pennsylvania, the company operates through three segments: North America Confectionery, North America Salty Snacks, and International. Its portfolio includes well-known brands such as Hershey’s, Reese’s, Kisses, Jolly Rancher, and SkinnyPop.
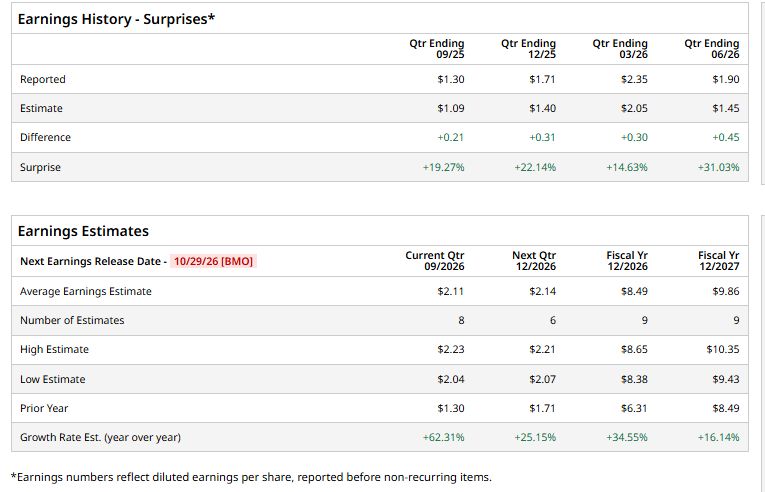
The chocolate maker is expected to report its Q3 2026 earnings before the market opens on Thursday, Oct. 29. Ahead of the event, analysts expect the company’s EPS to be $2.11 on a diluted basis, up 62.3% from $1.30 in the year-ago quarter. Hershey has also topped Wall Street’s EPS estimates in each of the past four quarters, building a solid track record ahead of its next report.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
For fiscal 2026, analysts project the company’s EPS to be $8.49, up 34.6% from $6.31 in fiscal 2025. Moreover, its EPS is expected to rise 16.1% year over year to $9.86 in fiscal 2027.
 www.barchart.com
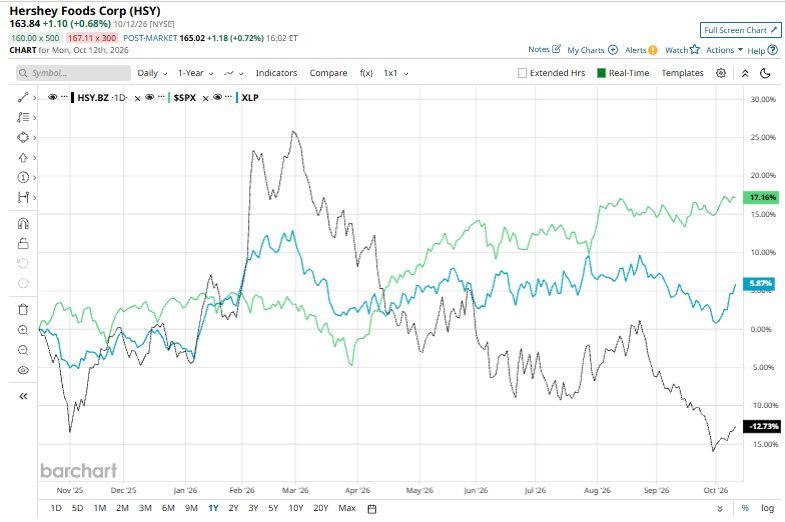
HSY stock has plunged 14.7% over the past 52 weeks, underperforming the S&P 500 Index’s ($SPX) 19.2% rise and the State Street Consumer Staples Select Sector SPDR ETF’s (XLP) 8.1% rise during the same time frame.
 www.barchart.com
The Hershey Company has lagged the broader market over the past year primarily because of soaring cocoa costs, margin pressure, and higher product prices that have weighed on consumer demand. Elevated raw-material expenses and tariffs have squeezed profitability, while price increases have contributed to lower sales volumes. Although Hershey has worked to offset these pressures through pricing actions and cost-saving initiatives, investors have remained cautious about the pace of its earnings recovery.
Analysts are somewhat bullish on HSY, with the stock having a “Moderate Buy” rating overall. Among the 22 analysts covering the stock, six recommend a “Strong Buy,” 15 suggest a “Hold,” and one suggests a “Strong Sell.” HYS’ average analyst price target is $198.90, indicating an upside of 21.4% from the current level.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Why It’s Time to Load Up on Marvell Stock Dear TSMC Stock Fans, Circle Oct. 15 on Your Calendar Dear Accenture Stock Fans, Mark Your Calendars for Oct. 14 Nasdaq Futures Slip as Chip Stocks Extend Slide; Big Bank Earnings on Tap