

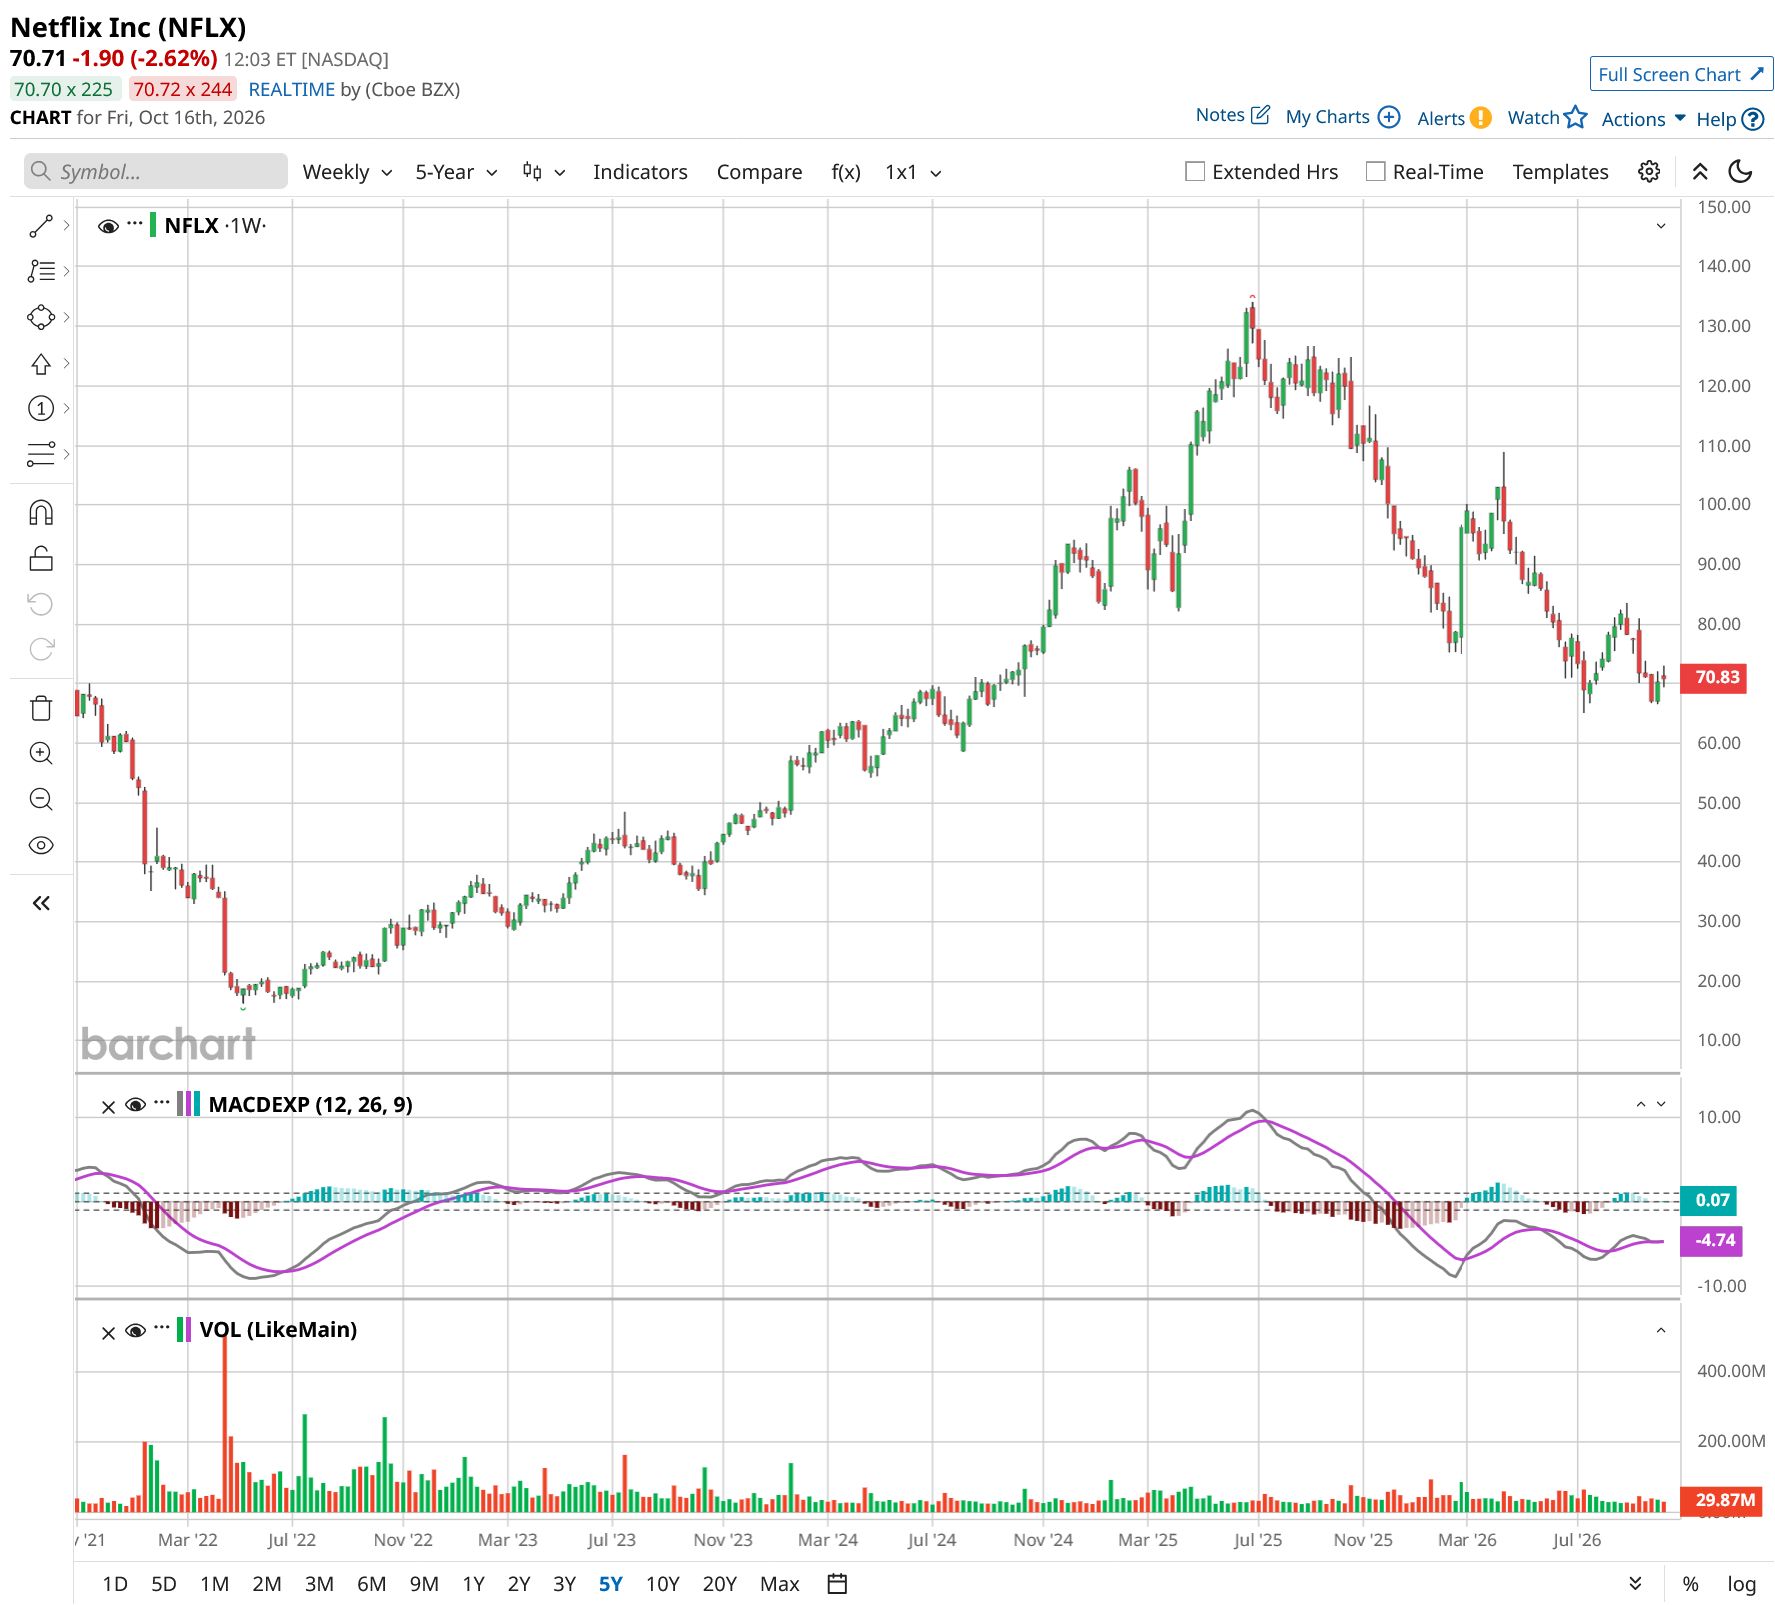
Valued at a market cap of over $300 billion, Netflix (NFLX) is one of the world's largest media companies. Over the last decade, NFLX stock has returned more than 480% to shareholders. However, it is down 46% from its all-time high in October 2026.
Wall Street has asked the same question about Netflix for years. Can a company this big keep growing at a healthy pace?
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
A new analyst call offers a confident answer, which rests on something viewers can rarely measure. I dug into the note and the company's latest earnings interview. Here is what stood out.
 www.barchart.com
The Streamer Still Has a Long Runway
Despite its massive size, Netflix continues to grow at an enviable pace. During its Q2 earnings call, CFO Spencer Neumann said management expects 13% to 14% revenue growth this year.
Wall Street forecasts sales to rise from $45.2 billion in 2025 to $51.22 billion in 2026 and to $74.60 billion in 2030.
Neumann explained that Netflix has less than 45% penetration across about 800 million addressable households. It captures just 7% of a roughly $670 billion revenue pool, and it accounts for just 5% of global TV viewing.
Greg Peters, one of Netflix's two CEOs, said view hours grew 2% in the first half, which added 1.5 billion hours. However, not all hours are equal. For instance, live events will account for 5% of the content budget but only 1% of view hours.
Yet six of the top ten sign-up days in five years came from live events.
Jefferies Sets an $85 NFLX Stock Price Target
According to a report from Investing.com, Jefferies initiated coverage on NFLX stock with a “Buy” rating and an $85 price target. NFLX currently trades at about $71, indicating an upside of more than 20%.
Analyst John Colantuoni said his team sees three forces working together for the streaming giant: better monetization, margin gains from scale, and share buybacks. Jefferies says these factors should deliver more than 14% earnings-per-share growth over the next ten years.
Wall Street estimates earnings to grow from $2.53 per share in 2025 to $6.19 per share in 2030, which indicates a compounded annual growth rate of 19.6%.
Neumann said Netflix repurchased $4.7 billion of shares in Q2, its largest quarter ever. About $27 billion of buyback capacity remains unrealized, which could reduce the share count by almost 10% at current prices.
Why Jefferies is Bullish on Netflix Stock
Jefferies expects revenue per member to grow 6% a year on average over the next three years. The outlook covers more than half of the 11% annual revenue growth it projects from 2026 to 2029.
In the U.S., Jefferies says the standard plan costs 60% less per viewing hour than other paid platforms. It expects that gap to shrink to 50% by 2029 as prices rise about 7% a year.
In short, Netflix plans to charge more while still looking cheaper.
Peters made a similar point on the call. He said some rivals would cost twice as much per hour. He also said the first half-price changes in the U.S., Mexico, and Spain went as expected.
Ads are the second lever. Jefferies projects advertising revenue will grow 35% a year. It points to membership growth, heavier ad load, demand from third-party ad platforms, and new ad formats.
Peters said the gap between ad tier revenue per member and the standard plan is narrowing. He called that gap near-term underrealized revenue.
Live sports feed both levers. Netflix just won exclusive rights to the FIFA World Cup 2030 in Spain and Andorra.
All 104 matches will air live, and one match per matchday will be free in Spain, according to a Netflix statement.
Chief Content Officer Bela Bajaria said, “Few events unite people like the World Cup.” Netflix also holds Women's World Cup rights for 2027 and 2031 in the U.S. and Canada.
Gaming is a small segment, but it's growing rapidly. Peters said monthly active players for cloud games rose 11x since October.
My Take: Is NFLX Stock a Buy?
Netflix has scale, a low price per hour, and a thriving ad business.
Ad revenue growth of 35% a year is ambitious, and viewing hours grew only 2% in the first half. Content spending is forecast to rise about 10% this year, while steady price hikes only work if it can retain customers amid a challenging macro environment.
Netflix is also testing free trials for new members who aren't rejoining in several countries. I read that as a company willing to experiment to keep sign-ups flowing.
My view is cautiously bullish. I would watch three things: ad revenue growth, how members react to price increases, and view hours. If those hold up, the upside Jefferies sees looks reachable.
If NFLX trades at 25x forward earnings, below its five-year average of 33x, it could more than double by the end of 2029.
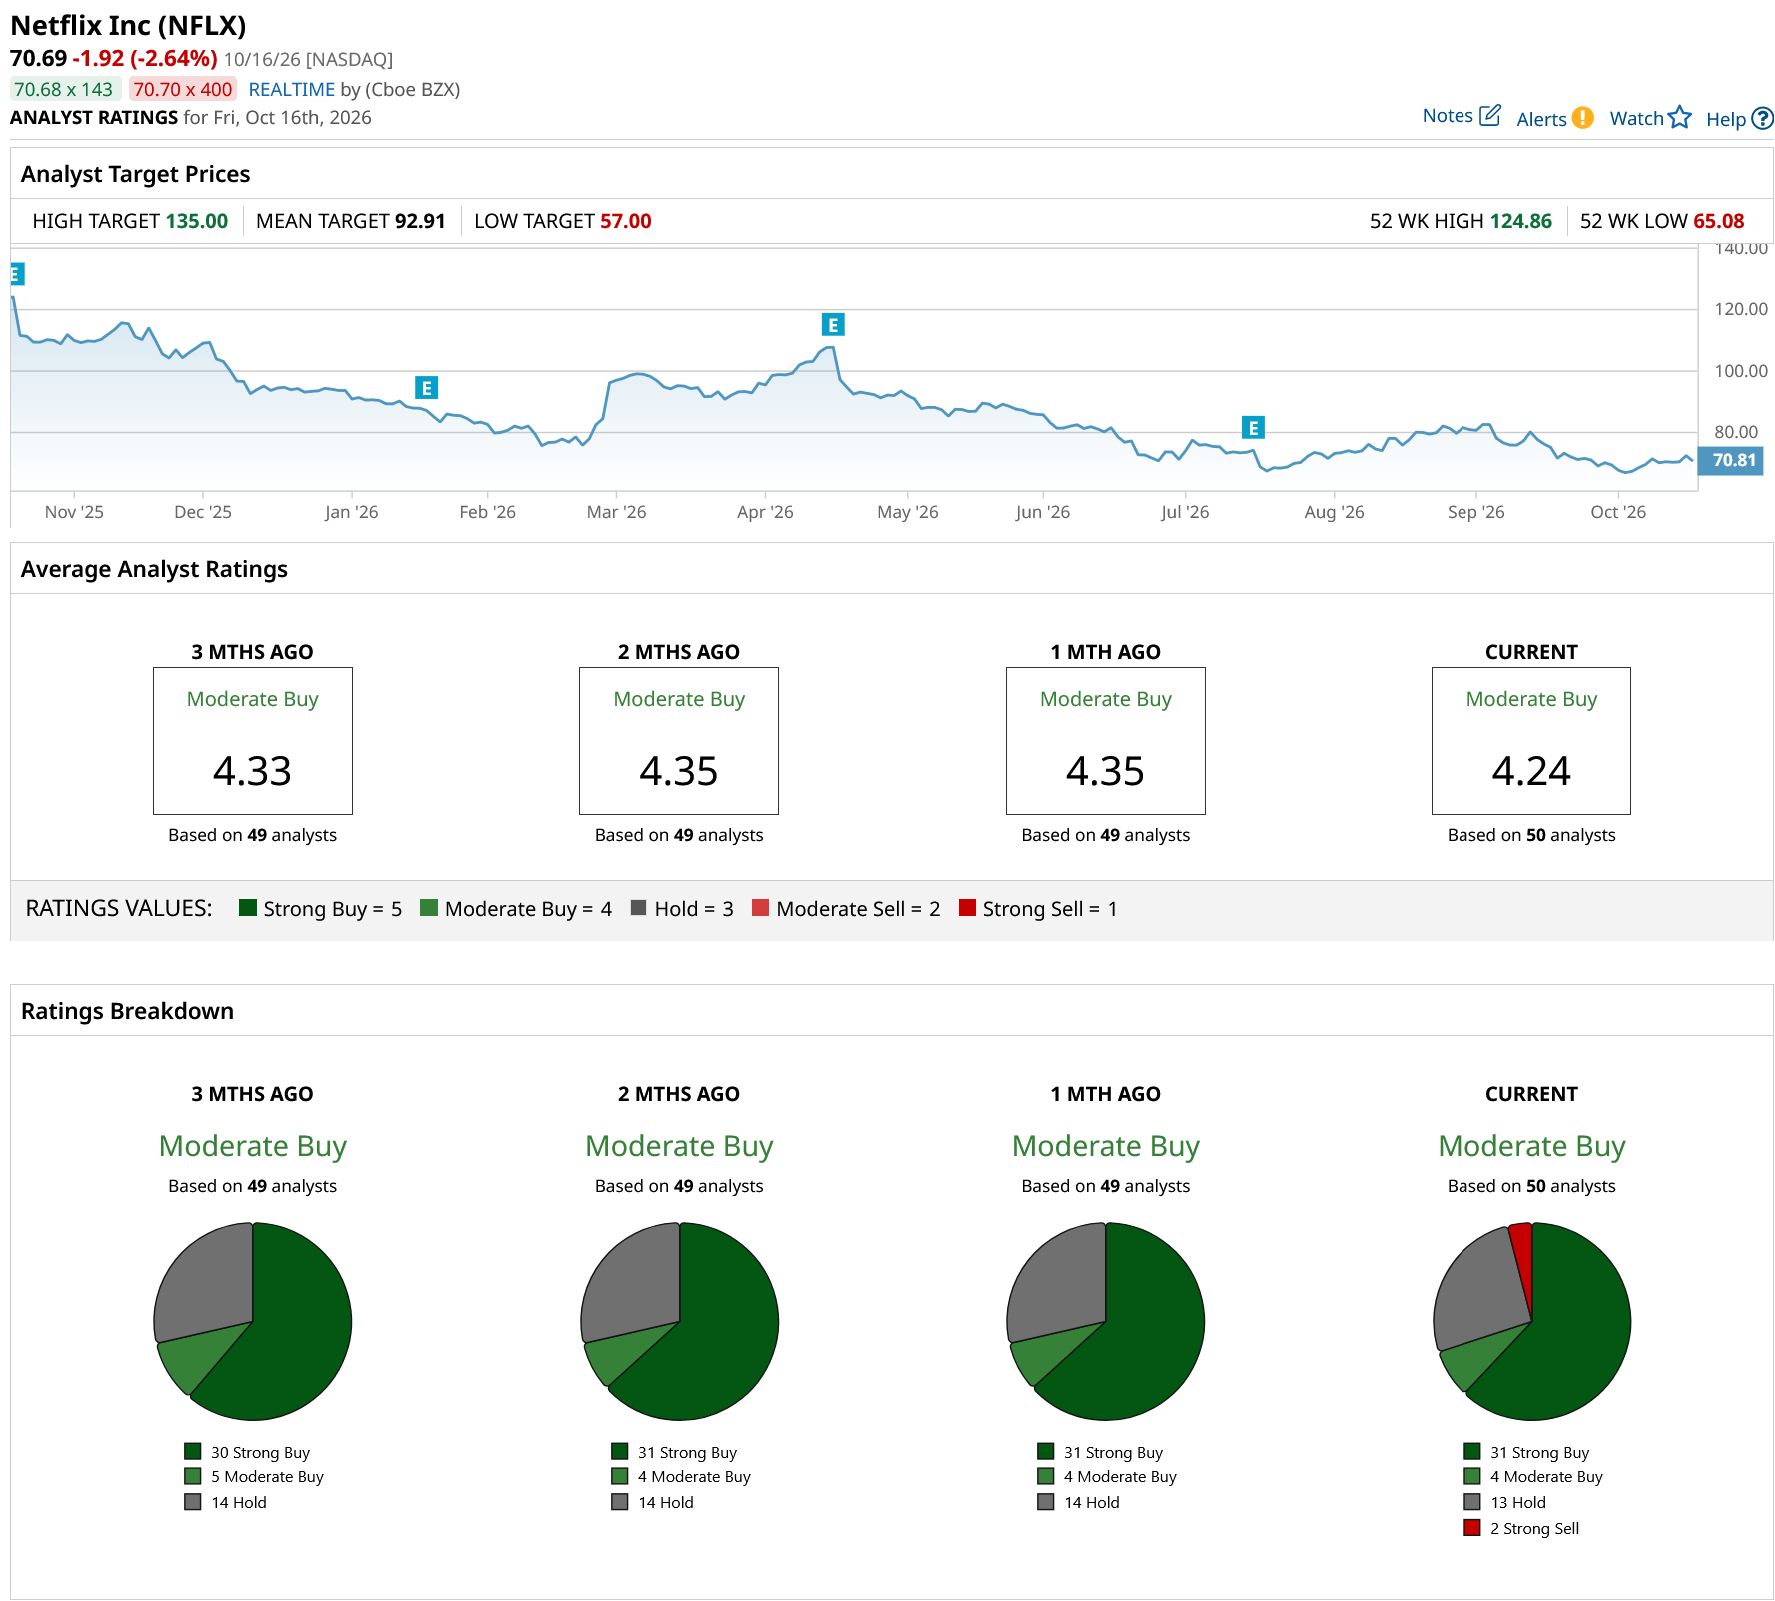
Out of the 50 analysts covering NFLX stock, 31 recommend “Strong Buy,” four recommend “Moderate Buy,” 13 recommend “Hold,” and two recommend “Strong Sell.” The average NFLX stock price target is $92.91, above the current price of about $71.
 www.barchart.com
On the date of publication, Aditya Raghunath did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Jefferies Makes a Bold $85 Call on Netflix Stock What a New Nvidia-Backed AI Platform Means for Honeywell Stock Elon Musk Admits He Has ‘No Idea’ How to Make Chips. Tesla Investors May Help Pay for Him to Learn. AI Sector Pressure, Earnings and Other Key Things to Watch this Week