

Meta Platforms (META) reports third-quarter results on Oct. 21, and the earnings number could look ugly. Meta expects to book a $10 billion legal charge this quarter, stemming from an August settlement with dozens of state attorneys general over claims that its apps harmed young users.
Bank of America analyst Justin Post cut his Q3 EPS estimate from $7.08 to $3.79 because of it. That’s well below the consensus of around $6. Still, Post thinks the core business is doing better than expected. He sees artificial intelligence (AI)-driven ad growth lifting revenue to $63.8 billion, above the $63.3 billion consensus. He kept his “Buy” rating and $810 price target, which implies about 15% upside as of this writing.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Why the Charge Looks Worse Than It Is
The full settlement is worth up to about $18 billion, paid in yearly installments over 10 years. Meta is booking about $10 billion of that as an expense this quarter. Only about $12.7 billion of the total is guaranteed. The other $5.3 billion depends on YouTube and TikTok making similar changes and payments. Investors liked the deal, sending the stock up about 4% when it was announced. Still, the market can be harsh on earnings per share (EPS) misses. Last quarter, higher legal and severance costs led to a miss, and the stock fell about 9% the next day.
Spending is the bigger question. Post expects Meta to narrow its 2026 capital spending guidance to $140 billion to $145 billion, a figure I think has scared investors more than it should. He also warned that heavier AI spending could weigh on 2027 earnings. I’ll be watching for updates on Muse AI, launched in September, and on how Meta plans to make money from its AI tools.
About Meta Stock
Meta Platforms is a global technology company that develops products and platforms that help people connect and communicate with their friends and family. The company operates through the Family of Apps (FoA) and Reality Labs (RL) segments. Its product portfolio includes Instagram, Facebook, WhatsApp, Threads, Meta AI, Messenger, AI-powered smart glasses, and others. Founded in 2004, the company is headquartered in Menlo Park, California.
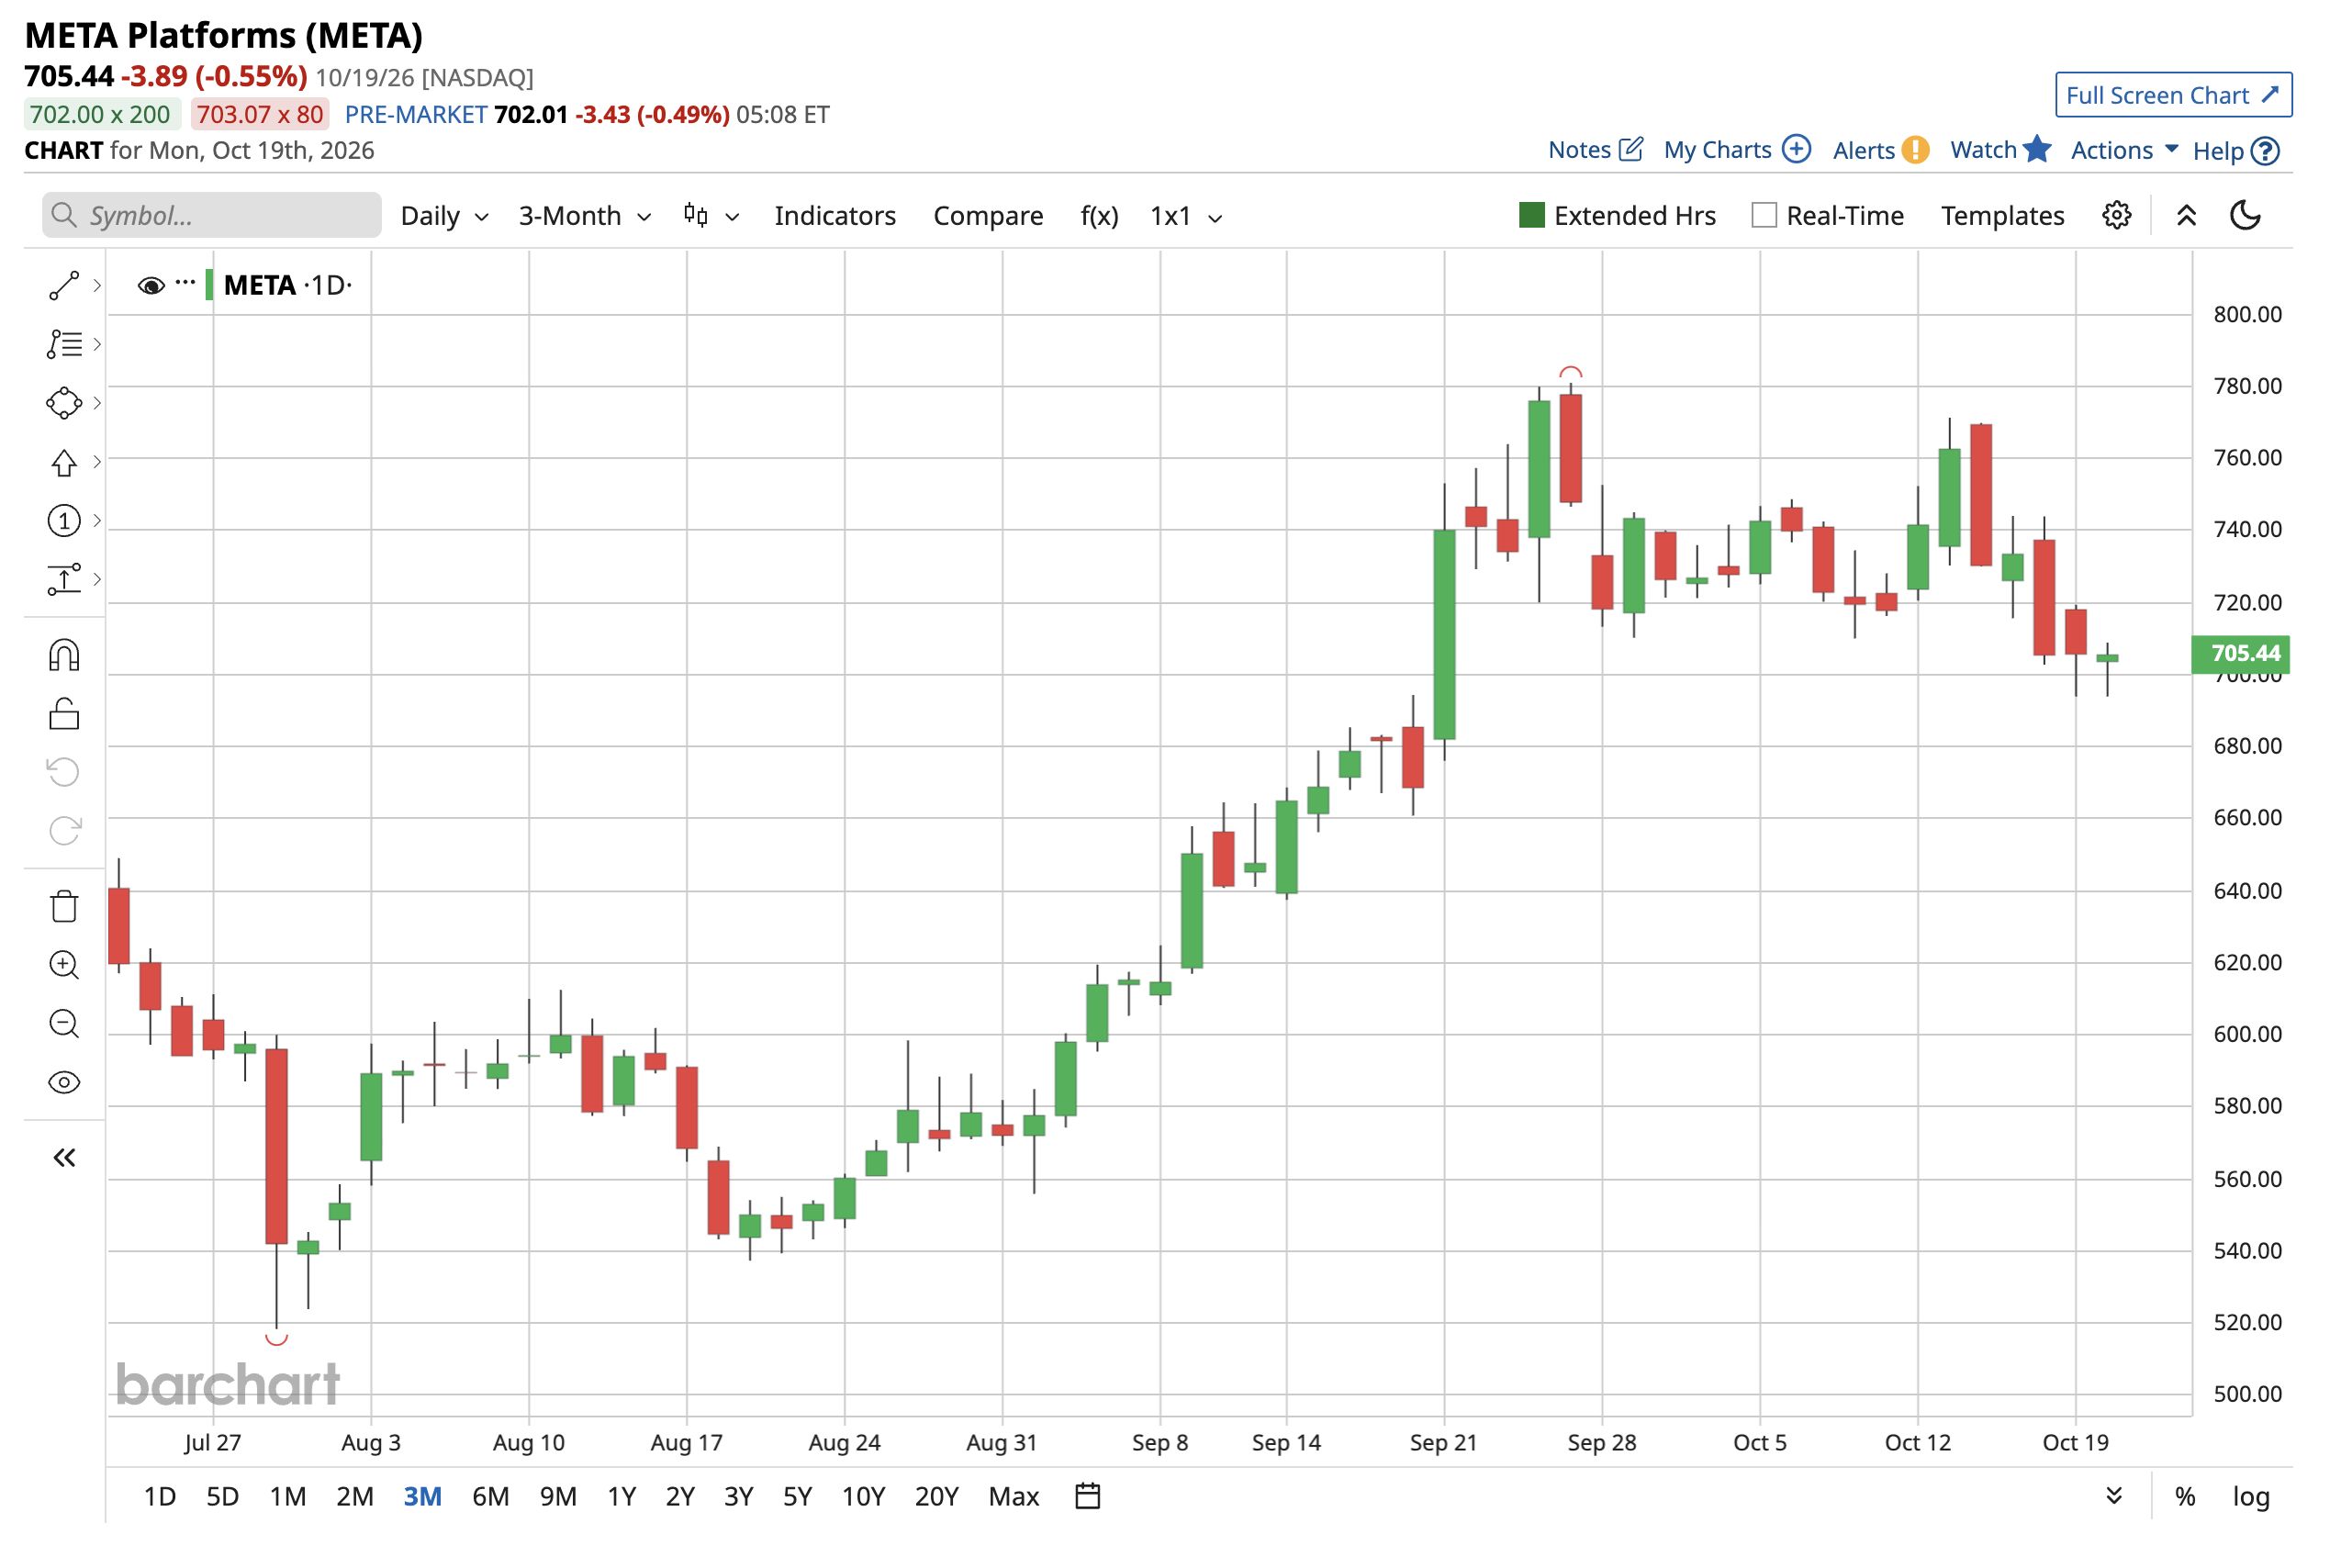
Over the past year, Meta has significantly underperformed the S&P 500 ($SPX). The broader index posted gains of around 14% while the stock declined approximately 4% during the same period. That created a performance gap of more than 18 percentage points. Both dropped sharply around March 2026 during broader market volatility. However, Meta’s rebound came later and was driven largely by company-specific news. Its personal AI agent, Muse, launched on Sept. 8 and quickly rose to the top of the Apple App Store, which eased investors' worries about the company’s heavy AI spending.
 www.barchart.com
Meta’s Q3 Outlook Tests Investor Confidence in Its AI Strategy
The company reported its second-quarter fiscal 2026 earnings on July 29. During the quarter, total revenue reached $60.8 billion, representing a 28% year-over-year increase. FoA remained the main driver of the business, generating $60.4 billion in revenue. On a GAAP basis, earnings came in at $6.18, missing consensus estimates by $1.04. Total expenses rose 55% year over year to $42 billion, including $2.4 billion in legal-related charges and $1.2 billion in severance costs tied to the May 2026 headcount reduction.
Looking forward, the company expects third-quarter 2026 total revenue to be in the range of $61 billion to $64 billion. Total expenses for the quarter are expected to be in the range of $165 billion to $169 billion. Moreover, the company expects capital expenditures, including principal payments on finance leases, to be in the range of $130 billion to $145 billion.
JPMorgan asked the company about its plans to improve its recommendation systems. CFO Susan Li said there is still room to improve recommendations through the rest of 2026 and into 2027. CEO Mark Zuckerberg added that Meta does not have enough computing capacity to meet demand for its AI services and wants to expand capacity to capture opportunity.
What Do Analysts Expect for META Stock?
Needham analyst Laura Martin reiterated a “Hold” rating on META. The analyst’s rating reflects Meta’s recent shift away from its Metaverse strategy toward personal AI assistants built around its Muse platform. Although Meta’s stock has risen about 27% since early September, Laura believes the rally has already reflected much of the expected benefit from this shift. In contrast to Needham, Jefferies maintained a “Buy” rating with a price target of $875.
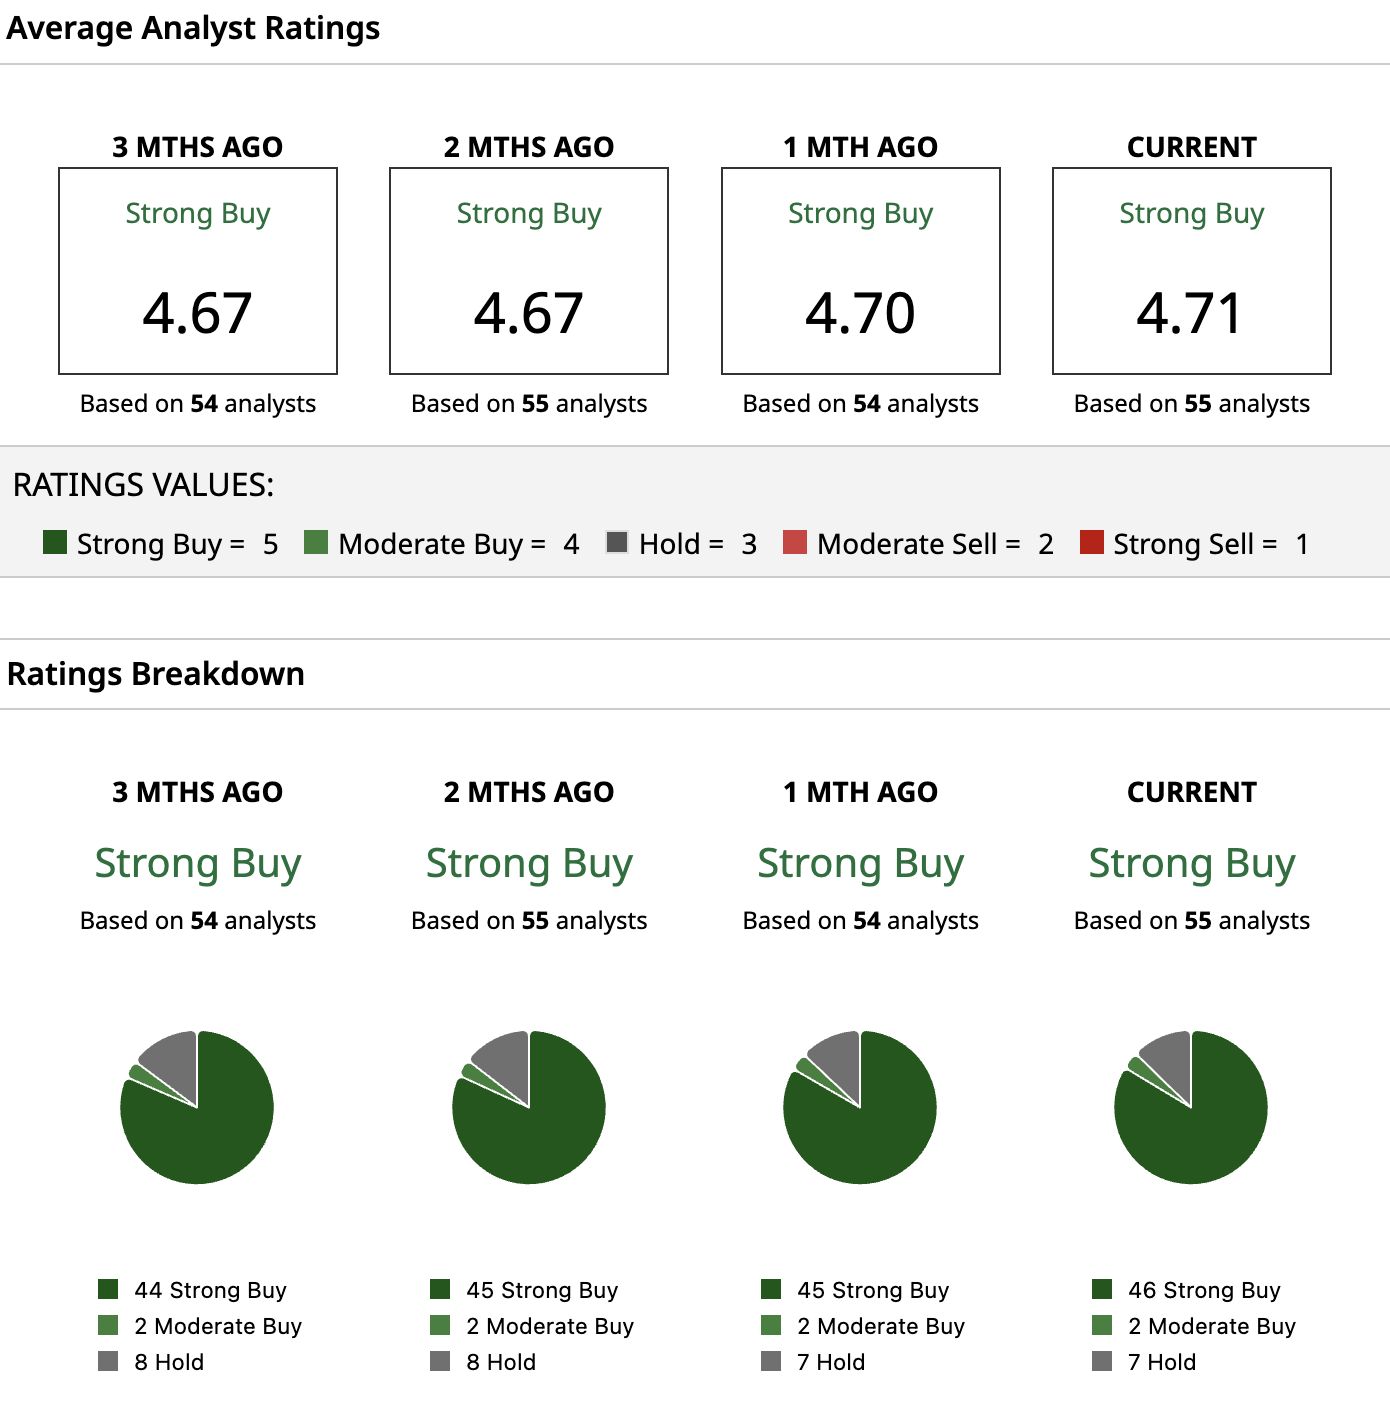
Based on 54 Wall Street analysts covering the stock, META holds a consensus “Strong Buy” rating. It has a mean price target of $804, which reflects a modest 12% upside from current levels. The high price target of $1050 implies 46% upside from the current share price. This shows that analysts remain optimistic about Meta’s long-term prospects.
 www.barchart.com
On the date of publication, Jabran Kundi did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
10 Billion Reasons Meta’s Q3 EPS Could Shock You, and Not How You Think Down 12% in 1 Month, Bloom Energy Faces a Big Test on October 22. Here’s My Prediction. You Won’t Get Rich Investing in This Beaten-Down Stock, But You Don’t Need To. ‘No Question Tesla’s Going to Merge With SpaceX’ — Kevin O’Leary Says If You Own Tesla Stock, You’ll Own the New Company After Flying Roadster Demo