

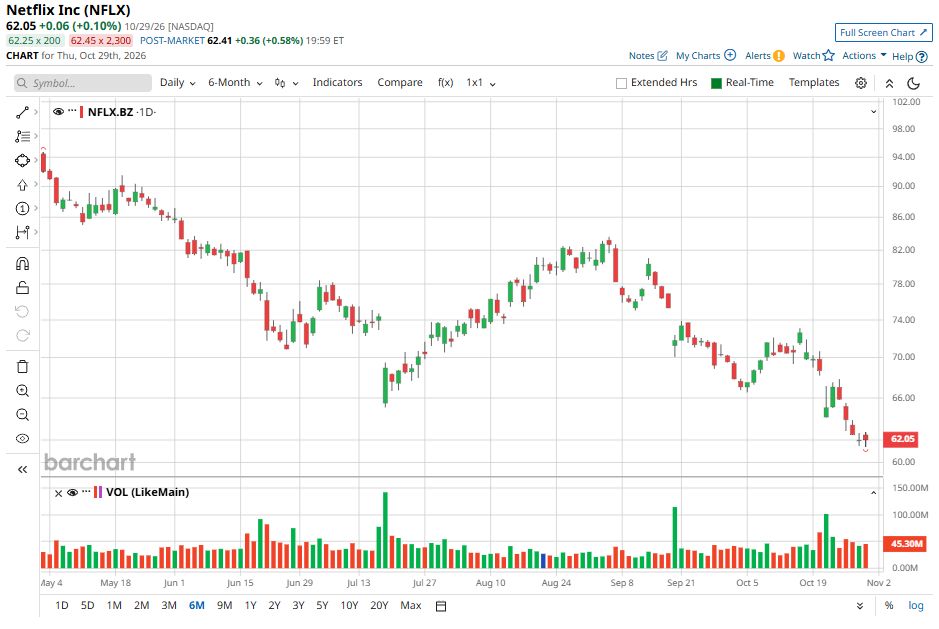
Netflix (NFLX) has faced considerable pressure in 2026, with its share price declining about 34% year-to-date (YTD) and trading nearly 47% below its 52-week high. The sell-off reflects growing investor concerns about the company's ability to sustain its growth momentum amid heightened competition.
Although Netflix continues to benefit from pricing flexibility, a sticky subscriber base, and a lower valuation multiple following the recent correction, these factors do not justify an immediate buy.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Why Is Netflix Stock Under Pressure?
The primary reason for Netflix's share price weakness is slowing revenue growth. The company's financial performance shows a gradual moderation in its top-line growth rate in recent quarters, raising questions about the sustainability of its growth trajectory.
Netflix reported revenue growth of 17.6% in Q4 2025. However, the growth rate fell to 16.2% in Q1 2026 and 13.4% in Q2 2026, then moderated further to 11.8% in Q3 2026.
 www.barchart.com
Beyond the reported financial figures, concerns about user engagement are adding to the negative sentiment. Netflix is competing for viewers' time against short-form video platforms such as YouTube. These alternatives offer easily accessible, continuously refreshed content, potentially limiting the amount of time consumers dedicate to subscription-based streaming services.
Netflix’s forward guidance has further pressured the stock. For Q4 2026, Netflix projected revenue of $13.44 billion, below Wall Street's consensus estimate. The forecast also points to another sequential slowdown in revenue expansion, with the expected growth rate declining to approximately 11.5%.
Another potential concern is the reduction in the 2026 advertising revenue outlook. NFLX lowered its full-year 2026 advertising revenue target to $2.7 billion from $3 billion. This revision reflects a slower-than-anticipated rollout of certain advertising capabilities.
The advertising opportunity remains strategically important because it could diversify Netflix's revenue streams and create an additional monetization channel without relying exclusively on subscription price increases.
Taken together, moderating revenue growth, intensifying competition for viewer engagement, conservative quarterly guidance, and a cut in advertising guidance create a challenging near-term backdrop.
Don’t Rush to Buy Netflix Stock
Netflix reported $12.9 billion in Q3 revenue, up 11.8% from the prior-year period. Profitability also improved significantly, with its operating margin expanding to 34.6% from 28.2% in Q3 2025.
Looking ahead, Netflix has several growth drivers supporting revenue and earnings, including subscriber additions, further price increases, and expansion of its advertising business. Subscriber retention remains encouraging across geographical markets, with both global and U.S. churn rates declining year-over-year (YoY) in Q3. This suggests that customers have largely absorbed recent pricing adjustments without a deterioration in retention.
Netflix has a strong content lineup planned for Q4 and is broadening its entertainment portfolio through licensing agreements and more third-party programming. These initiatives could help diversify its content offering, strengthen viewer engagement, and create further monetization opportunities.
In addition, the recent pullback in Netflix shares has compressed its valuation to about 17.4 times forward earnings. Although this represents a discount to the premium multiples Netflix has historically commanded, a lower valuation multiple doesn’t make NFLX undervalued.
Analysts’ earnings estimates indicate that this lower multiple is justified. Analysts expect Netflix to generate earnings of $3.75 in 2027, implying 4.5% YoY growth. Moreover, NFLX stock still trades at a premium to peers. For comparison, Disney (DIS) stock trades at approximately 14.7 times forward earnings, below Netflix's current multiple.
Therefore, Netflix continues to grow revenue and earnings, has a resilient subscriber base, and has promising monetization opportunities. However, its valuation does not yet present a compelling entry point.
NFLX Stock: A Recovery Story That Still Needs Proof
Netflix’s recent correction has made its valuation more reasonable, but the stock does not yet offer a compelling buying opportunity. Slowing revenue growth, intensifying competition for viewer engagement, and a lower advertising revenue outlook suggest that near-term growth could remain under pressure.
While pricing power, subscriber retention, and advertising expansion offer long-term upside, modest earnings growth and a premium valuation relative to peers could limit the recovery rally.
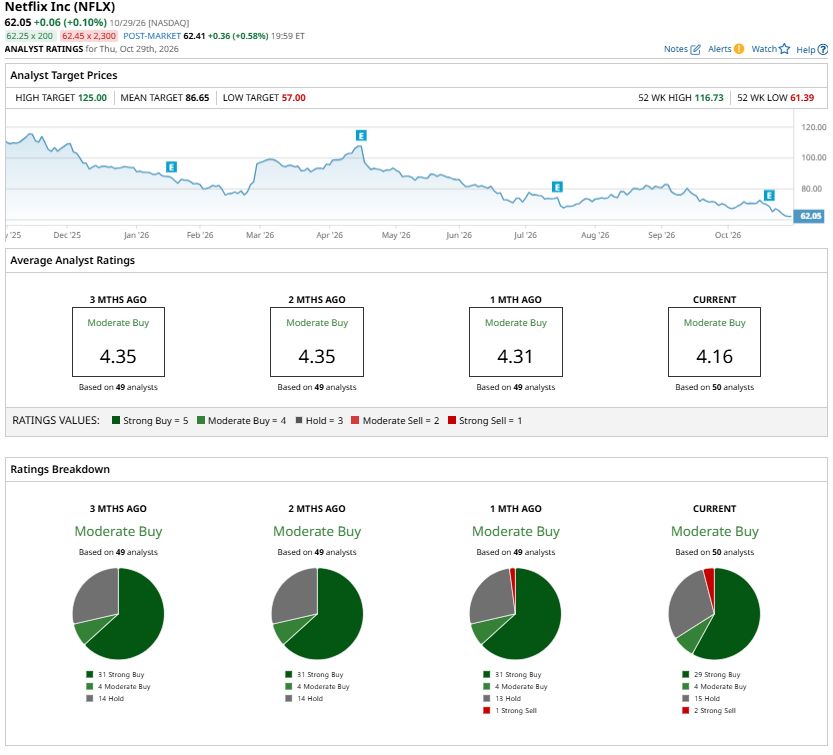
For now, investors may be better off waiting for clearer signs that revenue growth is stabilizing and monetization is improving before investing in NFLX. Analysts keep a “Moderate Buy” consensus rating on the stock.
 www.barchart.com
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.