

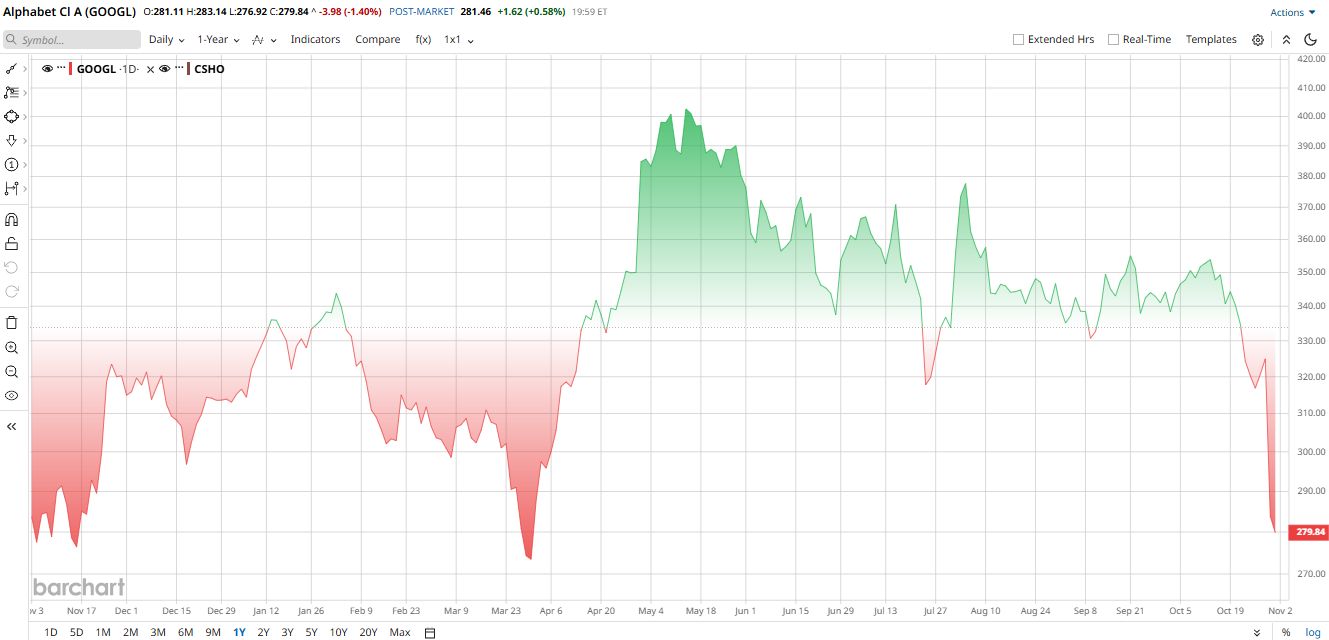
Alphabet (GOOGL) experienced the worst trading session in its history on Oct. 29, when shares plummeted nearly 13%. The historic crash wiped out roughly $500 billion in market value in a single day, making it the second-largest single-day market-cap loss for any U.S. company on record. GOOGL stock is now down nearly 19% over the past month and down 10% year-to-date (YTD).
The selloff came on the heels of Google Cloud's remarkable 103% year-over-year (YOY) revenue growth. Despite those fantastic results, investors were still not pleased.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
There appears to be a disconnect about the cost of growth. Google Cloud continues to grow, but Search failed to perform well enough while artificial intelligence (AI) remains an expensive undertaking. In particular, investors want to know when the company's AI spending will convert into solid profit.
New findings only added to the worries about how AI might impact Google's search experience. Now, investors are eyeing the returns Alphabet expects from its AI investment, rather than just Google Cloud's growth.
 www.barchart.com
Google Cloud Is a Major Growth Engine
From my perspective, Alphabet posted some outstanding numbers for the third quarter. Google Cloud revenue climbed to $30.7 billion, up 103% YOY and accelerating from 82% growth in the previous quarter. Cloud backlog reached $561 billion during Q3, with management expecting to recognize more than half of that figure over the next two years. On the other hand, Google Cloud’s operating margin reached 36.2%.
Meanwhile, Alphabet is also selling its custom Tensor Processing Units (TPUs) to outside customers such as Anthropic (ANT) and Oracle (ORCL), creating another way to benefit from AI infrastructure demand.
Still, a backlog is not cash in the bank. Alphabet has to build data centers, buy chips, and secure power before it can fulfill that demand.
AI Investment Is Weighing on Cash Flow
Here comes the scary part for investors. Capital expenditures came to $51.4 billion in Q3, while free cash flow was -$9.1 billion. Even more spending is expected in 2027, with analysts believing that annual capex may top $300 billion by the end of next year.
Alphabet's spending would have been more palatable if the other financial figures from the quarter had come in stronger. Total revenue grew 25% YOY to $127.6 billion but came in below estimates. EPS of $2.12 also missed the $3.01 consensus estimate.
Overall, investors would like to see that Alphabet's growth prospects are able to generate sufficient cash for its expansion efforts.
Search and Gemini Are Other Pieces of the Story
Alphabet’s advertising business is still growing, but the Q3 numbers weren’t entirely reassuring. Search and other revenue grew 12% YOY to $63.35 billion, while YouTube ads revenue grew 10% to $11.21 billion. Search fell short of expectations. This is significant because advertising continues to be Alphabet's business backbone, and AI-driven search might alter how ads contribute to Google's broader ecosystem.
Still, Alphabet is adapting. Search query growth was its strongest in five years, according to CEO Sundar Pichai. The company is expanding its AI Overviews and building out Gemini, which now has more than 1 billion app users. That gives Google both subscription and advertising opportunities. The problem is converting that AI audience into revenue without compromising Search.
Meanwhile, the valuation of GOOGL stock is trading below norms. Alphabet stock now trades at 14.8 times trailing earnings, which is lower than the communication services sector average of roughly 21 times. The forward price-to-earnings (P/E) ratio of 13.9 times also points to expected lower earnings amid increased spending.
Wall Street Still Sees Upside
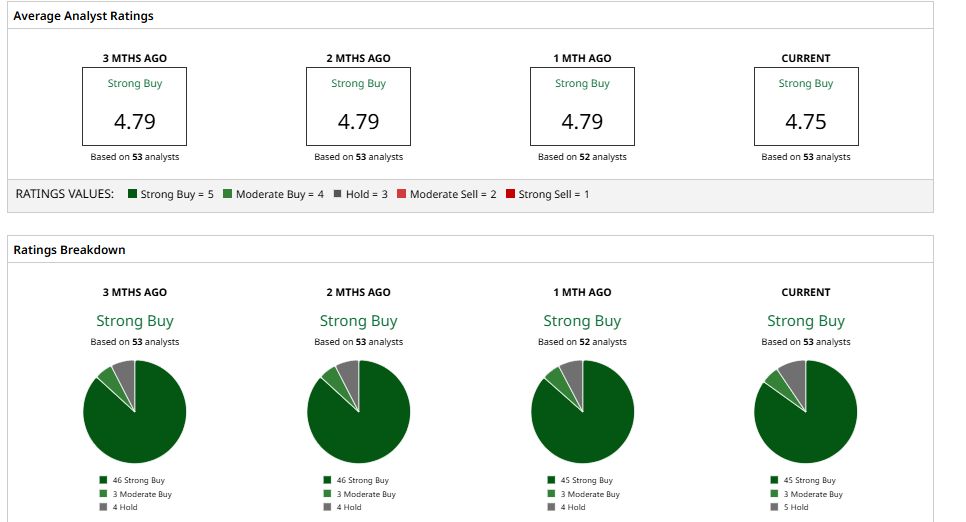
Despite the recent selloff and some analyst downgrades, GOOGL stock has a consensus "Strong Buy" rating on Wall Street. The average price target of $406.04 implies potential upside of roughly 46% from current levels.
Some firms trimmed their expectations after Q3 earnings. Recently, Citigroup and JPMorgan both cut their price targets to $375. Cantor Fitzgerald also lowered its target to $350 but kept an “Overweight” rating, while D.A. Davidson has a "Neutral" rating with a $300 target. Finally, Needham is more bullish with a $450 price target and a “Buy” rating.
The post-earnings debate now revolves around a cash-flow investment thesis. Investors want to see whether Cloud and Gemini can produce attractive returns — and eventually cash flow — while Search continues to fund the business.
 www.barchart.com
On the date of publication, Nauman Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Dear Qualcomm Stock Fans, Mark Your Calendars for November 4 GOOGL Stock Is Down 10% YTD. Alphabet’s Historic Selloff Could Be a Buying Opportunity. Dear Arm Stock Fans, Mark Your Calendars for November 4 Dear Arista Networks Stock Fans, Mark Your Calendars for November 3