

Franklin Templeton Inc. (BEN), headquartered in San Mateo, California, is a global investment management firm serving clients in over 150 countries. Valued at $16.4 billion by market cap, the company offers a wide range of services across equity, fixed income, alternative investments, and multi-asset strategies, and manages over $1.8 trillion in assets.
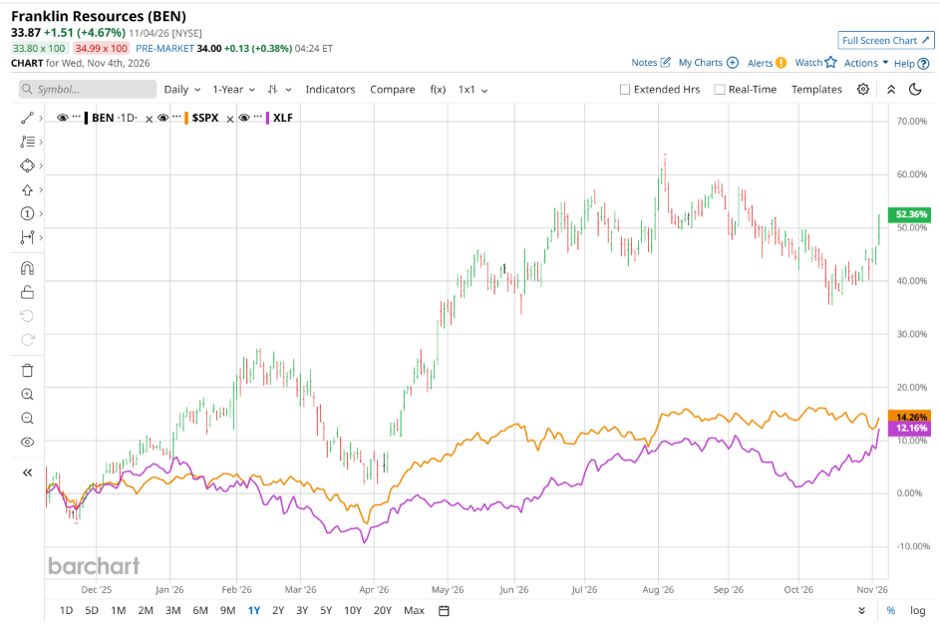
Shares of this leading investment manager have outperformed the broader market over the past year. BEN has gained 49.9% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 13.5%. In 2026, BEN stock is up 41.8%, surpassing the SPX’s 12.3% returns on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Zooming in further, BEN’s outperformance looks more pronounced compared to the State Street Financial Select Sector SPDR ETF (XLF). The exchange-traded fund has gained about 12.9% over the past year. Moreover, the stock’s double-digit gains on a YTD basis outshine the ETF’s 8.1% returns over the same time frame.
 www.barchart.com
BEN has delivered strong performance posting a total return of over 40% and outpacing the broader financial sector as its stock rebounded from multi-year lows. This outperformance has been driven by general equity market strength and record AUM, which reached $1.8 trillion in August 2026. A key driver of this turnaround is the moderation and periodic reversal of long-standing fund outflows, which barring a sharp shift in investment performance position asset flows to continue trending upward. Furthermore, recent acquisitions are now being more fully integrated, expanding high-margin alternative asset capabilities and bolstering consecutive quarters of solid earnings beats.
For the current fiscal year, ended in September, analysts expect BEN’s EPS to grow 31.1% to $2.91 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
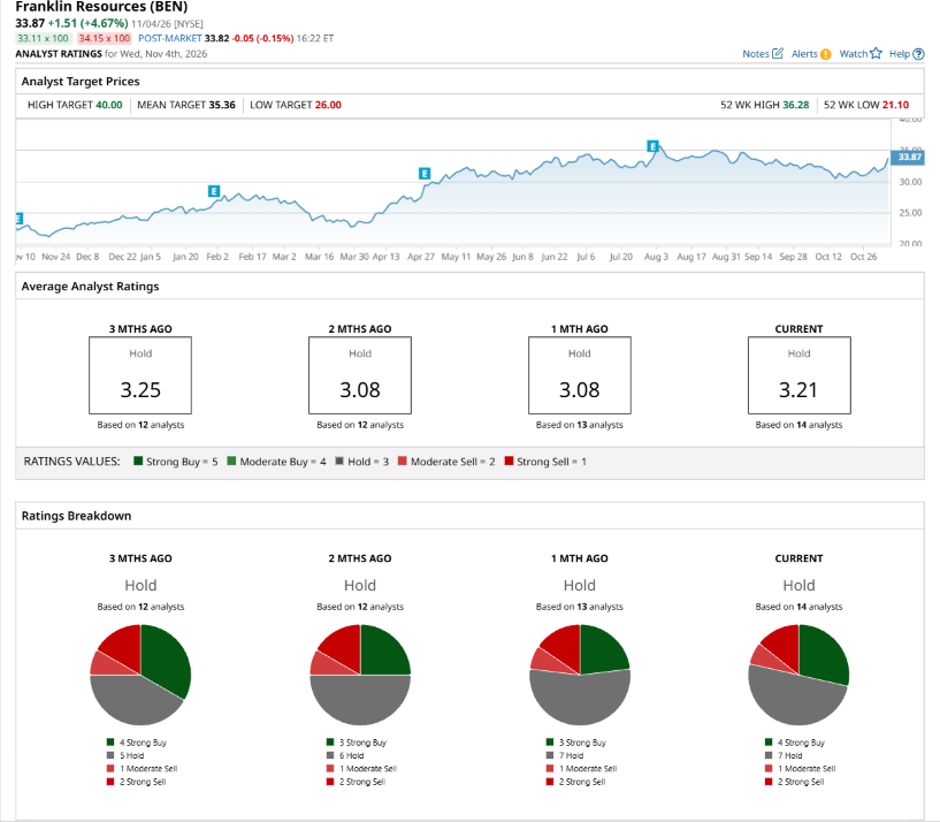
Among the 14 analysts covering BEN stock, the consensus is a “Hold.” That’s based on four “Strong Buy” ratings, seven “Holds,” one “Moderate Sell,” and two “Strong Sells.”
 www.barchart.com
This configuration is more bullish than a month ago, with three analysts suggesting a “Strong Buy.”
On Oct. 28, Morgan Stanley (MS) analyst Michael Cyprys maintained a “Hold” rating on BEN and set a price target of $35, implying a potential upside of 3.3% from current levels.
The mean price target of $35.36 represents a 4.4% premium to BEN’s current price levels. The Street-high price target of $40 suggests an upside potential of 18.1%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Short Straddle Screener Results for November 5th Nasdaq Futures Slip as Chip Stocks Extend Slide; Earnings and Fed Speak on Tap Nike’s Dividend Yield Is Still Attractive, But I Can’t Say the Same About NKE Stock Dear Airbnb Stock Fans, Mark Your Calendars for November 5