

Qualcomm’s (QCOM) financial performance has been unimpressive in the last few quarters. Recently, the company reported Q4 FY26 results with a year-on-year (YoY) decline in revenue coupled with margin compression.
The main culprit was the company’s QCT segment that reported its third consecutive quarter of YoY decline in revenue. This was primarily due to a decline in handset revenue even as automotive segment revenue growth was robust.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The handset business has been impacted by a challenging memory and supply environment. With component cost inflation, handset makes have seen a negative impact on volumes and margins. This has directly impacted chip orders.
Amidst these challenges, it seems like a good time to accumulate QCOM stock. Valuations are attractive, and it’s likely that other business divisions will gradually offset the challenging conditions in the handset market.
About Qualcomm Stock
Headquartered in San Diego, Qualcomm is involved in the development and commercialization of foundational technologies for the wireless industry. This includes advanced artificial intelligence, high-performance and low-power computing, and leading connectivity.
The company’s products and services are used globally, across industries and applications from handsets to automotive, the internet of things, and data centers. Qualcomm derives its revenue from sales of integrated circuit products and licensing of its intellectual property, including patents and other rights.
The company’s reportable segments include QCT (Qualcomm CDMA Technologies), semiconductor business, and QTL (Qualcomm Technology Licensing) business. For FY26, Qualcomm reported revenue of $43.2 billion, which was lower by 2% on a YoY basis. For the same period, the company’s earnings before tax declined by 16% to $13 billion.
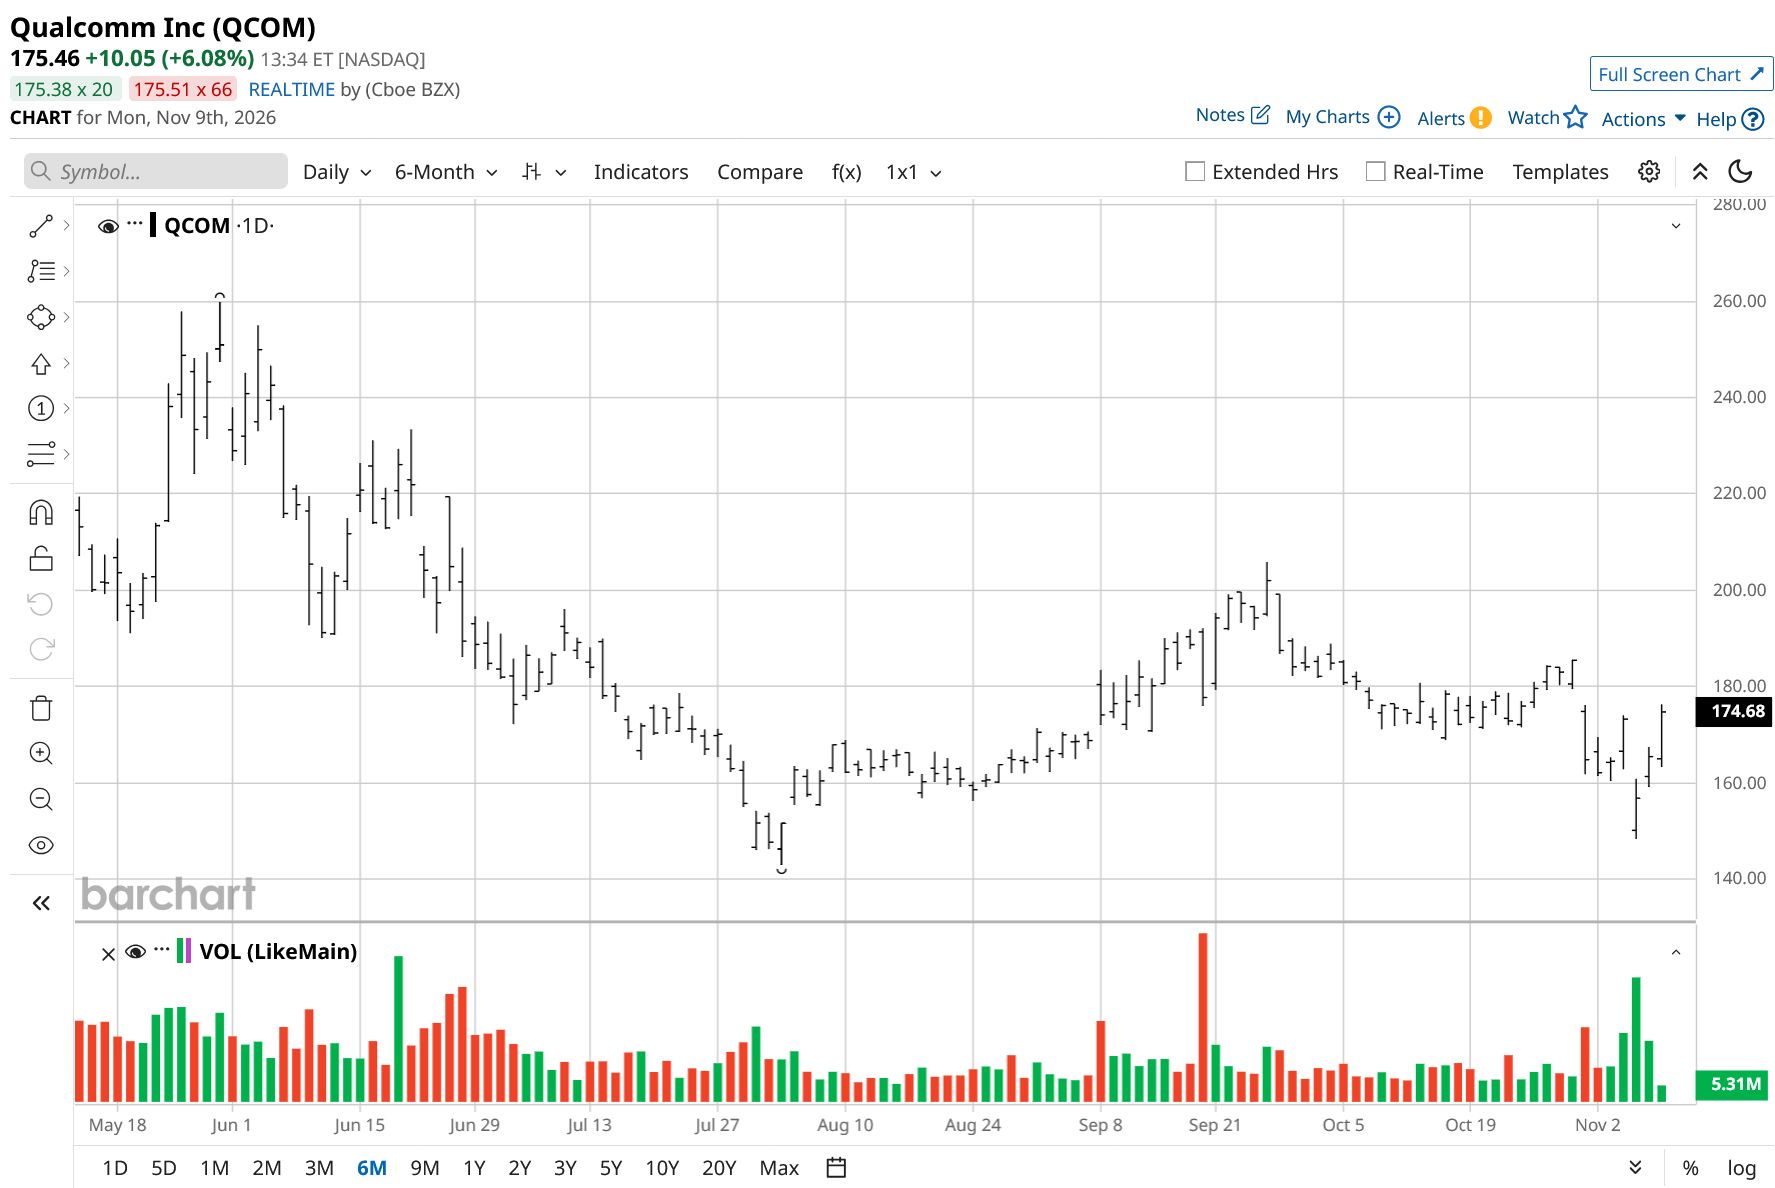
QCOM stock has mirrored the muted financial performance with a decline of 20% in the past six months. At the same time, a broader selloff in tech stocks has also impacted sentiments.
 www.barchart.com
Strong Growth in Automotive Business
It’s worth noting that for FY26, Qualcomm reported a 13% YoY decline in handset revenue to $24.1 billion. However, overall QCT revenue declined by only 3%. The reason was a 52% YoY growth in automotive revenue to $6 billion. At the same time, IoT revenue increased by 8% to $7.1 billion. These segments partially offset the negative impact of handsets.
The second positive for Qualcomm is growth in data center revenue in FY27. For Q1, the company expects data center revenue of $650 million. Qualcomm further expects to exit FY27 with $7 billion in annualized run-rate. The company has also guided for a strong YoY growth in FY28. The revenue target from the data center segment for FY29 is in excess of $15 billion. Therefore, the division is likely to create incremental value in the coming years.
Margin compression is another challenge that has been impacting QCOM stock. The semiconductor industry has witnessed a broad-based increase in input costs. Qualcomm expects to increase prices across its products with the benefit of these actions likely in the second half of FY28. Therefore, the worst might be over in terms of margin compression.
It’s also worth mentioning that even with the headwinds, Qualcomm reported free cash flow of $8.7 billion in FY26. With margin improvement likely in FY27 and beyond coupled with multiple top-line growth catalysts, higher FCF is likely in the coming years.
What Do Analysts Say About QCOM Stock?
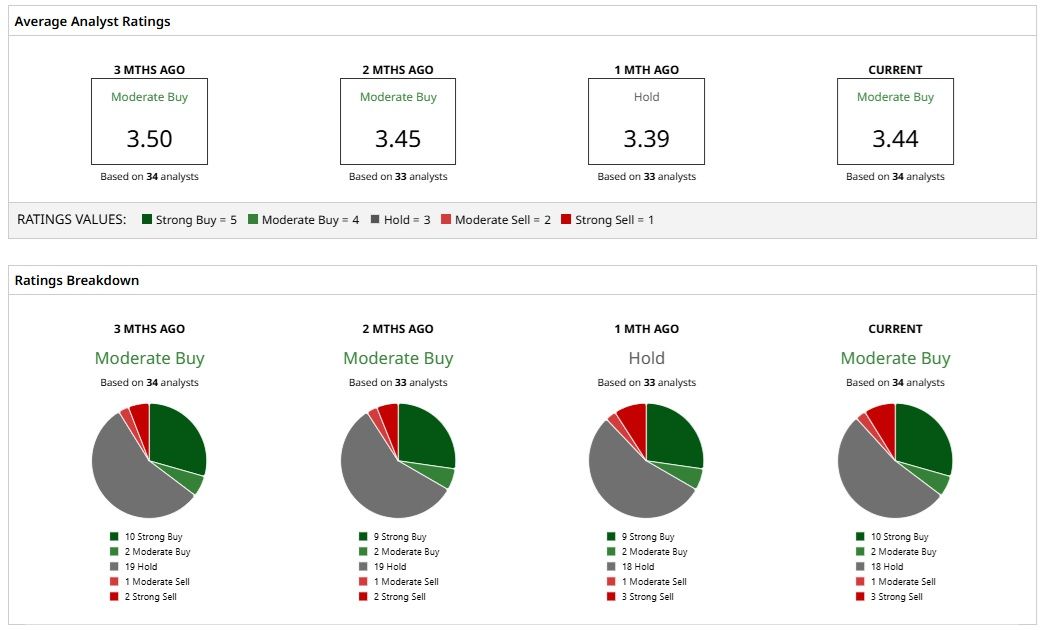
While growth has disappointed, QCOM stock trades at a forward price-earnings ratio of 21.9, and the company also offers a forward dividend yield of 2.35%. Based on 34 analysts with coverage, QCOM has a consensus “Moderate Buy” rating. While 10 analysts have a “Strong Buy” rating for the stock, two have a “Moderate Buy,” 18 have a “Hold,” one has a “Moderate Sell,” and three analysts have a “Strong Sell” rating.
The mean price target of $191.72 represents a potential upside of 9% from current levels. Further, the most bullish price target of $320 suggests that QCOM stock could climb as much as 82% from here.
 www.barchart.com
On the date of publication, Faisal Humayun Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
As Non-Handset Revenue Grows, Qualcomm Is Positioned for Recovery CoreWeave Stock Just Hit a 52-Week Low. Wall Street Sees Nearly 3X Upside by 2027. Unusual Put Options Volume in Walmart Ahead of Earnings Next Week - Is WMT Set to Drop? Warren Buffett’s Successor Is Doubling Down on Berkshire Hathaway Stock. You Probably Shouldn’t