

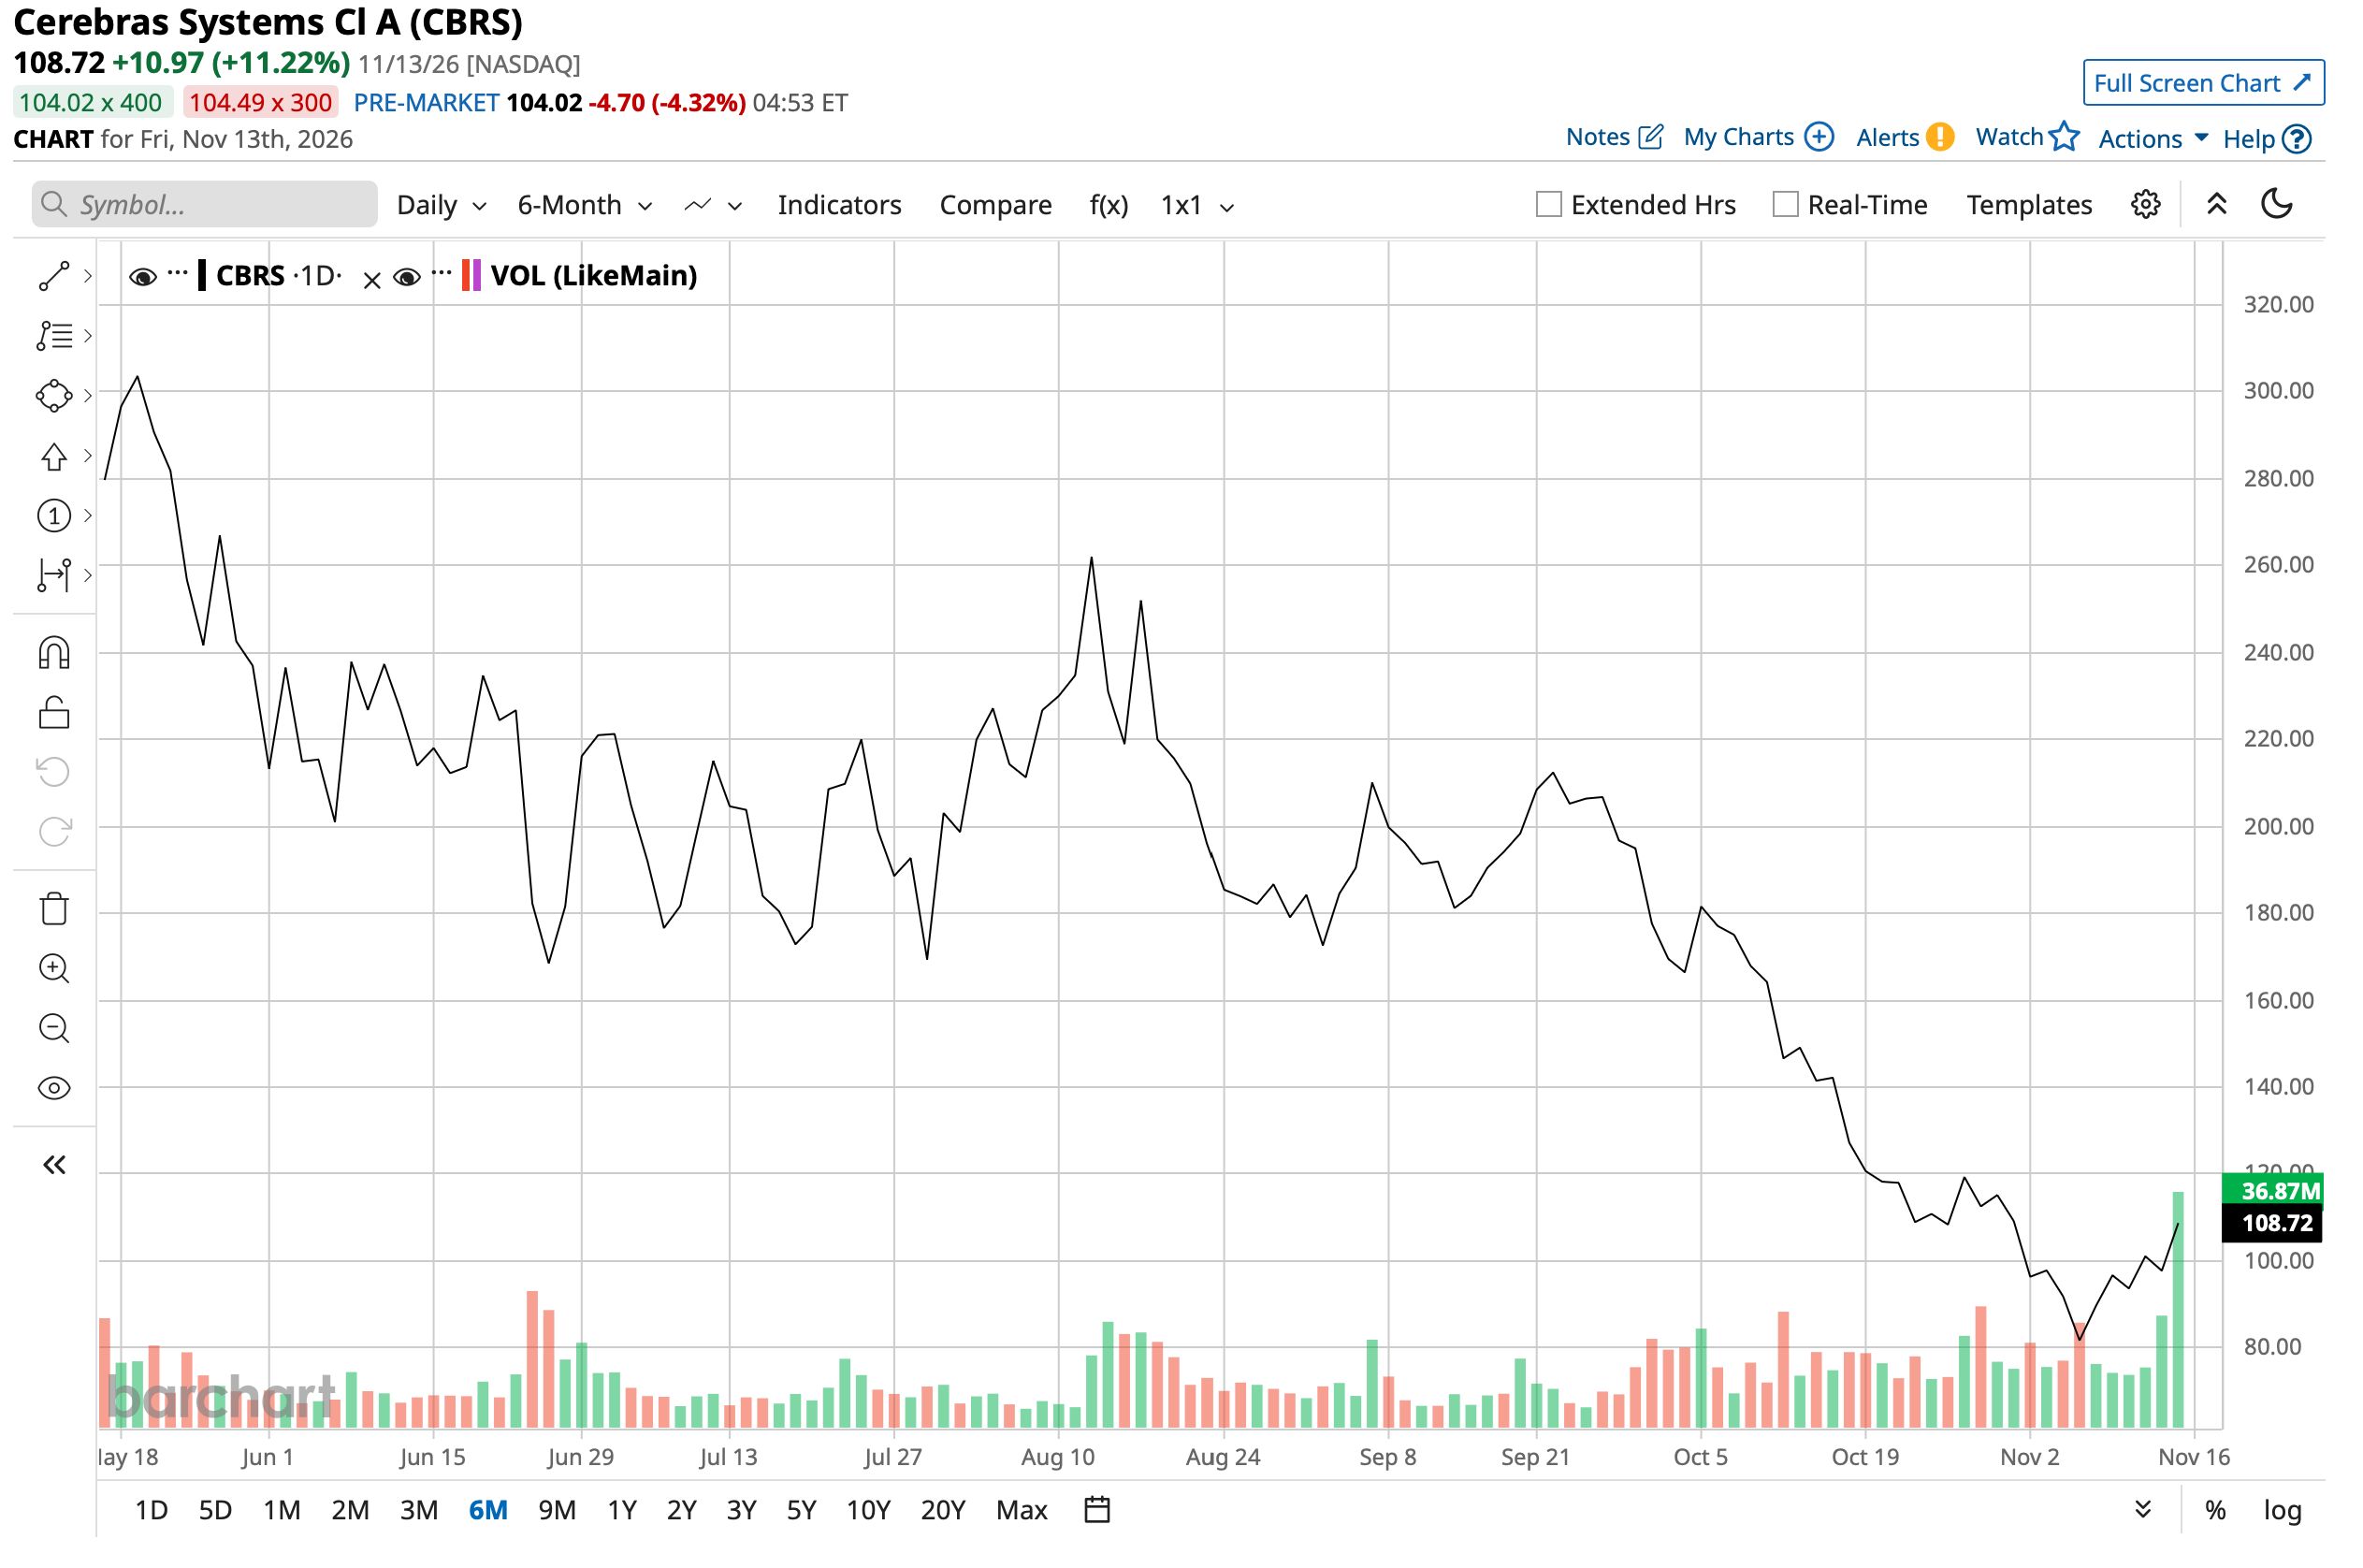
Shares of chipmaker Cerebras Systems (CBRS) rose more than 11% on Nov. 13 after the company revealed better-than-expected third-quarter results and a compute deal with Microsoft (MSFT). This was a much-needed boost for CBRS stock, which currently trades well below not only its all-time high of $386.34 but also its initial public offering (IPO) price of $185 per share.
Remaining convinced of demand, Cerebras raised its revenue guidance for fiscal 2026 alongside the Q3 report as well. Let's take a closer look.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About Cerebras Stock
Founded in 2015, Cerebras develops and supplies artificial intelligence (AI) computing systems, processors, and cloud-based AI infrastructure. Its main product differentiator is its proprietary Wafer-Scale Engine (WSE), which is a huge AI processor. The objective of WSE is to reduce the need to move data between separate processors and external memory, allowing AI workloads to run with much lower communication overhead and latency.
Valued at a market capitalization of $23.9 billion, CBRS stock is currently up 32% from its 52-week low of $77.84 per share. But are the company's Q3 results and latest deal with Microsoft enough to stage a turnaround for the stock? Let's find out.
 www.barchart.com
Cerebras Reports Q3 With a Customer-Concentration Specter
Details about Cerebras' agreement with Microsoft remain limited, as CEO Andrew Feldman noted that more information will be shared in 2027. Nonetheless, this is a positive development that may alleviate some concerns around customer concentration for the company, especially after it also announced agreements with Amazon's (AMZN) AWS and Oracle's (ORCL) Oracle Cloud Infrastructure (OCI).
Still, two customers respectively accounted for 38% and 34% of Cerebras' revenue, with one widely speculated to be OpenAI. Having said that, the company posted record numbers for Q3 2026. Revenue came in at $210.8 million, up 55% year-over-year (YOY), as the cloud segment became its biggest revenue contributor at $141.9 million, up from just $38.9 million in the year-ago period. However, the hardware segment saw revenue decline 29% YOY. While the decline was partly attributable to warrant-related amortization recorded as a reduction in revenue, lower hardware deliveries also contributed to the weakness.
Losses widened to $0.67 per share from $0.41 per share in the year-ago period. Meanwhile, the company remains bullish about revenue growth in fiscal 2026, raising revenue guidance to $940 million to $960 million. Cerebras reported remaining performance obligations (RPO) of $26.1 billion and secured almost 700 megawatts of data-center capacity expected to go live by the end of 2027.
For the nine months ended Sept. 30, 2026, net cash outflow from operating activities widened YOY. Net cash outflow from operating activities was $388.9 million compared to $134.2 million in the year-ago period. Overall, Cerebras ended the quarter with a cash balance of $3.1 billion.
On the valuation front, CBRS stock still trades at elevated levels, even after such a steep correction. Its price-to-sales (P/S) ratio is 32.5 times is much higher than the sector median.
What Do Analysts Think of Cerebras Stock?
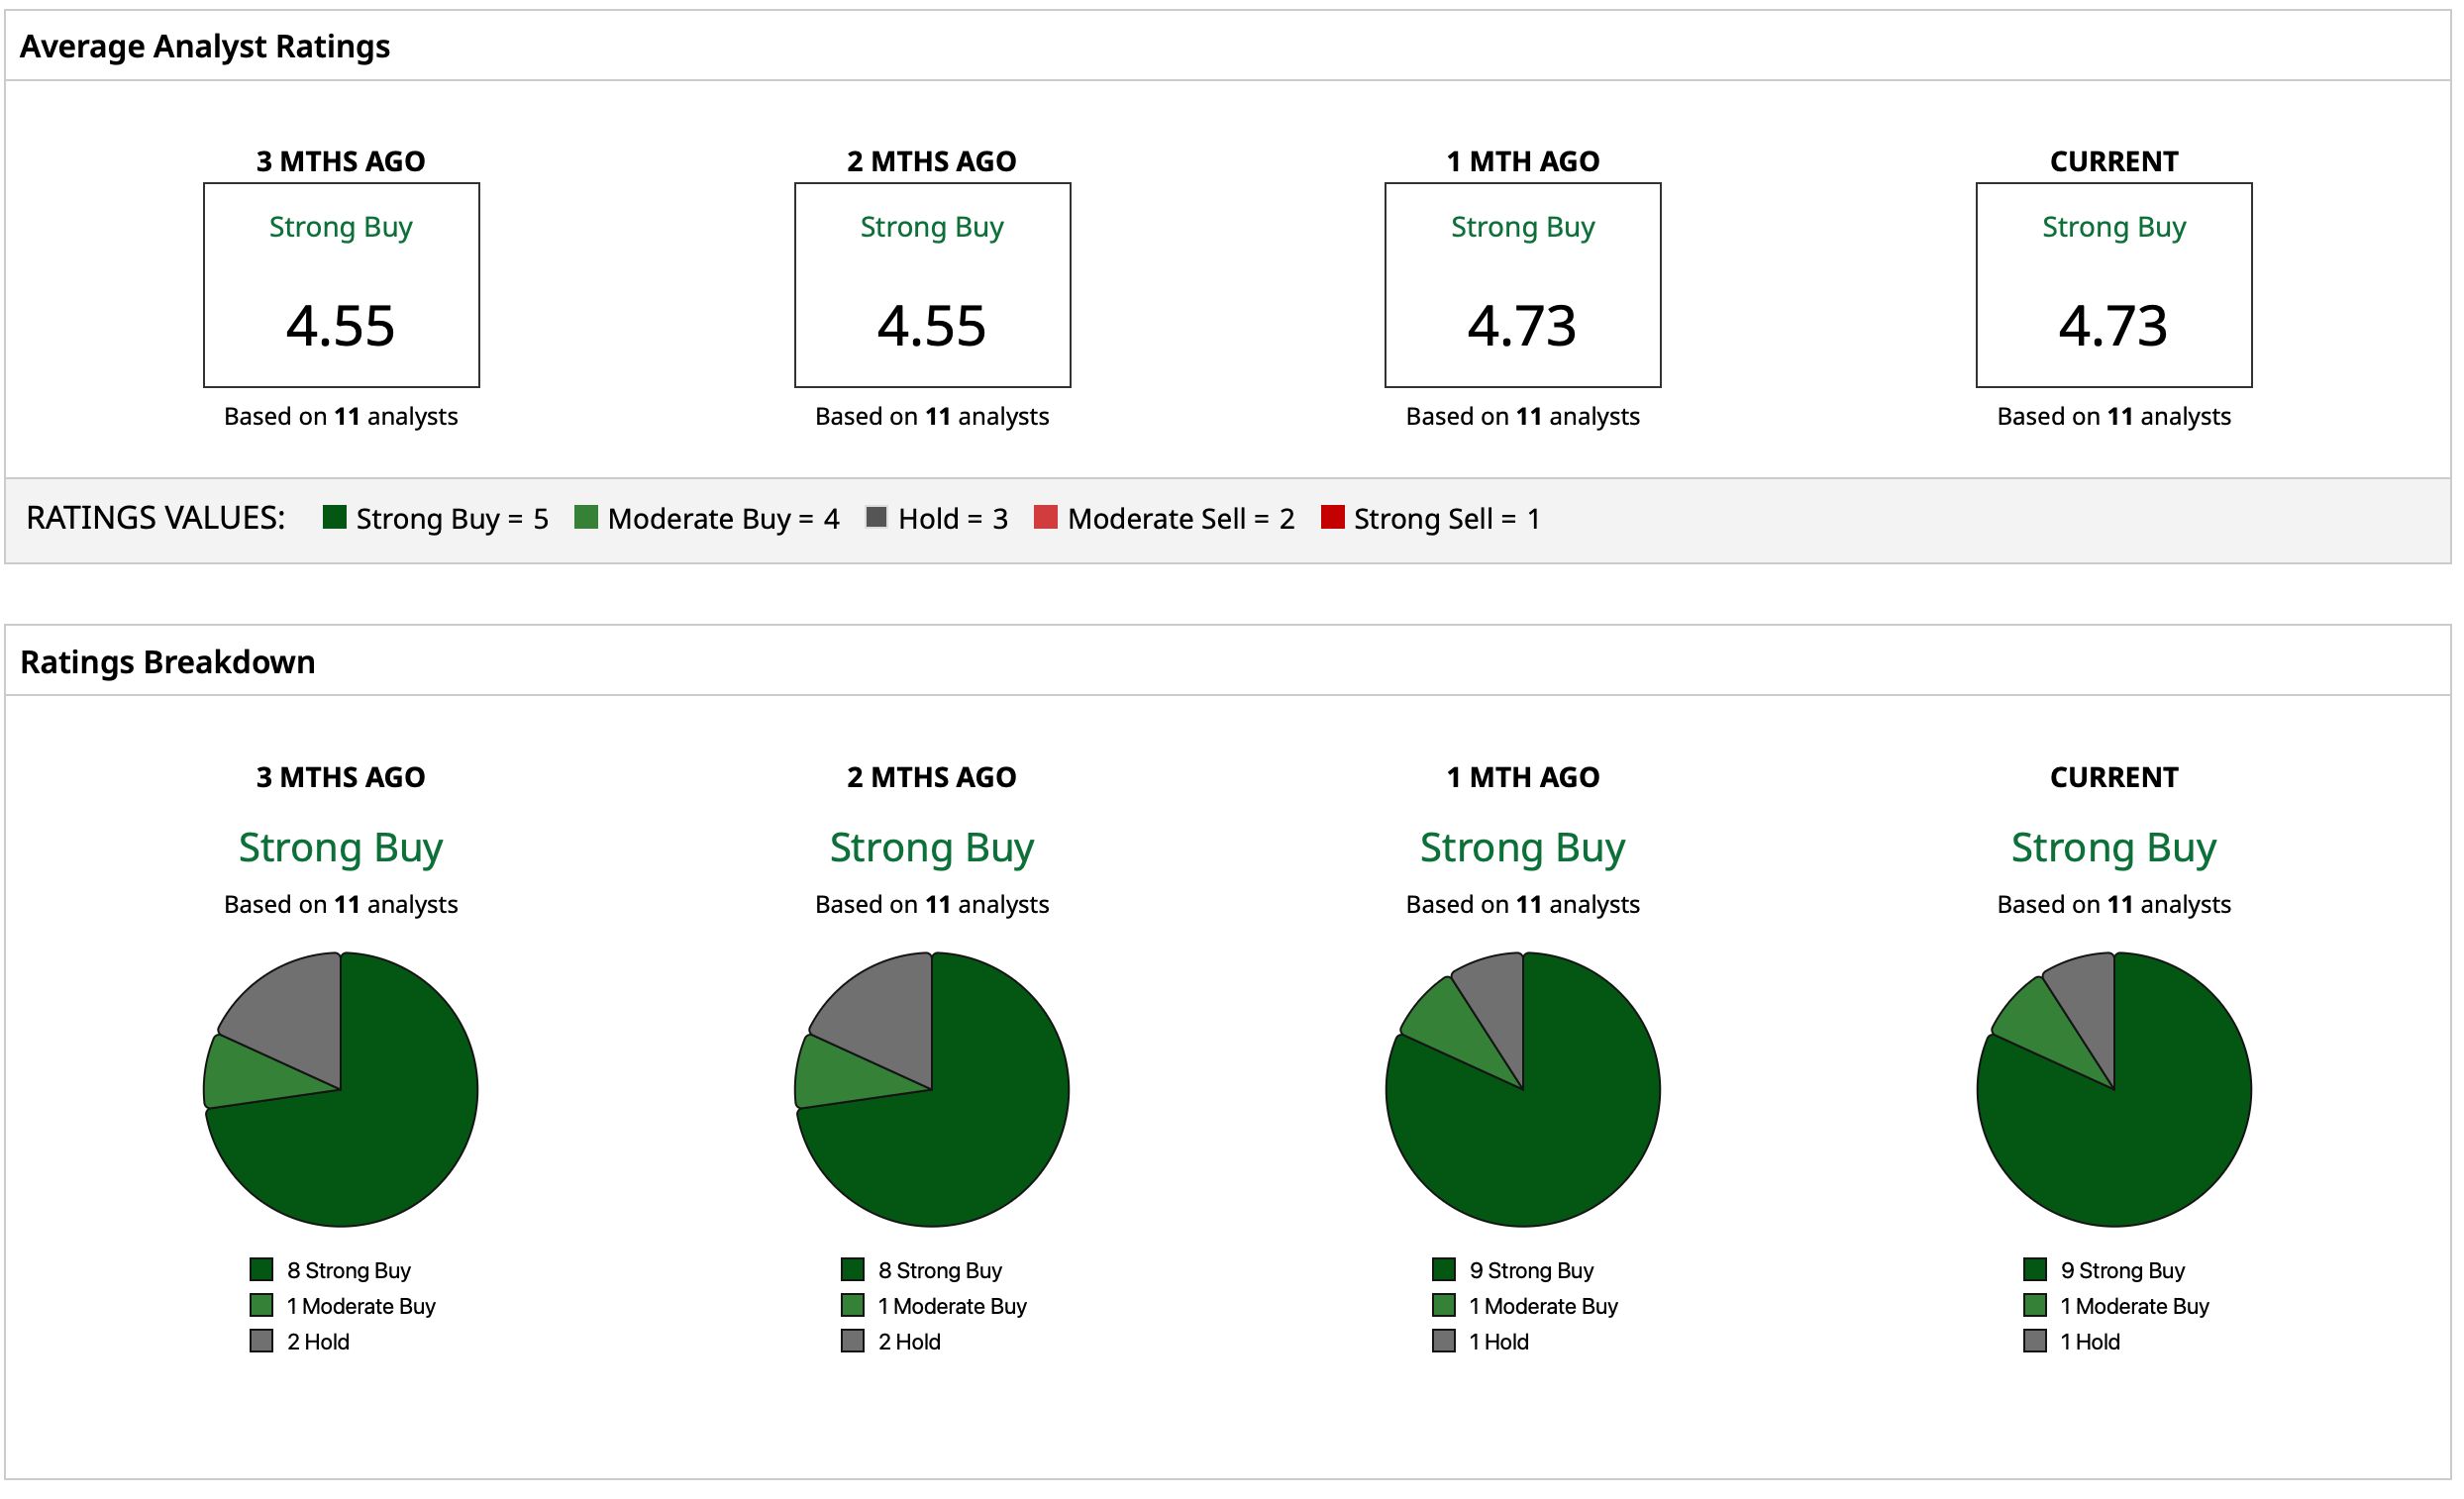
Wall Street has a consensus “Strong Buy” rating for CBRS stock. Out of 12 analysts covering the stock, 10 have a “Strong Buy” rating, one has a “Moderate Buy” rating, and one analyst has a “Hold” rating. The mean target price of $222.17 indicates potential upside of 111% from current levels.
However, some firms recently reduced their price targets for Cerebras stock. Morgan Stanley dropped its price target from $279 to $178, UBS lowered its target from $250 to $155, Needham lowered its target from $300 to $200, and Mizuho lowered its target from $300 to $240. Primary headwinds include doubts over the company's ability to bring additional data-center capacity online in a timely manner as well as customer-concentration risks.
 www.barchart.com
On the date of publication, Pathikrit Bose did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
A $3 Billion Reason Why Disney Stock Is in Focus Today A $5 Billion Reason Why Nike Stock Is in Focus Today What It Will Take for Cerebras Stock to Stage a Real Revival After Q3 Earnings Rally Micron Stock Is Down 41%, but the $35 Billion Buyback Could Change the Game. Here's How.