

Solventum Corporation (SOLV), based in Maplewood, Minnesota, is a healthcare company that develops, manufactures, and commercializes a portfolio of solutions to address critical customer and patient needs. With a market cap of $15 billion, the company’s broad portfolio of solutions leverages material and data science, clinical research, and digital capabilities. Solventum operates in separation and purification, health information, medical solutions, medical device component, and oral care market.
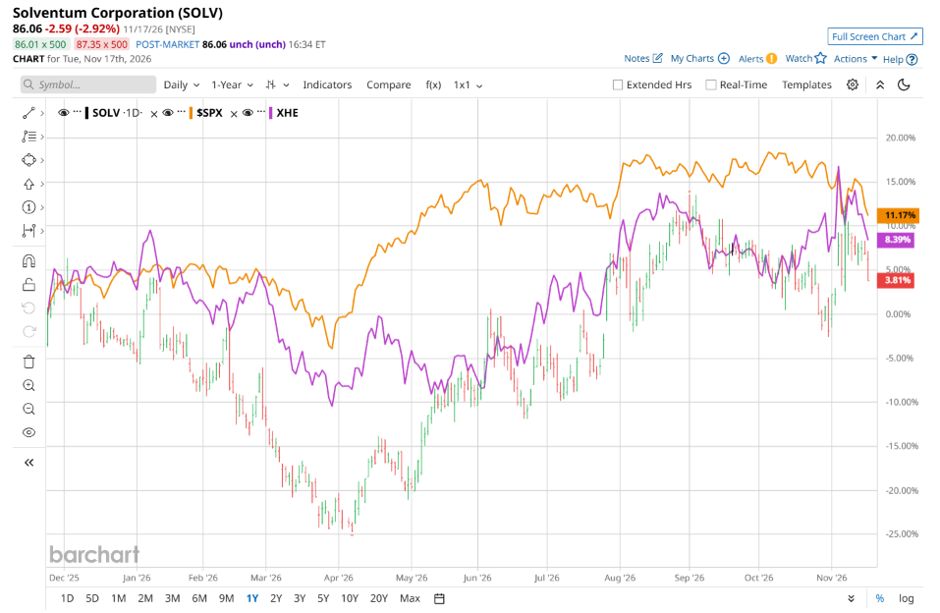
Shares of this leading global healthcare company have outperformed the broader market over the past year. SOLV has gained 13% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10%. In 2026, SOLV stock is up 8.6%, surpassing SPX’s 7.2% rise on a YTD basis.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
Narrowing the focus, SOLV’s underperformance is apparent compared to the State Street SPDR S&P Health Care Equipment ETF (XHE). The exchange-traded fund has gained about 13.5% over the past year. However, SOLV’s returns on a YTD basis outshine the ETF’s 4.6% gains over the same time frame.
 www.barchart.com
SOLV completed its largest ERP cutover to minimize customer disruption and advanced over 90% of its separation from 3M Company (MMM), significantly lowering execution risk and boosting expected free cash flow through reduced costs. Despite reported sales reflecting advanced order reversals and tariff refund headwinds, management raised its profit guidance and expressed strong confidence in next-year margin expansion driven by cost savings, a new long-term 3M supply agreement, and product ramps. Furthermore, the company is evaluating spin or sale options for its Health Information Systems business to sharpen strategic focus, while organic growth will center on core drivers like wound therapy and sterilization assurance, supported by recent innovations such as the V.A.C. Peel and Place dressing.
On Nov. 5, SOLV shares closed down by 2.4% after reporting its Q3 results. Its adjusted EPS of $1.45 surpassed Wall Street expectations of $1.35. The company’s revenue was $1.95 billion, falling short of Wall Street forecasts of $1.97 billion. SOLV expects full-year adjusted EPS in the range of $7.20 to $7.30.
For the current fiscal year, ending in December, analysts expect SOLV’s EPS to grow 18.8% to $7.26 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
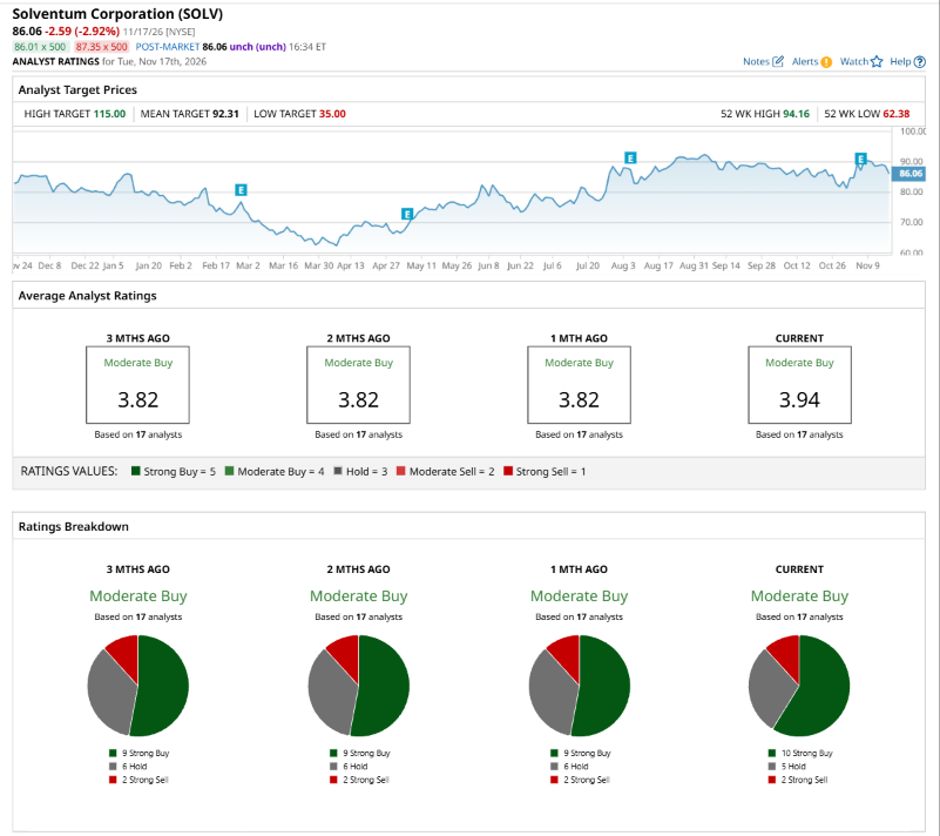
Among the 17 analysts covering SOLV stock, the consensus is a “Moderate Buy.” That’s based on 10 “Strong Buy” ratings, five “Holds,” and two “Strong Sells.”
 www.barchart.com
This configuration is more bullish than a month ago, with nine analysts suggesting a “Strong Buy.”
On Nov. 9, Patrick Wood from UBS maintained a “Buy” rating on SOLV, with a price target of $105, implying a potential upside of 22% from current levels.
The mean price target of $92.31 represents a 7.3% premium to SOLV’s current price levels. The Street-high price target of $115 suggests an ambitious upside potential of 33.6%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Realty Income vs. Agree Realty: Which REIT Wins on Dividends and Growth? Bill Gates Has Earned $2.6 Billion in Dividends From a Landfill Stock the EPA Keeps Citing for Methane Leaks, and a Filing Shows He Just Bought 3.7M More Shares Amazon Is Building a Massive Shopping Data Repository to Compete With AI Agents. Shareholders Should Welcome the Move. Applied Materials Reports Another Double Beat in Q4. AMAT Stock Could Gain 66% From Here.