

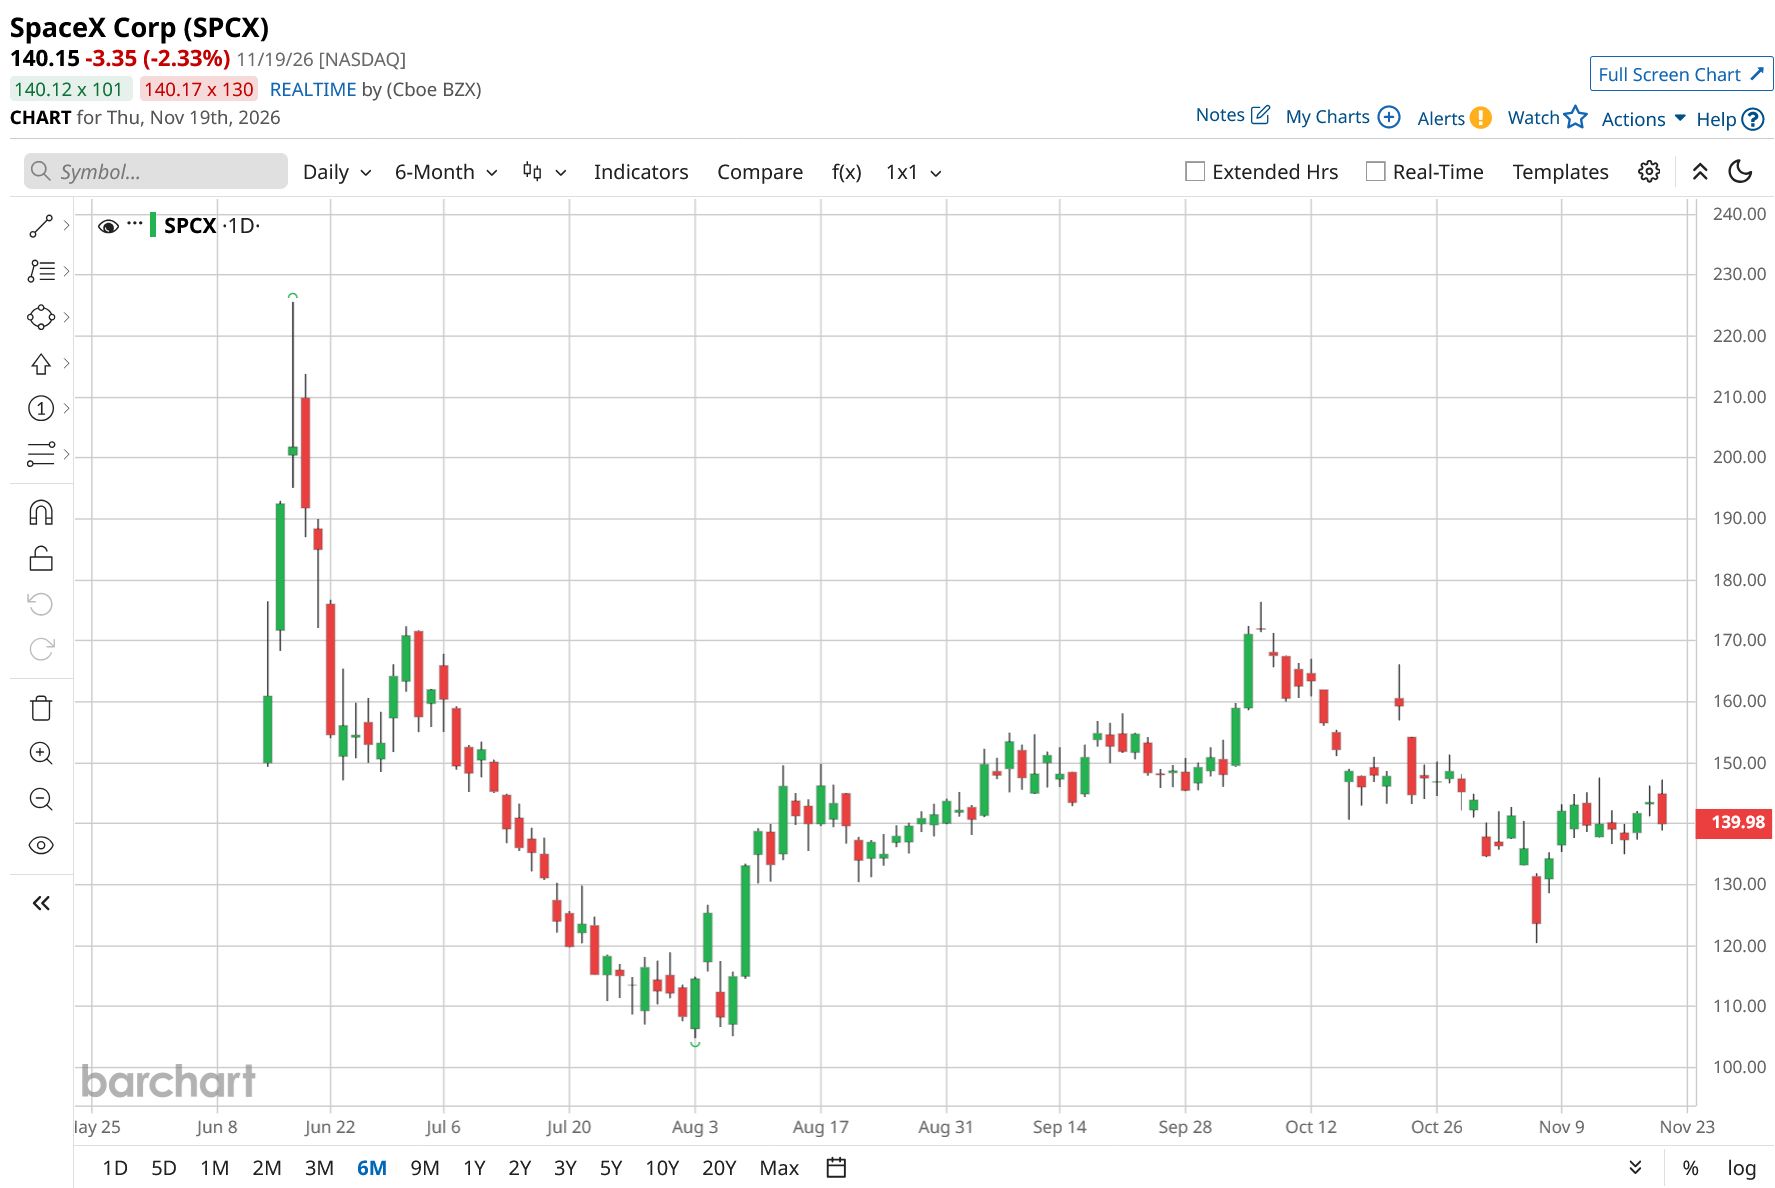
Shares of Elon Musk-led Space Exploration Technologies (SPCX), better known as SpaceX, have fallen nearly 36.4% from their post-IPO peak as the excitement surrounding its market debut gradually lost steam. The aerospace and artificial intelligence (AI) giant priced its IPO at $135 on June 11, before climbing to an all-time post-listing high of $225.64 on June 16. SPCX's current price of about $140 puts it down nearly 40% from that high.
The retreat came amid a combination of profit-taking, stretched valuation multiples, a limited pipeline of near-term catalysts, and mounting concerns about hefty AI infrastructure spending. Yet Nvidia’s (NVDA) recently released Q3 Form 13F filing has put the space and technology heavyweight in focus.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
The chipmaker increased its SpaceX holdings by 7.71 million shares, or 6.3%, during Q3. As of Sept. 30, Nvidia held 130.5 million SpaceX shares, up from 122.8 million at the end of June. The addition stands out because the rocket manufacturer was the only company among the eight holdings in Nvidia's $48.3 billion portfolio to receive additional shares during the quarter.
The semiconductor giant took a markedly different approach with rival Intel (INTC), cutting its position by 25% after selling 53.7 million shares. This portfolio reshuffle erased Intel's $9 billion lead from Q2 and pushed SpaceX into the top spot among Nvidia's stock holdings. At quarter-end, the latter position was valued at $19.7 billion, edging past Intel's $19.4 billion.
A closer look at SpaceX's business fundamentals helps put this shift into perspective.
About SpaceX Stock
Based in Starbase, Texas, SpaceX develops and launches reusable rockets and spacecraft while providing satellite-powered broadband services. With a market cap of nearly $1.9 trillion, its operations span commercial launch services, the Starlink global internet network, and a growing AI business encompassing Grok, enterprise solutions, and computational infrastructure.
Although SPCX stock has posted marginal gains over the past three months, its performance has been less encouraging recently, with the stock losing 6% over the past month. A sustained recovery has yet to materialize, and the shares are essentially flat over the last five trading sessions.
Several developments helped support the stock's price stability, including a roughly $40 billion AI-chip financing plan, Nvidia's expanded stake, and robust Q3 growth. The latest momentum also reflects a reported computing agreement with Anthropic (ANT), Elon Musk's projection of $500 billion in annualized revenue for 2027, and continued strength across Starlink's expanding operations.
 www.barchart.com
Despite the improving share-price momentum, valuation remains difficult to overlook. SPCX stock is currently trading at 910.61 times forward-adjusted earnings and 39.27 times sales. Both multiples sit considerably above their respective industry averages, highlighting the substantial premium attached to the business.
Q3 Earnings Beat Expectations
On Oct. 20, the aerospace and AI pioneer released its Q3 FY2026 earnings, reporting a sharp acceleration in revenue and profitability. Shares responded positively, climbing 7.9% in the following trading session.
Total revenue surged 161.4% year-over-year (YoY) to $14.6 billion, reflecting the growing contribution of AI infrastructure and software alongside Starlink's steadily expanding subscriber base. The figure also topped Street’s expectations of $12.54 billion.
Super Intelligence (SI) emerged as the strongest growth engine, generating $7.6 billion in revenue compared with $813 million previously. Its performance benefited from cloud services agreements, increased computing capacity, and the acquisition of Cursor.
Connectivity delivered a strong quarter, with revenue increasing 69.5% YoY to $5.2 billion. Growth was supported by a 91% YoY increase in enterprise and government demand, alongside continued expansion of Starlink's consumer business, which added 1.6 million subscribers in Q3 to reach a total customer base of 13.6 million.
The Space segment, however, delivered a more subdued performance, with revenue increasing just 6.1% YoY to $1.8 billion despite a favorable customer mix. During the quarter, the launch business completed 35 missions, including 21 Starlink launches and two Starship flights, maintaining a busy operational schedule.
At the consolidated level, adjusted EBITDA jumped 306.1% YoY to $8.8 billion. Net income swung to $4.4 billion, reversing the $1.1 billion loss recorded in the corresponding period a year earlier. EPS followed the same trajectory, reaching $0.35 compared with a loss per share of $0.36 in the prior-year period. It also topped Street’s forecast of $0.10.
Capex reached $19.6 billion in Q3. Management's forward guidance suggests that the investment cycle is far from over. Q4 capex is expected to reach $35 billion–$40 billion, while Q1 FY2027 revenue is projected at $33 billion–$37 billion.
On the other hand, analysts project Q4 FY2026 EPS to decline 100% YoY to $0.31. For the full year FY2026, the bottom line is expected to fall 100% from the previous year to $0.22 before rebounding 1,759.1% from the previous year to $4.09 in FY2027.
What Do Analysts Expect for SPCX Stock?
Analysts are broadly optimistic. Colin Canfield of Cantor Fitzgerald has rated SPCX stock a “Buy,” with a price target of $345, while Doug Anmuth of J.P. Morgan also maintains a “Buy” rating and a $500 target.
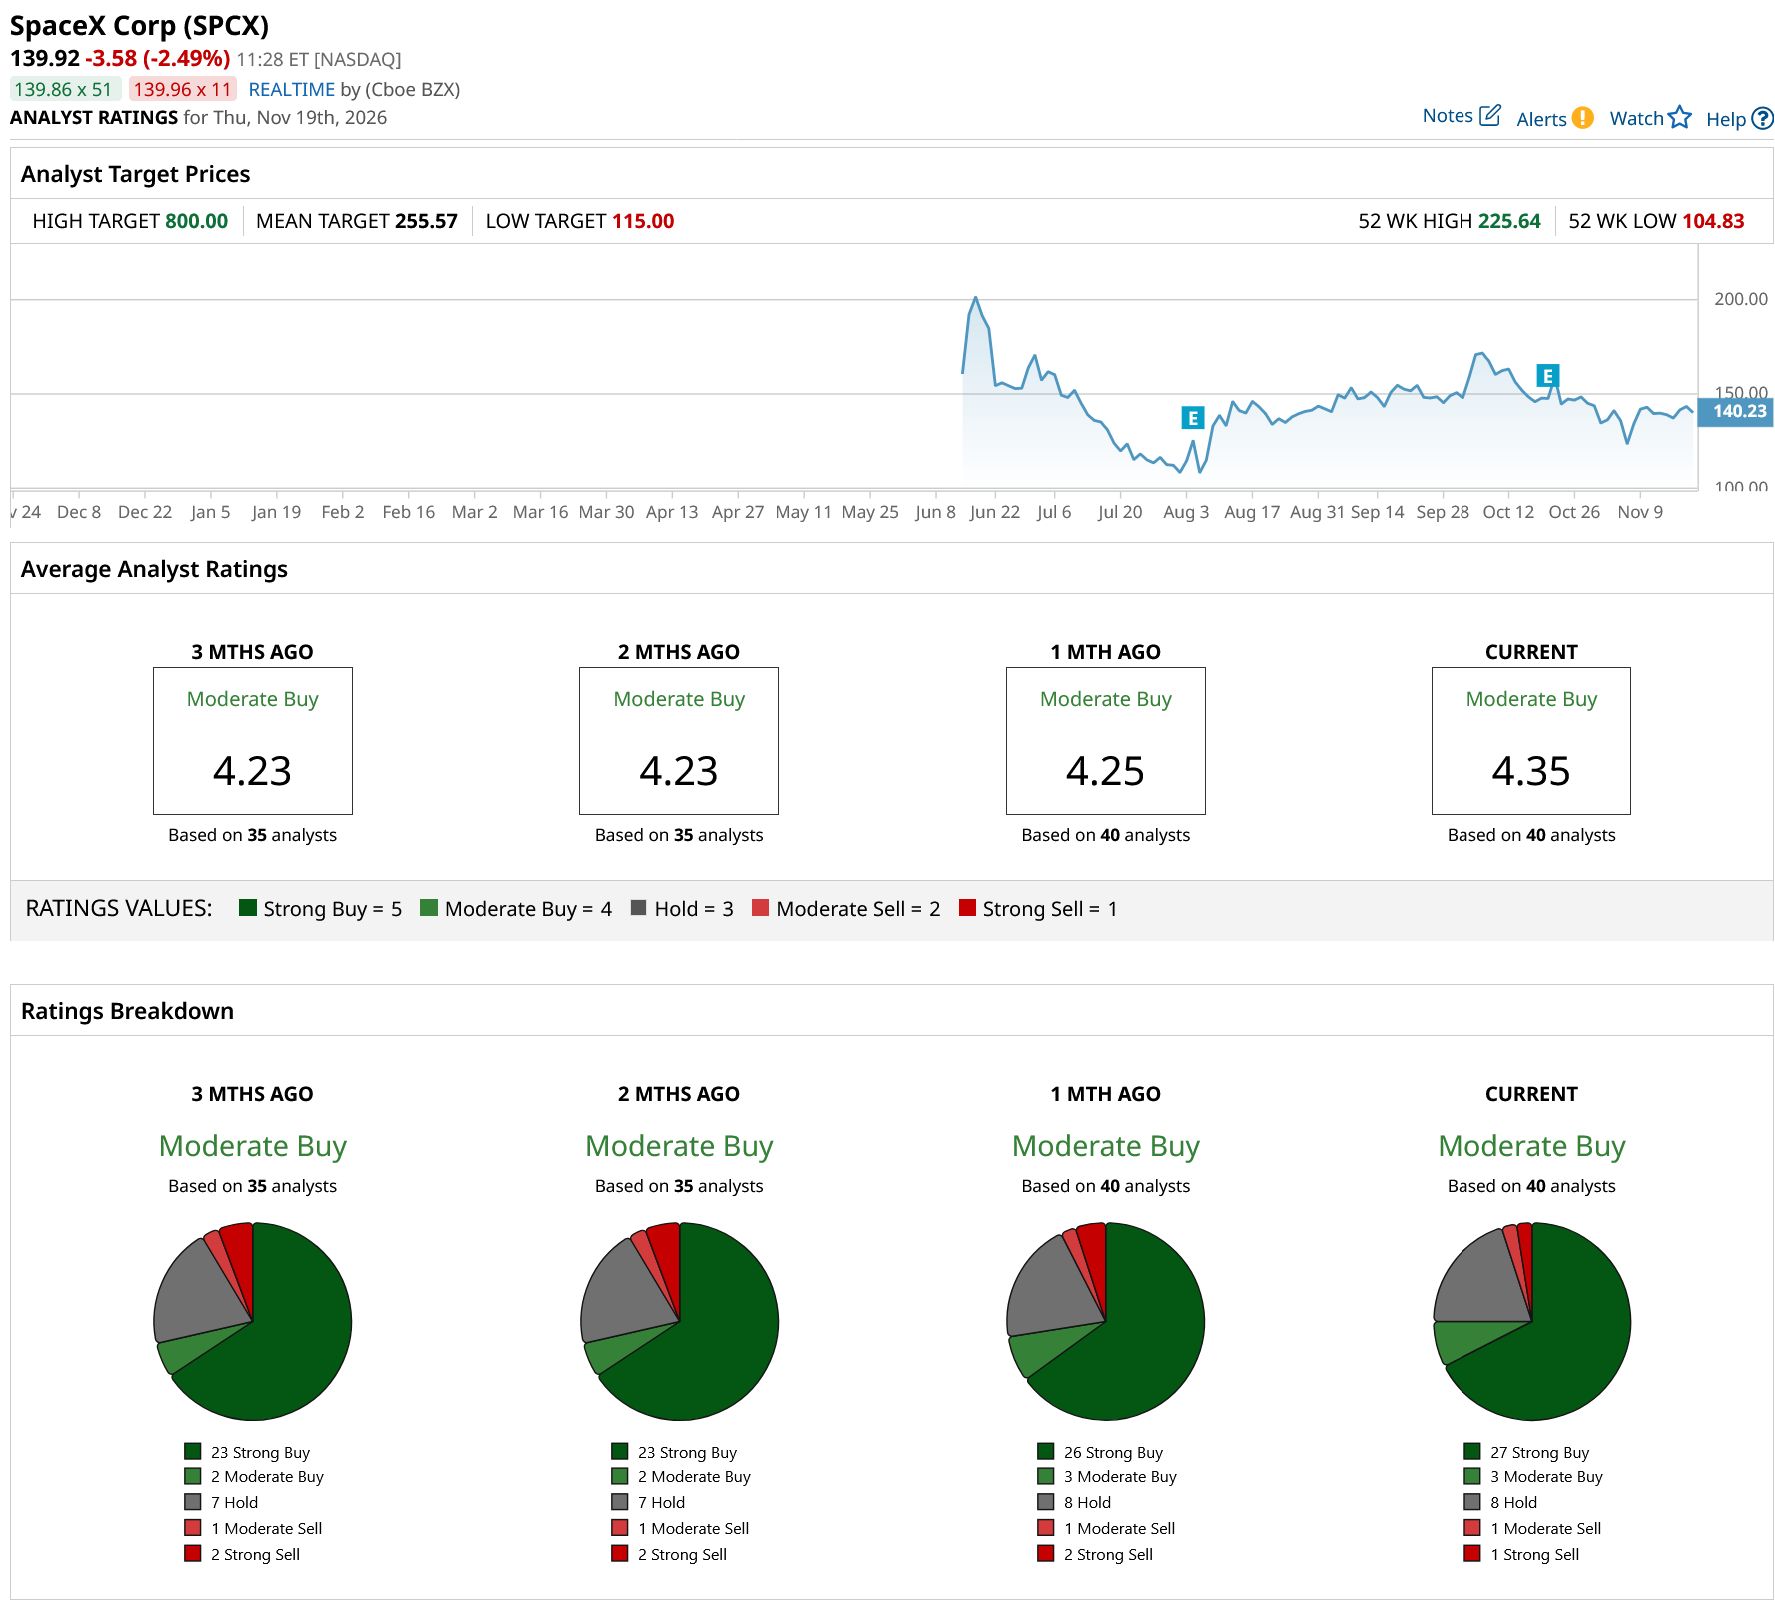
Across the wider analyst community, the stock carries an overall “Moderate Buy” rating. Of 40 analysts covering SPCX stock, 27 recommend a “Strong Buy” and three assign a “Moderate Buy.” Another eight maintain a “Hold” rating, one suggests a “Moderate Buy,” and one has issued a “Strong Sell” recommendation.
The average price target for SPCX stock stands at $255.57, indicating potential upside of 83% from current levels. At the more optimistic end of the forecast range, Brian Gesuale of Raymond James has set a Street-high target of $800, implying potential gains of 471% from the prevailing share price.
 www.barchart.com
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
George Soros’s Fund Doubled Down on Micron Stock in Q3. The Bull Case Is Hard to Ignore. Barchart Experts ‘See’ an Opportunity with This Hot Stock at 2-Year Highs SpaceX Stock Is Down Nearly 40% from Its Post-IPO Highs but Nvidia Is Still Loading Up Nvidia Could Poach Arm's CEO to Replace Jensen Huang. Here's What That Might Mean for ARM Stock.