

Institutional capital is increasingly rotating toward specialized memory chipmakers as high-bandwidth memory emerges as a critical bottleneck in artificial intelligence infrastructure. With hyperscalers racing to secure next-generation stacked DRAM capacity for data center accelerators, top technology-focused hedge funds are positioning early to capture surging pricing power and multi-year supply visibility.
Underscoring this institutional conviction in AI memory leaders, Philippe Laffont's Coatue Management initiated a new position in South Korean semiconductor giant SK hynix (SKHY) during the third quarter.
More Top Stocks Daily: Go behind Wall Street’s hottest headlines with Barchart’s Active Investor newsletter.
About SK hynix
SK hynix is a South Korean semiconductor manufacturer specializing in dynamic random-access memory (DRAM), NAND flash memory, and high-bandwidth memory (HBM). Its products power smartphones, computers, servers, and advanced data centers, positioning the company as a major beneficiary of the global artificial intelligence (AI) infrastructure boom.
SK hynix Stock Outperforms Market
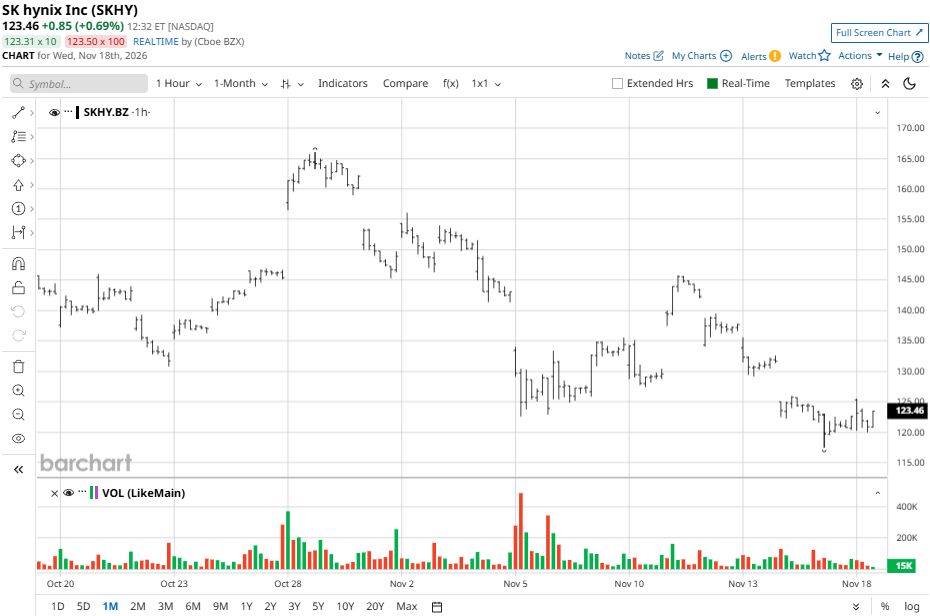
SK hynix shares have experienced significant volatility in 2026, supported by surging demand for AI chips and high-bandwidth memory. The company's stock has more than doubled this year, although it has retreated substantially from its record high reached in June. Investor optimism surrounding AI infrastructure spending, rising memory prices, and SK hynix's leading position in the HBM market has supported its longer-term performance.
The Nasdaq Composite ($NASX) has remained positive in 2026, gaining approximately 4.7% year-to-date (YTD) through Nov. 17. SK hynix's South Korean shares have delivered considerably stronger gains over the same broad period, despite a sharp pullback from their June peak.
 www.barchart.com
Q3 Results Shine
SK hynix reported record third-quarter 2026 revenue of 104.62 trillion won, representing a 328% increase from the same period last year and surpassing the 100 trillion won milestone for the first time. Operating profit surged more than sevenfold year over year to 83.33 trillion won, exceeding the LSEG SmartEstimate of 76.7 trillion won. Net income reached 39.78 trillion won, reflecting the exceptional profitability generated by strong AI memory demand and higher semiconductor prices. Revenue and operating profit also increased 32% and 38%, respectively, from the previous quarter.
The company's financial position strengthened alongside its earnings growth. Operating margin reached 80%, while net margin stood at 38%, highlighting the profitability of its high-value-added memory products. Cash and cash equivalents climbed to 114.5 trillion won, while borrowings declined to 15.8 trillion won, leaving SK hynix with a net cash of 98.7 trillion won. Growth was supported by increased server DDR5 sales, expanding HBM4 shipments, and stronger demand for 321-layer NAND enterprise solid-state drives (eSSDs). The company also announced plans for approximately 100 trillion won in shareholder returns during 2026, including dividends and share repurchases.
Looking ahead, management expects the AI infrastructure boom to sustain memory demand, with supply constraints potentially extending through 2030. SK hynix said its HBM and DRAM production capacity is effectively sold out through 2029, while demand for HBM is approximately twice its available supply. The company has secured long-term agreements covering more than 50% of its production capacity for 2027 and 2028.
Coatue Management Takes New Stake in SK hynix
Coatue Management, the technology-focused investment firm founded by Philippe Laffont, established a new position in SK hynix during the third quarter, according to its latest 13F filing with the U.S. Securities and Exchange Commission. The investment adds SK hynix to Coatue’s portfolio as demand for high-bandwidth memory (HBM) and AI-related semiconductors continues to reshape the global chip industry.
The fund also initiated new positions in Salesforce (CRM), Shopify (SHOP), Intercontinental Exchange (ICE), and Visa (V), while increasing its holdings in Meta Platforms (META), Nvidia (NVDA), Microsoft (MSFT), Intel (INTC), and Equinix (EQIX). Although the filing does not disclose Coatue’s investment rationale, the addition of SK hynix highlights the stock’s growing presence among institutional investors seeking exposure to the expanding AI infrastructure and advanced memory markets.
Should You Buy SKHY Stock?
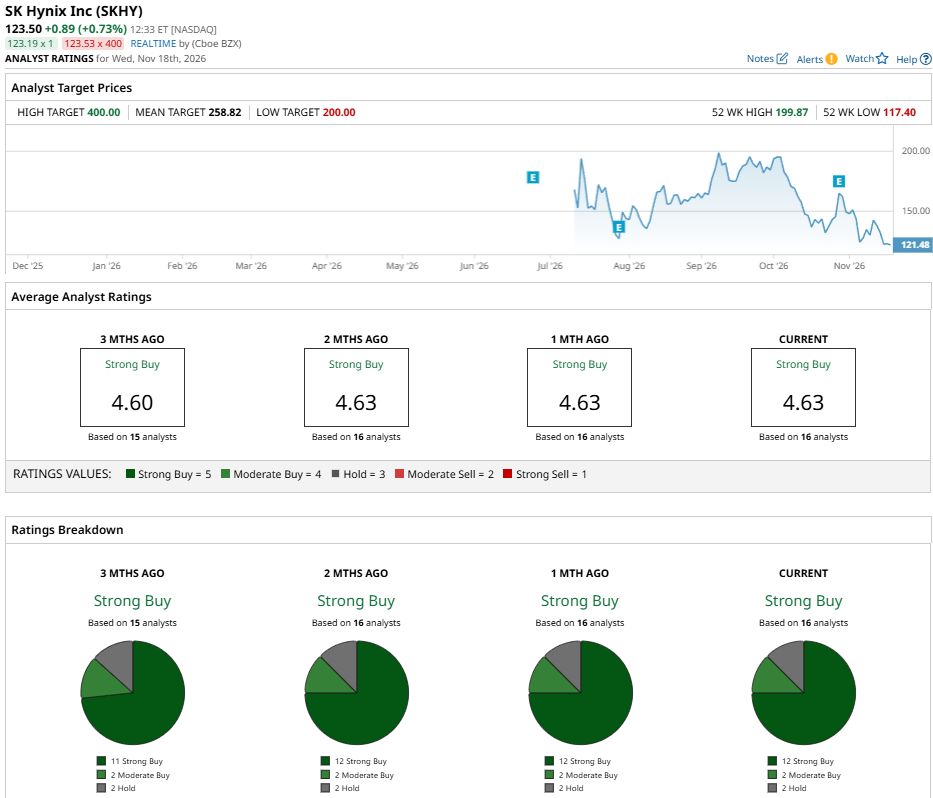
Coatue Management’s decision to establish a new position in SK hynix during the third quarter adds to the growing institutional interest in the semiconductor company as AI infrastructure spending fuels demand for high-bandwidth memory. This investment activity, combined with SK hynix’s expanding role in the AI chip supply chain, strengthens its long-term growth narrative. Wall Street analysts remain optimistic, assigning SKHY a “Strong Buy” consensus rating and a mean price target of $258.82, implying approximately 116% upside from its current price. Of the 16 analyst ratings, 12 give it a “Strong Buy,” two a “Moderate Buy,” and two a “Hold” rating.
 www.barchart.com
On the date of publication, Ruchi Gupta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
More news from Barchart
Coatue Management Bets on SK hynix Stock as Demand for HBM Chips Accelerates TD Cowen Just Upgraded UnitedHealth Stock. Here’s Why. Apple Is Now Worth Over $5 Trillion Without Betting Big on AI Data Centers. AAPL Stock Now Trades Near Wall Street’s Targets. 2 ETFs to Consider in a Market Where Nearly All Stocks Look Dangerous