

Micron Technology, Inc. MU is making aggressive investments to expand memory production as artificial intelligence (AI) drives demand for high-performance DRAM, high-bandwidth memory (HBM) and storage. The manufacturing push could help Micron capture more of this growth, provided the company can add capacity without creating excess supply.
Micron invested $7.1 billion in capital expenditures in the third quarter of fiscal 2026 and expects capital spending of about $27 billion for the full fiscal year. The company is expanding leading-edge DRAM production in Idaho and New York while also increasing its advanced packaging capacity in Singapore.
These investments come as Micron's business is growing rapidly. Its third-quarter revenues surged 346% year over year to $41.46 billion, while non-GAAP earnings reached $25.11 per share, up sharply from $1.91 a year ago. Its Cloud Memory Business Unit and Core Data Center Business Unit’s revenues jumped 307% and 653%, respectively, showing how quickly AI-related demand is rising.
The timing of capacity expansion is important. Micron expects its first Idaho fab to begin wafer output in mid-2027, with the second targeted for late 2028. The first New York fab is expected to supply memory from 2030 onward. Singapore is also anticipated to add meaningful HBM packaging capacity in the first half of 2027.
These investments should give Micron more capacity to serve AI customers as memory demand rises. However, the company must balance expansion with market conditions because adding capacity too quickly could pressure pricing. For now, strong AI demand and supply constraints provide a favorable backdrop. If Micron executes its manufacturing plans well, the expansion could help MU capture a larger share of the AI memory opportunity.
SK Hynix and Sandisk: Micron’s Rivals in the AI Memory Race
Micron faces strong competition from SK hynix Inc. SKHY and Sandisk Corporation SNDK.
SK hynix is a major threat in HBM, a key component of AI accelerators. In the second quarter of 2026, SK hynix’s revenues surged 257% year over year to 79.32 trillion Korean won, and operating profit jumped 557% to 60.54 trillion won. Operating margin reached 76%, up from 41% in the year-ago quarter. In its second-quarter results, SK hynix revealed that it has begun mass shipments of HBM4 and plans to expand production capacity to meet AI-driven demand.
The company is investing aggressively to enhance its manufacturing capacity. In early August 2026, SK hynix announced that it will invest roughly 54 trillion KRW ($38 billion) to expand its domestic memory chip manufacturing in South Korea alongside a new $4 billion packaging plant in the United States.
Sandisk is a more direct competitor to Micron in NAND and data center storage. Its fourth-quarter fiscal 2026 revenues jumped nearly 372% year over year to $8.97 billion, while data center revenues surged approximately 1,300% to $2.98 billion. In late August 2026, Sandisk and its manufacturing partner Kioxia announced a joint investment of more than $31 billion in Japan through 2032 to expand flash memory production for artificial intelligence and data centers.
Aggressive investment plans of SK hynix and Sandisk show that Micron must keep investing in both AI memory and storage to strengthen its position.
Micron’s Price Performance, Valuation and Estimates
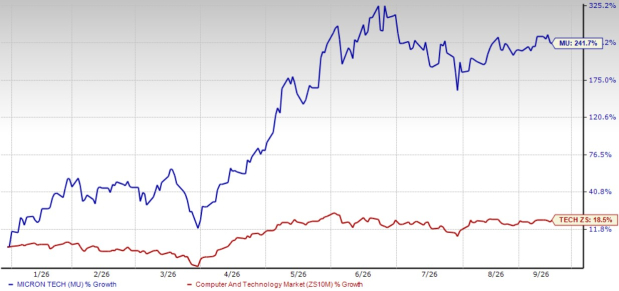
Shares of Micron have surged around 241.7% year to date compared with the Zacks Computer and Technology sector’s return of 18.5%.
Micron Technology YTD Price Return Performance
Image Source: Zacks Investment Research
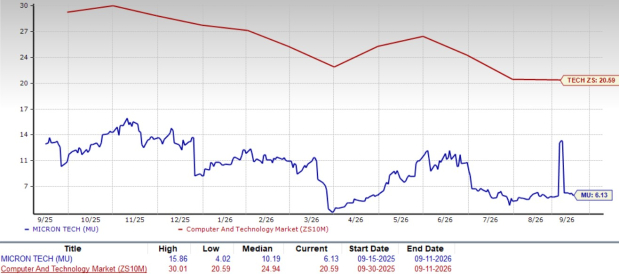
From a valuation standpoint, MU trades at a forward price-to-earnings ratio of 6.13, significantly lower than the sector’s average of 20.59.
Micron Technology 12-Month Forward P/E Ratio
Image Source: Zacks Investment Research
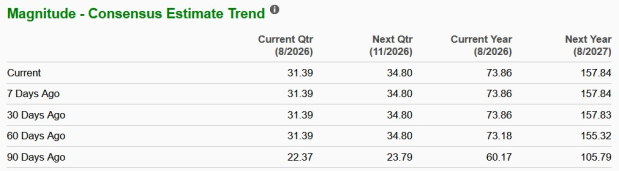
The Zacks Consensus Estimate for Micron’s fiscal 2026 and 2027 earnings implies a year-over-year increase of 791% and 113.7%, respectively. Bottom-line estimates for fiscal 2026 have been revised upward over the past 60 days, while for fiscal 2027, estimates have been revised upward over the past 30 days.
Image Source: Zacks Investment Research
Micron currently carries a Zacks Rank #2 (Buy). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Micron Technology, Inc. (MU): Free Stock Analysis Report
Sandisk Corporation (SNDK): Free Stock Analysis Report
SK Hynix, Inc. - Sponsored ADR (SKHY): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).