

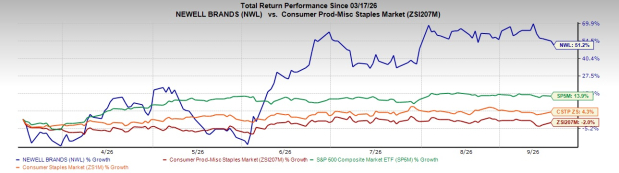
Newell Brands Inc. NWL has delivered a strong stock-market performance in recent months as investors have gained confidence in its ongoing turnaround. The company’s shares have rallied 51.2% over the past six months, comfortably outperforming the S&P 500 index, which gained 13.9% during the same period and the Consumer Staples sector’s growth of 4.3%. Meanwhile, the broader Consumer Products – Staples industry fell 2%.
The recent rally reflects improving operating trends, stronger innovation, better retail execution and a return to sales growth. Newell reported year-over-year growth in both net sales and core sales in the second quarter of 2026 for the first time in more than four years. The company also raised its 2026 outlook across sales, margins, normalized earnings per share (EPS) and operating cash flow.
Image Source: Zacks Investment Research
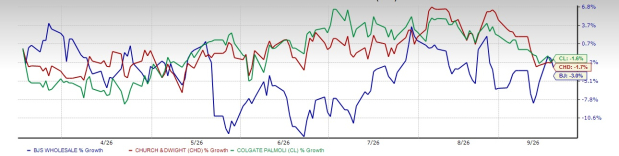
NWL’s performance is notably stronger than that of its competitors, BJ's Wholesale Club BJ, Colgate-Palmolive Company CL and Church & Dwight Co., Inc. CHD, which declined 3%, 1.6% and 1.7%, respectively, in the past six months.
Image Source: Zacks Investment Research
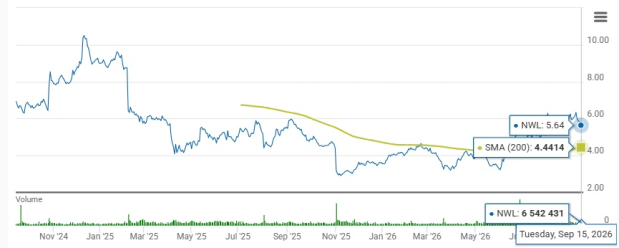
Closing at $5.64, NWL stock stands almost 21% below its 52-week high of $7.13, attained on July 31, 2026. The company is trading above its 200-day simple moving average of 4.44, indicating that the stock’s recent recovery remains intact despite its pullback from the 52-week high.
Image Source: Zacks Investment Research
What’s Fueling Newell’s Recent Stock Rally?
Newell’s second-quarter 2026 results provided a significant boost to investor sentiment. Net sales increased 3% year over year to approximately $2 billion, while core sales grew 2.3%, marking the company’s first year-over-year growth in both measures in more than four years. Normalized EPS rose to 42 cents from 24 cents a year ago and exceeded the Zacks Consensus Estimate of 19 cents.
The improvement was broad-based. Learning & Development generated 4.9% core sales growth, led by strength in Baby and a return to growth in Writing. Outdoor & Recreation delivered 3.7% core sales growth, while Home & Commercial Solutions remained under pressure but improved sequentially. Graco, Sharpie, EXPO and Coleman were among the brands benefiting from stronger innovation, distribution gains and improved retail execution.
Newell also raised its 2026 outlook. The company now expects net sales growth of 1-2%, core sales growth of 0-1%, normalized operating margin of 10-10.4% and normalized EPS of $0.73-$0.77, compared with its previous EPS outlook of $0.56-$0.60. Operating cash flow is expected to be around $400 million.
Newell’s improving fundamentals are being supported by strength in key brands such as Graco, Sharpie, Coleman and Oster, while distribution gains and increased advertising and promotional support are helping improve consumer engagement. At the same time, the company continues to face inflation, transportation costs and elevated debt levels, which could limit the pace of its recovery.
Are Newell’s Strategic Efforts Paying Off?
Newell’s strategic initiatives are showing signs of progress as it focuses on rebuilding its brands, improving innovation and strengthening retail execution. Management has emphasized a capability-based turnaround centered on consumer insights, product innovation, advertising and promotion, distribution expansion and better go-to-market execution.
Innovation has become an important growth driver. Newell expects to launch more than 25 Tier 1 and Tier 2 innovations during 2026, while six business units launched key products during the first half. Graco’s rotating car-seat platforms, Sharpie writing products and Coleman outdoor offerings are examples of the company’s efforts to strengthen its major brands.
The company is also benefiting from distribution gains. Six of its top 10 brands delivered year-over-year point-of-sale growth in the second quarter, while eight improved their growth trajectory sequentially. Graco gained 2.7 percentage points of U.S. market share year to date, while the U.S. business recorded 5% net sales growth.
Productivity and cost control remain another key component of the turnaround. In the second quarter, stronger sales, gross productivity and disciplined overhead management helped offset higher commodity and transportation costs. However, Newell expects approximately $200 million of inflationary pressure for 2026, highlighting the need for continued productivity gains and cost discipline.
Overall, Newell’s strategy is producing measurable improvements in sales, margins, distribution and brand momentum. However, investors should distinguish between improvements from underlying operations and the benefit from tariff recoveries. The second-quarter results included approximately $126 million of pretax tariff recoveries, equivalent to about 21 cents per share, making the sustainability of underlying earnings growth an important consideration.
How Have Estimates Shaped Up for NWL?
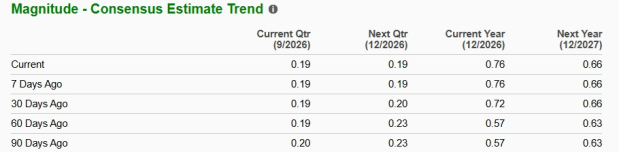
Following Newell’s stronger-than-expected second-quarter results and raised guidance, analysts have increased their earnings expectations. The Zacks Consensus Estimate for Newell’s 2026 EPS had increased by 19 cents to 76 cents in the past 60 days, with several analysts revising their estimates higher.
Image Source: Zacks Investment Research
How to Play Newell Stock Now?
Newell’s recent performance highlights meaningful progress in its turnaround, with sales returning to growth, margins improving and management raising its full-year outlook. Stronger innovation, distribution gains and improved execution across brands such as Graco, Sharpie and Coleman provide important support for the company’s growth strategy.
The stock’s recent appreciation means investors may want to closely monitor the sustainability of underlying sales and earnings growth, particularly as tariff-related benefits roll off and inflationary pressures remain elevated.
The key factors to watch going forward include the durability of core sales growth, continued market-share gains, the success of new product launches, productivity savings and the company’s ability to offset inflation and transportation costs. These factors will help determine whether the recent improvement represents a sustained turnaround or an early stage of recovery. NWL carries a Zacks Rank #3 (Hold).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Newell Brands Inc. (NWL): Free Stock Analysis Report
Colgate-Palmolive Company (CL): Free Stock Analysis Report
BJ's Wholesale Club Holdings, Inc. (BJ): Free Stock Analysis Report
Church & Dwight Co., Inc. (CHD): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).