

Wix.com Ltd. WIX is focused on lowering AI-related costs in 2026 by developing and deploying its own large language models (LLMs), with the company expecting these efforts to improve its margin profile in the second half of the year. On the last earnings call, management stated that lowering inference costs with proprietary LLMs was a company-wide priority for 2026. Wix launched its Harmony model earlier in the year and followed it with Base1 in June, a proprietary model developed for BASE44. According to management, bringing the model in-house provides tighter control over quality, faster iteration cycles and a better long-term cost structure.
Base1 is already producing tangible cost benefits for BASE44. As more inference shifts to the company’s own model and additional cost optimization efforts continue, Wix expects AI-related costs to decline across both free and paid users. As a result, the company projects BASE44’s non-GAAP gross margin to reach approximately 60% in the second half of 2026 compared with nearly 0% entering the year. On the last earnings call, management highlighted that the improvement reflects BASE44 moving beyond its early-stage hypergrowth economics toward a more sustainable margin profile.
Wix’s consolidated margins are also expected to benefit. The company anticipates that the cost savings will result in approximately two percentage points of total non-GAAP gross margin improvement in the second half of 2026 compared with the first half. In the second quarter, total non-GAAP gross margin was 67%, down three percentage points year over year, primarily due to elevated BASE44 investments and higher AI compute costs as the business scaled.
However, Wix plans to reinvest the entire gross margin savings into BASE44 sales and marketing to capture strong demand and additional market share. The company expects third- and fourth-quarter sales and marketing expenses to remain elevated. At the same time, lower AI costs and reduced core Wix marketing expenses are expected to offset the increased BASE44 investment. Wix therefore continues to expect its consolidated non-GAAP operating margin to improve in the second half of 2026, supporting its full-year free cash flow outlook.
Taking a Look at WIX’s Competitors
Shopify Inc. SHOP is gaining from broad merchant gains, deeper payments adoption and expansion across online, offline and B2B channels. AI tools are becoming a larger part of merchant discovery and operations, while Catalog, Sidekick and agentic integrations extend Shopify into emerging commerce surfaces. International localization and enterprise wins add runway, and rising free cash flow margins show that investment is being funded with greater operating discipline. Management’s third-quarter outlook points to continued revenue growth and further expense leverage. For the third quarter of 2026, Shopify expects revenue growth in the low-30% range. Gross profit dollars are projected to increase in the mid-to-high-20% range.
GoDaddy Inc. GDDY is sustaining steady demand as higher-value customers adopt more products and Airo becomes a larger part of the platform experience. Applications & Commerce continues to outgrow Core Platform, while pricing, bundling and AI-led productivity support margin expansion and cash generation. Airo’s rapid adoption, broader integration and growing role across identity, presence and commerce strengthen the long-term cross-sell opportunity. International growth and disciplined capital returns add support. For the third quarter of 2026, GoDaddy expects revenues between $1.32 billion and $1.34 billion. The midpoint implies year-over-year growth of 5%, reflecting a difficult comparison with strong prior-year aftermarket activity.
WIX’s Price Performance, Valuation & Estimates
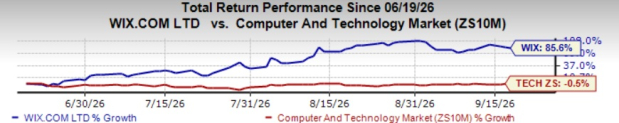
Shares of WIX have gained 85.6% in the past three months, outperforming the Zacks Computer and Technology sector’s decline 0.5%.
Image Source: Zacks Investment Research
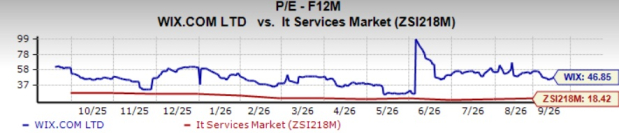
From a valuation standpoint, WIX stock is currently trading at a forward 12-month Price/Earnings ratio of 46.85X, which is higher than the Zacks Computers - IT Services industry average of 18.42X.
Image Source: Zacks Investment Research
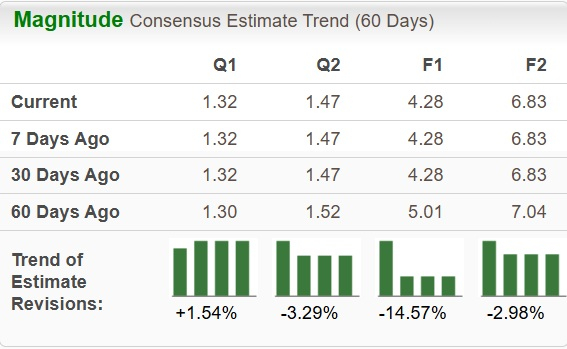
The Zacks Consensus Estimate for WIX’s 2026 earnings is pegged at $4.28, which suggests a 14.57% decline over the figure reported in 2025.
Image Source: Zacks Investment Research
WIX currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Wix.com Ltd. (WIX): Free Stock Analysis Report
GoDaddy Inc. (GDDY): Free Stock Analysis Report
Shopify Inc. (SHOP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).