

M&T Bank Corporation’s MTB solid loan growth, expanding fee businesses and increasing use of artificial intelligence (AI) are likely to support earnings growth. Management comments at the Barclays 24th Annual Global Financial Services Conference provided additional context around these trends.
Loan growth remains a key earnings driver. M&T Bank expects average loans of $141–$143 billion for 2026 (up from prior guidance range of $140–$142 billion), supported by healthy demand from middle-market and large corporate clients. Broad-based commercial loan growth should expand average earning assets and aid interest income. Management expects taxable-equivalent net interest income (NII) to be in the lower half of the $7.2-$7.35 billion range for 2026, with the net interest margin (NIM) likely to remain in the high-3.60% range.
MTB is also strengthening its fee-based businesses, including capital markets, wealth management and mortgage placement. Management expects fee revenues to be near the upper end of previously stated $2.8-$2.85 billion growth range for 2026. Growth in these businesses should reduce the dependence on spread income and support a more diversified revenue base. Capital markets and advisory services can deepen relationships with commercial clients, while wealth management offers relatively recurring revenues. Meanwhile, mortgage-placement activities allow MTB to generate fees without retaining all originated loans, supporting capital efficiency and limiting incremental balance-sheet risks.
The company’s increased adoption of AI could drive productivity gains over time. M&T Bank is deploying AI across areas such as credit underwriting, fraud detection and cybersecurity. Greater automation and improved risk assessment could help streamline operations, contain costs and strengthen operating leverage.
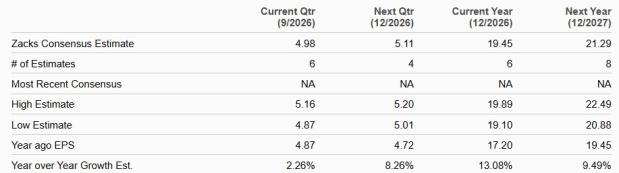
Overall, solid loan growth and higher fee revenues are likely to support near-term earnings, while AI-driven efficiencies could emerge as an additional long-term growth lever. Reflecting these positives, MTB’s earnings are projected to increase 13.1% in 2026 and 9.5% in 2027.
Earnings Estimates
Image Source: Zacks Investment Research
How Are Other Banks Expected to Fare in 2026?
PNC Financial PNC expects net interest income to increase 15-15.5% from the 2025 baseline of $14.4 billion, revised upward from the earlier guidance of 14.5% growth. Non-interest income is expected to rise 11% from the 2025 baseline of $8.7 billion and 9% excluding integration costs and significant items. Driven by this, PNC Financial’s total revenues are anticipated to increase 14% from the 2025 baseline of $23.1 billion.
Citizens Financial CFG expects NII to rise at the high end of 10-12% from the $5.8 billion reported in 2025. Average loans are projected to rise 3-5% from the $142.7 billion reported in 2025. Citizen Financial expects 2026 non-interest income to rise at the high end of 6-8% from the $2.4 billion reported in 2025.
MTB Price Performance & Zacks Rank
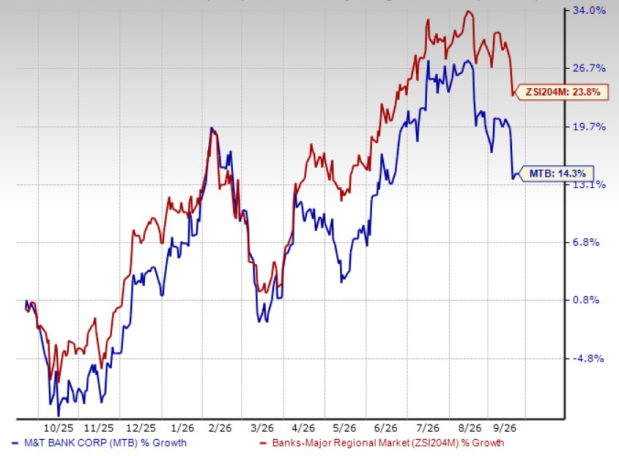
M&T Bank shares have gained 14.3% in the past year compared with the industry’s growth of 23.8%.
Price Performance
Image Source: Zacks Investment Research
The company currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Beyond Nvidia: AI's Second Wave Is Here
The AI revolution has already minted millionaires. But the stocks everyone knows about aren't likely to keep delivering the biggest profits. AI’s second wave is moving from infrastructure to implementation and these companies are at the forefront of this transition, positioned to become what Amazon and Google were to the internet era.
See Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
M&T Bank Corporation (MTB): Free Stock Analysis Report
The PNC Financial Services Group, Inc (PNC): Free Stock Analysis Report
Citizens Financial Group, Inc. (CFG): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).