

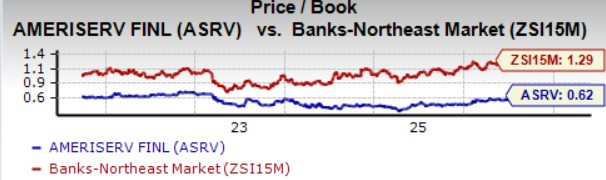
From a valuation perspective, AmeriServ Financial, Inc. ASRV stock looks attractive. ASRV is currently trading at a trailing 12-month price/book (P/B) of 0.62X, a roughly 52% discount compared with the industry average of 1.29X. ASRV also trades at a lower valuation compared to other stocks, such as Norwood Financial Corp. NWFL and SB Financial Group, Inc. SBFG. Currently, both NWFL and SBFG have P/B multiples of 1.29X.
Though ASRV’s cheap valuation may present a potentially profitable opportunity for investors seeking value, a more comprehensive analysis is needed to determine if its discounted valuation is justified based on its fundamentals and growth prospects.
Image Source: Zacks Investment Research
ASRV Stock’s Price Performance
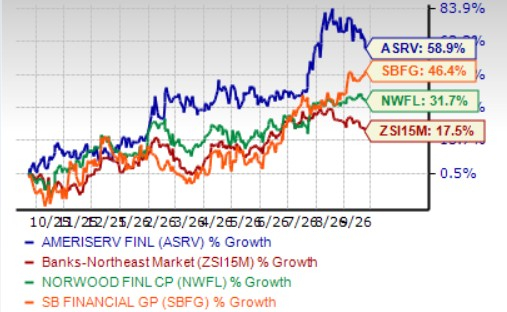
ASRV’s shares have surged 58.9% in the past year compared with the industry’s 17.5% growth. It has also outperformed Norwood Financial and SB Financial, which have rallied 31.7% and 46.4%, respectively, in the same time frame.
Image Source: Zacks Investment Research
Business Tailwinds for ASRV
Improving spread income remains a key earnings tailwind. In the first half of 2026, total interest income increased to $35.6 million from $34.7 million a year earlier, while interest expense declined to $13.4 million from $14.4 million. As a result, net interest income rose to $22.2 million from $20.3 million. The combination of higher asset yields and lower funding costs strengthens AmeriServ’s core earnings base and can support profitability if favorable repricing trends continue over the coming periods.
Credit trends also improved meaningfully in the first half of 2026. AmeriServ recorded a $0.08 million total credit-loss recovery compared with a $3 million provision a year earlier. Net loan charge-offs fell to $0.2 million, or 0.05% of average loans, from $3 million, or 0.56%, in the prior-year period. Non-performing assets also declined to $7.9 million at June 30, 2026, from $8.5 million at year-end 2025, supporting a lower credit-cost burden and a more favorable backdrop for earnings and balance-sheet stability.
Fee-based revenue continued to provide diversification during the first half of 2026. Total non-interest income increased 3.9% year over year to $8.5 million from $8.2 million, while wealth management fees rose 5.5% to nearly $6 million from $5.6 million. The wealth and capital management business also administered $2.8 billion of off-balance-sheet assets at June 30, 2026, up from $2.7 billion at year-end 2025, supporting a broader, more recurring revenue mix and reducing reliance on spread income alone.
The balance sheet also provides support for future growth. As of June 30, 2026, total deposits increased to $1.26 billion from $1.25 billion at year-end 2025, while total borrowed funds declined to $66.7 million from $75.3 million. Shareholders’ equity increased to $123.1 million from $119.3 million. In the first half, deposits grew by $13.2 million while FHLB advances were reduced by $8.4 million, strengthening funding flexibility and reducing reliance on wholesale borrowings as the bank pursues new business.
Headwinds for ASRV’s Business
AmeriServ faces headwinds from weak loan growth and rising operating costs. Loans fell to $1.02 billion at June 30, 2026, from $1.03 billion at year-end 2025, while first-half interest and fees on loans slipped to $29 million from $29.4 million. At the same time, non-interest expense climbed 7.2% to $25.2 million, led by higher professional fees, salaries and technology costs, limiting operating leverage. Service charges on deposit accounts also declined to $0.58 million from $0.61 million, adding pressure to fee income during the period.
Conclusion
Overall, AmeriServ’s improving spread income, lower credit costs, growing wealth management revenues and stronger funding profile provide support for earnings, while weak loan growth, elevated operating expenses and lingering credit risks remain key constraints.
ASRV’s undervaluation, despite the rise in share price, presents a lucrative opportunity for investors to add the stock to their portfolio.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
AmeriServ Financial Inc. (ASRV): Free Stock Analysis Report
SB Financial Group, Inc. (SBFG): Free Stock Analysis Report
Norwood Financial Corp. (NWFL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).