

Affirm Holdings, Inc. AFRM has entered fiscal 2027 with strong operating momentum, supported by robust Gross Merchandise Volume (“GMV”) growth and improving margins. Fiscal 2026 GMV increased 37% year over year to $50.2 billion, while fourth-quarter GMV rose 36% to $14.1 billion. Higher volume is supporting operating leverage, while improving margins indicate that the business model is gaining scalability.
Funding costs increased to $454 million in fiscal 2026 from $425.5 million a year earlier. However, the trend improved in the fourth quarter, with average annualized funding costs declining 103 basis points year over year to 5.8%, aided by favorable repricing across funding channels. With benchmark rates expected to be higher in fiscal 2027, maintaining funding efficiency will be key to further margin expansion.
Credit costs also warrant monitoring. Provision for credit losses rose to $796.7 million in fiscal 2026 from $616.7 million, while 30-plus-day delinquencies, excluding Peloton and Pay-in-X loans, increased 19 basis points to 2.5%. Still, recent loans are performing broadly in line with expectations, suggesting that credit remains manageable rather than becoming a broader constraint on earnings.
Overall, Affirm is increasingly shifting from a growth-at-scale story toward a profitability story. Sustained GMV growth remains important, but funding efficiency and credit performance will increasingly determine how much of that growth reaches the bottom line. If both remain disciplined, continued operating leverage could support further margin expansion in fiscal 2027.
How Are Competitors Faring?
Some of AFRM’s competitors in the digital lending and payments space are Sezzle Inc. SEZL and Klarna Group plc KLAR.
Sezzle continues to benefit from strong BNPL demand, with second-quarter 2026 GMV rising 38% year over year. Faster revenue growth points to improving monetization, while operating leverage is supporting profitability. The key consideration remains whether credit costs stay contained as SEZL scales.
Klarna provides a broader BNPL and payments comparison, with second-quarter 2026 GMV increasing 18% and transaction margin dollars rising 42%. The disparity between volume and margin growth highlights the importance of monetization and cost discipline. For KLAR, sustaining profitability as growth moderates remains important.
AFRM’s Price Performance, Valuation & Estimates
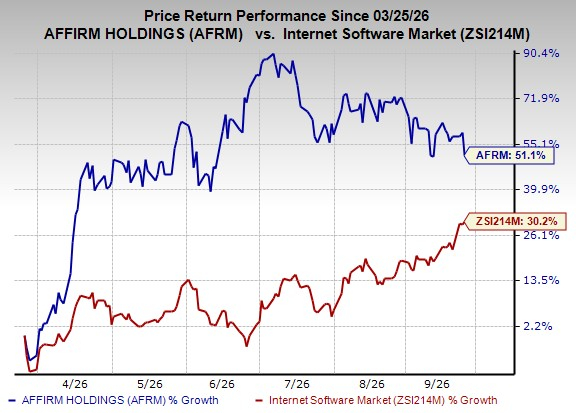
Shares of AFRM have risen 51.1% over the past six months compared with the industry’s 30.2% growth.
Image Source: Zacks Investment Research
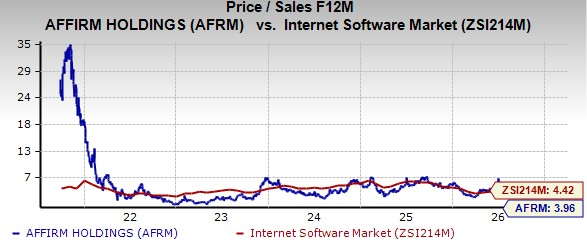
From a valuation standpoint, AFRM trades at a forward price-to-sales ratio of 3.96 compared with the industry average of 4.42. AFRM currently carries a Value Score of D.
Image Source: Zacks Investment Research
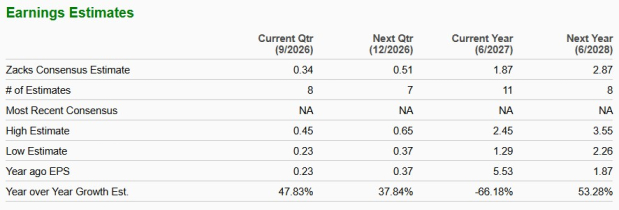
The Zacks Consensus Estimate for AFRM’s 2026 earnings is pegged at $1.87 per share, followed by 53.3% growth next year.
Image Source: Zacks Investment Research
AFRMcurrently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Affirm Holdings, Inc. (AFRM): Free Stock Analysis Report
Sezzle Inc. (SEZL): Free Stock Analysis Report
Klarna Group plc (KLAR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).