

CECO Environmental Corp. CECO and Tetra Tech Inc. TTEK are two prominent names operating in the environmental and industrial services sector. As rivals, both companies operate in multiple industries with significant overlap in the pollution control, water treatment and consulting service markets.
These companies are poised to benefit from significant growth prospects in industrial and environmental services sectors, supported by higher investments in pollution control programs. But which company is better positioned to deliver upside moving ahead? Let’s compare their fundamentals, growth prospects and challenges to see which stock stands out now.
The Case for CECO Environmental
CECO is witnessing solid momentum in its Engineered Systems segment, driven by strength across power generation and natural gas infrastructure projects, along with its strong backlog execution. In the second quarter of 2026, the segment’s revenues surged 35.2% year over year to $173.7 million, constituting 60.9% of the company’s revenues.
Engineered Systems orders surged 200% year over year to $672.1 million. Its organic orders were up 173.8%, driven by strong demand for CECO’s energy and power technologies. Higher spending on energy infrastructure and growth across midstream and downstream markets supported demand for emissions-control and acoustic solutions.
Strength in the Industrial Process Solutions (IPS) segment remains another growth catalyst for CECO. In second-quarter 2026, revenues from the segment increased 8.4% year over year to $61.7 million, which accounted for 21.6% of its quarterly revenues. The revenue growth was supported by strong project execution on semiconductor and industrial ducting backlog.
CECO continues to see strong scrubber technology demand across semiconductor and international markets. The IPS segment’s orders reached $90.3 million in the second quarter, up 81% year over year, including 157% organic growth.
CECO’s backlog increased for 12 consecutive quarters and reached $1.8 billion at second-quarter 2026, with most expected to convert within one to two years. A significant share of the backlog comprises long-cycle power generation and gas infrastructure projects, while industrial process solutions provide additional diversification and help support cash generation.
While CECO’s adjusted results showed operational improvement, GAAP results were impacted by acquisition costs and purchase-accounting adjustments. The company reported a second-quarter 2026 GAAP net loss of $34.8 million against net income of $9.5 million a year earlier. Higher costs, including $45.5 million in acquisition and integration expenses and a $9.5 million inventory fair-value adjustment associated with the Thermon acquisition, pressured margins.
Rising debt levels remain another concern. The company exited second-quarter 2026 with $727.7 million of total outstanding borrowings, much higher than $212.4 million at 2025-end. This increase was primarily attributable to funds raised to support the Thermon buyout. At the end of the quarter, CECO’s net leverage was 2.7x trailing-12-month bank EBITDA, above its 2.0-2.5x target range.
The Case for Tetra Tech
Tetra Tech is benefiting from multi-year investment in water, environmental and defense programs. In third-quarter fiscal 2026 (ended June 2026), net revenues from the Government Services Group segment (excluding USAID/DOS and episodic disaster response) rose 7% year over year, supported by water infrastructure and defense projects. The Commercial & International Services Group segment’s net revenues increased 9%, supported by strength in U.K. water and digital automation projects.
Management highlighted significant opportunities in the water sector, including the U.K. AMP8 cycle’s £105 billion investment through 2030 and more than £2 billion in contract capacity across the UK, the Netherlands and Ireland. Australia’s digital water investment plans and the recent PFAS treatment, hydropower, Army Corps engineering and water-monitoring awards further support demand for Tetra Tech’s services.
In January 2026, it completed the acquisition of Halvik, a leading provider of advisory consulting services. The inclusion of Halvik’s advanced data analytics, systems modernization and cybersecurity expertise boosted TTEK’s analytics and digital solutions portfolio.
The company remains committed to rewarding its shareholders through dividend payouts. In the first nine months of fiscal 2026, it paid out dividends of $52.5 million and repurchased about $202 million of common stock. It hiked the quarterly dividend rate by 11% in July 2026. Also, the company recently announced a significant expansion of its share repurchase program. The latest buyback authorization, along with the $398 million left under its existing program (as of June 28, 2026), brings the total share repurchase authority to $898 million.
TTEK’s operating cash flow rose 31% year over year to $467 million in the first nine months of fiscal 2026, while net debt to EBITDA improved to 0.88x from 0.96x. Strong cash generation supports shareholder returns, acquisitions and debt reduction efforts.
However, lower federal co-funding for flood protection remains a concern for its U.S. state and local markets. Also, TTEK expects Department of State work to continue at a conservative level. In U.S. commercial markets, growth in energy, mining and minerals projects has been partly offset by weaker renewable energy activity, including Atlantic Coast offshore wind program cancellations.
The Zacks Consensus Estimate for CECO & TTEK
Image Source: Zacks Investment Research
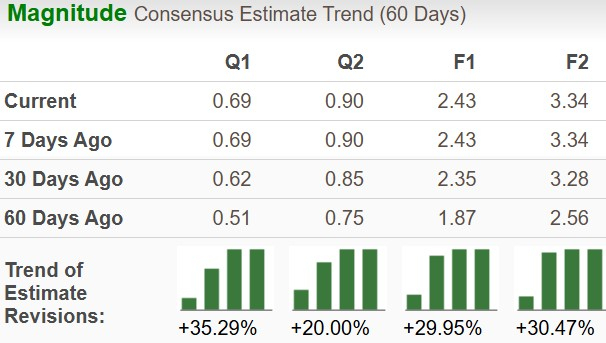
The Zacks Consensus Estimate for CECO’s 2026 earnings per share (EPS) implies year-over-year growth of 173%. CECO’s EPS estimates for 2026 have increased over the past 60 days.
Image Source: Zacks Investment Research
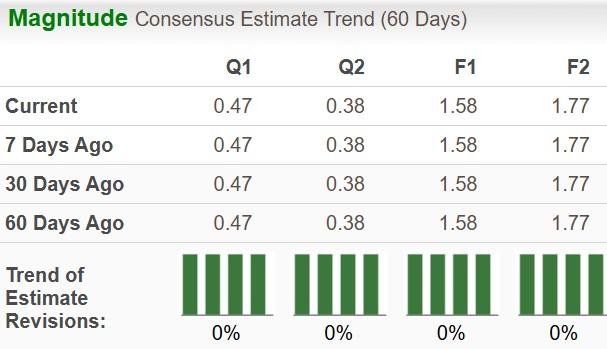
The Zacks Consensus Estimate for TTEK’s 2026 EPS indicates year-over-year growth of 1.3%. TTEK’s EPS estimates have been stable over the past 60 days for 2026.
Price Performance and Valuation
Image Source: Zacks Investment Research
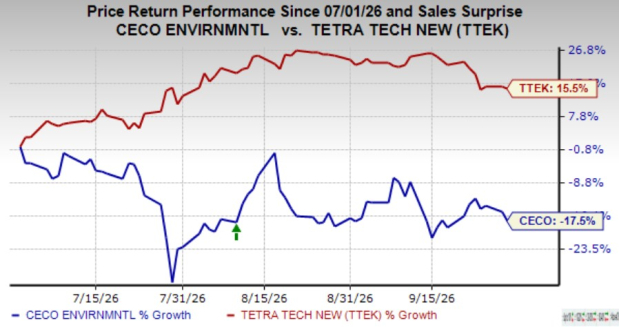
In the past three months, CECO shares have declined 17.5%, while Tetra Tech stock has gained 15.5%.
Image Source: Zacks Investment Research
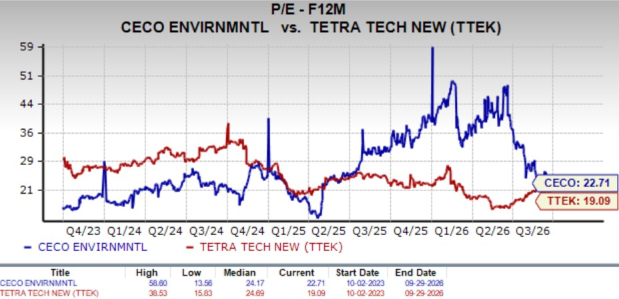
CECO is trading at a forward 12-month price-to-earnings ratio of 22.71X, while TTEK’s forward earnings multiple sits at 19.09X.
Final Take
CECO’s strong foothold in power generation, gas infrastructure and semiconductors markets has been dented by rising operating expenses and premium valuation. Tetra Tech’s strength in the government and commercial sectors, accretive buyouts and strong liquidity position it for healthy long-term growth.
Both companies currently carry a Zacks Rank #3 (Hold). This makes choosing one stock a difficult task. Considering their long-term prospects, valuation and margin projections, TTEK seems to have an edge over CECO currently. While TTEK carries a VGM of C, CECO has a VGM of F.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Tetra Tech, Inc. (TTEK): Free Stock Analysis Report
CECO Environmental Corp. (CECO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).