

The consumer staples industry is navigating a challenging environment marked by cautious consumer spending, heightened value-seeking behavior, inflationary pressures and evolving shopping patterns. Colgate-Palmolive Company CL and The Clorox Company CLX emerge as two prominent players with strong brand portfolios and leading positions across essential consumer categories.
While Colgate is benefiting from its global scale, category leadership, innovation and strong emerging-market presence, Clorox is focused on rebuilding market share, strengthening its brands, improving productivity and expanding its health and hygiene platform through the GOJO acquisition. Both companies are leveraging innovation, pricing, revenue growth management and digital capabilities to navigate a volatile operating environment.
This face-off between Colgate and Clorox examines how brand strength, market-share momentum, portfolio positioning and differences in growth strategies shape their long-term growth potential and defensive appeal.
The Case for CL
Colgate’s investment thesis is anchored in its strong global brands, category leadership, broad geographic footprint and diversified portfolio spanning Oral Care, Personal Care, Home Care and Hill’s Pet Nutrition. The company’s global operating model continues to support growth despite a volatile macroeconomic environment. In the second quarter of 2026, organic sales increased across four of five divisions and three of four categories, while emerging markets delivered mid-single-digit growth, led by India, Brazil, Mexico and China.
Innovation and premiumization remain important pillars of Colgate’s strategy. The company is scaling new products such as Optic White Pro Series with ActivShine Technology and expanding Fabuloso into new forms. It is also increasing brand support to strengthen consumer engagement and improve market share, particularly in North America, where heightened competition and softer category trends have pressured performance.
Colgate is also investing heavily in digital capabilities, data, analytics and Artificial Intelligence. Its Promo AI tools are being scaled globally to improve promotional effectiveness, while revenue growth management and “funding the growth” initiatives are helping the company generate resources for increased advertising and brand investment. These efforts are designed to support both profit growth and stronger category positions.
Emerging markets remain a major growth opportunity. India, Brazil, Mexico and China continue to contribute meaningfully to the company’s performance. In China, Colgate has been leveraging social media, business-to-consumer platforms and localized innovation, with the Colgate China business delivering consistent mid-single-digit performance. The company is also transferring innovations developed in China, such as Optic White Purple, to other markets.
Hill’s Pet Nutrition provides another important growth avenue. Despite a soft pet-care category, Hill’s continues to outperform, supported by science-led premium innovation, therapeutic products and growth opportunities in areas such as wet food, cat food, small pets and international markets. Overall, Colgate is combining innovation, premiumization, revenue growth management, digital transformation and emerging-market expansion to strengthen its competitive position while maintaining a balanced approach between pricing and volume.
The Case for CLX
Clorox’s strategy is centered on strengthening its core brands, rebuilding market share, improving operational efficiency and creating a portfolio positioned for more consistent profitable growth. The company is responding to heightened value-seeking behavior by sharpening product superiority, improving price-pack architecture, increasing promotion effectiveness and strengthening brand-building investments. Clorox is also benefiting from the completion of its ERP transformation.
Clorox is focused on driving superiority across its portfolio through improvements in products, packaging, propositions, distribution and pricing. This approach has already helped stabilize market share in several businesses. Home Care has delivered eight consecutive quarters of share growth in fourth-quarter fiscal 2026, while Glad and Hidden Valley Ranch also returned to share growth following targeted investments in innovation, pricing, marketing and distribution.
Innovation is another key pillar of Clorox’s strategy. The company doubled innovation spending as a percentage of sales in fiscal 2026 and expects further progress in fiscal 2027. It is investing in packaging upgrades, product improvements and wellness-oriented offerings while using targeted pricing and revenue growth management to address changing consumer needs.
The GOJO acquisition has strengthened Clorox’s health and hygiene platform and expanded its presence in professional and consumer hygiene markets. Management said the acquired business performed ahead of expectations in the fourth quarter and is expected to be accretive to adjusted EPS in fiscal 2027.
However, the company continues to face elevated inflation, muted underlying demand and increased promotional activity. Fiscal 2027 organic sales growth is expected to benefit from lapping the prior-year ERP inventory drawdown, while underlying growth remains modest. Gross margin is expected to stay under pressure from higher commodity, manufacturing and logistics costs. Weakness in Litter and cautious consumer spending also remain concerns.
Price Performance & Valuation of CL & CLX
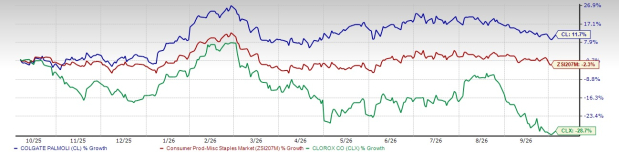
In the past year, Colgate has delivered higher returns, with shares gaining 11.7% against Clorox’s decline of 28.7%. Meanwhile, the Consumer Products - Staples industry has dropped 2.3% in the same time frame.
Image Source: Zacks Investment Research
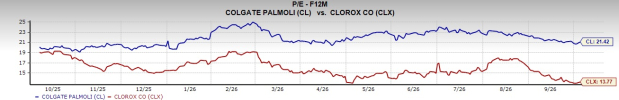
From a valuation standpoint, CL currently trades at a forward price-to-earnings (P/E) multiple of 21.42X compared with CLX’s 13.77X. Here, CLX trades at a cheaper forward earnings multiple compared with CL.
Image Source: Zacks Investment Research
How Does Zacks Consensus Estimate Compare for CL & CLX?
Colgate’s 2026 revenues and earnings per share (EPS) are projected to increase 4.8% and 4.9% year over year to $21.4 billion and $3.87, respectively. CL’s 2027 revenues and EPS are likely to increase 3.2% and 5.2% year over year to $22 billion and $4.07, respectively. The company has a strong track record of earnings surprises.
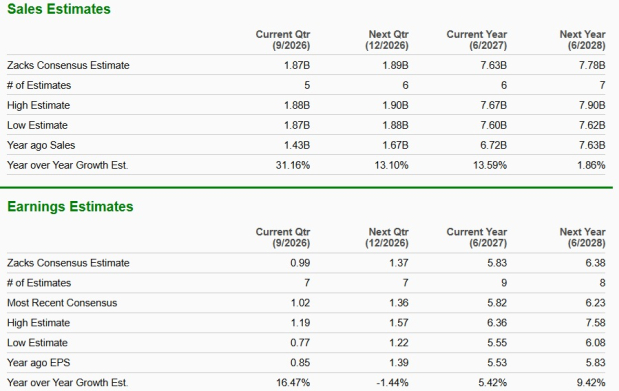
Image Source: Zacks Investment Research Clorox’s fiscal 2027 revenues and EPS are expected to rise 13.6% and 5.4% year over year to $7.6 billion and $5.83, respectively. CLX’s fiscal 2028 revenues and EPS are likely to jump 1.9% and 9.4% year over year to $7.8 billion and $6.38, respectively.
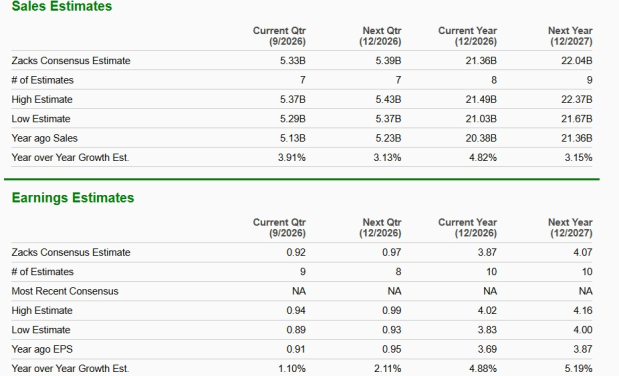
Image Source: Zacks Investment Research
CL vs. CLX: Who Has the Edge?
In this consumer staples face-off, Colgate moves ahead, supported by stronger operating momentum, global diversification, category leadership and a more consistent growth profile. The company is benefiting from solid emerging-market performance, premium innovation, Hill’s strength and increasing investments in digital capabilities, while its revenue growth management initiatives are helping offset inflationary pressures.
Colgate also has a more favorable recent share-price record. Its shares have outperformed the broader industry over the past year, while the stock's earnings outlook remains supported by positive operating trends and a strong global footprint. The key risk is valuation, as CL trades at a substantial premium to Clorox.
That said, Clorox remains a compelling transformation story. The GOJO acquisition expands its health and hygiene platform, while ERP-driven productivity, portfolio optimization, innovation and market-share recovery could support earnings growth. However, Clorox continues to face elevated inflation, muted category growth and the need to rebuild organic sales momentum. Management expects fiscal 2027 inflation to exceed $200 million, with the impact particularly pronounced in the first half.
For investors prioritizing business stability, global diversification, brand strength, market-share momentum and earnings visibility, Colgate takes the lead. Clorox offers greater transformation-driven upside and a cheaper valuation, but its investment case depends more heavily on successful execution, margin recovery and sustained market-share gains.
Supporting this stance, CL currently carries a Zacks Rank #3 (Hold), while Clorox at present displays a Zacks Rank #4 (Sell).
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Colgate-Palmolive Company (CL): Free Stock Analysis Report
The Clorox Company (CLX): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).