

Capri Holdings Limited CPRI is building momentum at Jimmy Choo through product innovation, targeted marketing and stronger customer engagement. Expanding accessories and casual footwear offerings are broadening customer appeal, while an enhanced pricing architecture is attracting younger shoppers without compromising luxury positioning. These initiatives are building the brand’s foundation for sustainable growth.
In first-quarter fiscal 2027, Jimmy Choo’s revenues increased 10.5% year over year to $179 million, exceeding management’s expectations. Constant-currency growth was 9.3%. Revenues rose 26% in the Americas, 5% in Europe, the Middle East, and Africa (EMEA) and 3% in Asia. Retail and wholesale both recorded low-double-digit growth, with North American department stores delivering double-digit point-of-sale increases.
Marketing efforts reinforced consumer connections. The Natural Reflection campaign featured the Glace Mule, Jelly Drop sandal and Cinch bag. An influencer trip to Nice brought together 16 creators with more than 36 million combined followers, generating nearly 50 million impressions. Curated Bon Bon client events drove a 40% increase in very important client sales, while Jimmy Choo’s global consumer database expanded 7% year over year.
Accessories sales grew at a double-digit pace, with Bon Bon and Cinch performing strongly and Bar and Curve styles broadening brand reach. Management also reported encouraging dress and casual footwear performance, highlighting the Faiz lace pump, Margot Flat and Sunny sneaker. Campaigns featuring Wang Yibo and Bai Lu strengthened visibility in Asia, complementing efforts to attract new customers.
Higher revenues improved expense leverage, lifting operating income to $13 million from $4 million and expanding the operating margin by 480 basis points to 7.3%. However, channel mix primarily drove a 170-basis-point decline in gross margin to 68.7%. Capri’s adjusted fiscal 2027 outlook anticipates approximately $635 million in Jimmy Choo revenues and a low-single-digit operating margin. Continued product innovation and deeper consumer engagement remain central to turning the brand’s regional momentum into sustained profitable growth.
CPRI’s Price Performance, Valuation & Estimates
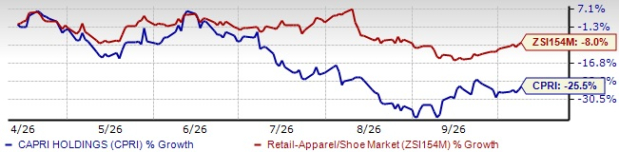
Shares of Capri Holdings have lost 25.5% over the past six months compared with the industry’s 8% decline.
Image Source: Zacks Investment Research
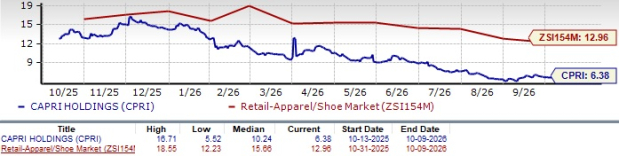
From a valuation standpoint, CPRI trades at a forward price-to-earnings ratio of 6.38, below the industry’s average of 12.96. It has a Value Score of B.
Image Source: Zacks Investment Research
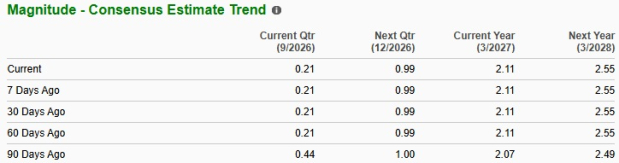
The Zacks Consensus Estimate for Capri Holdings’ fiscal 2027 earnings implies year-over-year growth of 40.7%, whereas the same for fiscal 2028 indicates an uptick of 21%. Earnings estimates for fiscal 2027 and 2028 have remained unchanged over the past 60 days.
Image Source: Zacks Investment Research
CPRI’s Zacks Rank & Key Picks
Capri Holdings currently carries a Zacks Rank #3 (Hold).
Genesco Inc. GCO is a Nashville-based specialty retailer and branded company. It sells footwear and accessories through retail stores. The company sports a Zacks Rank #1 (Strong Buy) at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
The Zacks Consensus Estimate for Genesco’s current fiscal-year earnings indicates 62.1% growth from the year-ago actual. GCO delivered a trailing four-quarter average earnings surprise of 11.2%.
Designer Brands Inc. DBI designs, produces and retails footwear and accessories. It offers shoes, boots, sandals, sneakers, socks, handbags and accessories. It currently carries a Zacks Rank #2 (Buy).
The Zacks Consensus Estimate for Designer Brands’ current fiscal-year earnings and sales suggests growth of 225% and 0.6%, respectively, from the year-ago actuals. DBI delivered a trailing four-quarter average earnings surprise of 108.1%.
G-III Apparel Group, Ltd. GIII designs, sources, distributes and markets a broad range of apparel and accessories under owned, licensed and private-label brands. The company also holds a Zacks Rank of 2 at present.
The Zacks Consensus Estimate for G-III Apparel’s current fiscal-year earnings and sales suggests decline of 13.8% and 8.4%, respectively, from the year-ago actuals. GIII delivered a trailing four-quarter average earnings surprise of 1.4%.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Capri Holdings Limited (CPRI): Free Stock Analysis Report
Genesco Inc. (GCO): Free Stock Analysis Report
G-III Apparel Group, LTD. (GIII): Free Stock Analysis Report
Designer Brands Inc. (DBI): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).