

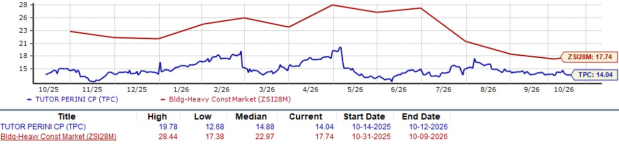
Tutor Perini Corporation TPC is trading at a discount to the Building Products - Heavy Construction industry, presenting a potential opportunity for value-focused investors. Despite its attractive valuation, the stock's long-term appeal depends on whether it can sustain earnings growth, improve profitability and successfully execute portfolio expansion for large infrastructure projects.
The company benefits from a substantial backlog, supported by elevated public infrastructure spending and strong demand for large-scale transportation, defense and government projects. Strengthening cash generation further supports its financial position. However, project execution risks, unresolved contract disputes and the timing of new awards warrant caution. The question is whether TPC’s discounted valuation represents an attractive entry point or reflects underlying business risks.
TPC Stock’s Valuation (P/E F12M)
Image Source: Zacks Investment Research
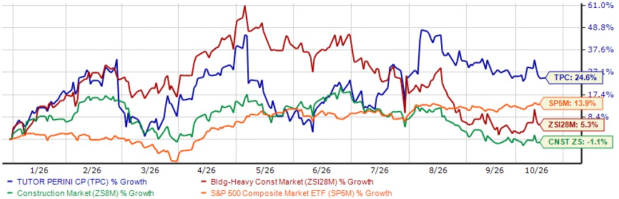
Tutor Perini's improving operational performance and stronger financial discipline have supported investor confidence, with shares gaining approximately 24.6% year to date, outperforming the industry, the broader Construction sector and the S&P 500 Index. However, the stock has retreated approximately 18.4% from its August high, indicating some investor caution despite its solid year-to-date gains.
TPC’s YTD Price Performance
Image Source: Zacks Investment Research
Strong Backlog Supports Long-Term Growth
Tutor Perini's near-record backlog of $19.9 billion at the end of second-quarter 2026 reflects robust public infrastructure spending and strong demand for complex transportation, defense and government projects. Limited competition for large-scale construction contracts and strategic project wins have further supported its backlog. It includes nine mega-projects valued at approximately $16 billion, many in the early stages of execution. As these higher-margin projects advance, they should support revenue growth and profitability through 2027.
Additionally, a pipeline exceeding $200 billion in potential bidding opportunities over the next three to four years offers substantial growth prospects. Continued federal, state and local infrastructure investments, along with selective bidding for high-margin projects, should support future contract awards and backlog replenishment.
Indo-Pacific Expansion Creates New Growth Opportunities
Tutor Perini is expanding its presence in the Indo-Pacific region through its Black Construction subsidiary, leveraging its expertise in complex military and infrastructure projects. The company secured a $652 million contract at Naval Base Guam during the second quarter. Management also identified more than $4.6 billion in potential federal project opportunities over the following 12-18 months, with additional opportunities exceeding $1 billion beyond that period. Planned port, harbor, airfield and fueling infrastructure investments could support future contract wins and higher-margin growth.
Specialty Turnaround and Financial Strength Support Upside
Tutor Perini's improving project execution is driving margin expansion, with Civil and Building operating margins reaching 15.3% and 5.6%, respectively, in the second quarter. The Specialty Contractors segment is emerging as an earnings growth driver, supported by increasing activity on electrical and mechanical projects in New York and Texas. Revenues rose 47% year over year, while operating margin improved to 2.2% from negative 10.2%. As newer projects ramp up, management expects further margin expansion, targeting sustainable margins of 5%-8% over the longer term.
Strong Cash Flow and Refinancing Enhance Financial Flexibility
The company's financial position is also strengthening. Operating cash flow reached a record $334.1 million in the first half of 2026, while recent debt refinancing is expected to generate approximately $21 million in annual cash interest savings, enhancing financial flexibility. These improvements should enhance liquidity, support growth investments and provide greater flexibility for shareholder returns.
What Risks Could Limit TPC's Upside?
Despite favorable growth prospects, Tutor Perini faces execution challenges associated with managing multiple large-scale construction projects. Cost overruns, labor constraints, inflation and project delays could pressure margins and disrupt expected earnings growth.
Moreover, its backlog declined approximately 6% year over year, while new awards in the first half of 2026 were lower than the prior-year period due to award timing. Although management remains optimistic about future opportunities, slower contract conversions or delays in government infrastructure funding could affect revenue visibility. Unresolved contract claims and disputes also introduce uncertainties surrounding cash collections and profitability.
Stable Earnings Estimates Support TPC's Growth Outlook
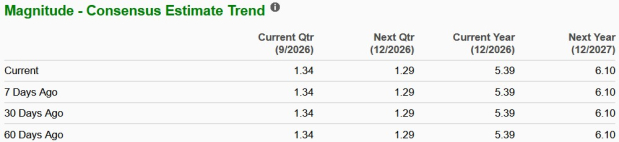
Tutor Perini's earnings outlook remains optimistic, supported by expectations for sustained growth and improving profitability. The Zacks Consensus Estimates for 2026 and 2027 earnings have remained unchanged over the past 60 days at $5.39 and $6.10 per share, respectively. However, these estimates imply year-over-year growth of 25.6% and 13.2%, respectively, highlighting TPC’s favorable earnings prospects.
TPC Stock’s Estimate Revision
Image Source: Zacks Investment Research
Can Tutor Perini Build a Lead Over Its Peers?
Tutor Perini competes with Sterling Infrastructure, Inc. STRL, Fluor Corporation FLR and Dycom Industries, Inc. DY across infrastructure construction and related markets, although their growth strategies differ.
Sterling is benefiting from strong demand for data centers and semiconductor facilities, with its combined backlog reaching $5.6 billion in second-quarter 2026. Its focus on higher-margin projects and capacity expansion supports future growth.
Fluor's diversified engineering and construction capabilities span infrastructure, energy, mining and nuclear projects. Its backlog reached $26.9 billion, supported by more than $6 billion in new awards. Meanwhile, Dycom's record $12.2 billion backlog reflects strong demand for fiber deployment and data center infrastructure.
Tutor Perini maintains a competitive position in complex civil construction, supported by its $19.9 billion backlog and expertise in transportation and government projects. Its disciplined bidding strategy and improving financial strength support long-term growth. However, Sterling's growing exposure to mission-critical projects, Fluor's diversified engineering capabilities and Dycom's expanding presence in digital infrastructure present strong competition.
Is TPC a Value Trap or an Opportunity?
Tutor Perini's discounted valuation, improving margins, substantial backlog and stronger balance sheet suggest that the stock offers genuine long-term value potential rather than being an outright value trap. Favorable earnings growth expectations and infrastructure demand further strengthen its investment case.
However, execution uncertainties, contract-related risks and the stock's recent appreciation temper its near-term attractiveness. With a Zacks Rank #3 (Hold), TPC stock appears better suited for investors willing to maintain their positions while monitoring operational progress. New investors may prefer to wait for greater earnings visibility or a more compelling entry point before increasing exposure. Investors must therefore weigh TPC's favorable earnings outlook and attractive valuation against potential execution challenges when assessing its further upside. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
7 Best Stocks for the Next 30 Days
Just released: Experts distill 7 elite stocks from the current list of 220 Zacks Rank #1 Strong Buys. They deem these tickers "Most Likely for Early Price Pops."
Since 1988, the full list has beaten the market more than 2X over with an average gain of +23.9% per year. So be sure to give these hand picked 7 your immediate attention.
See them now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Tutor Perini Corporation (TPC): Free Stock Analysis Report
Fluor Corporation (FLR): Free Stock Analysis Report
Dycom Industries, Inc. (DY): Free Stock Analysis Report
Sterling Infrastructure, Inc. (STRL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).