

Gildan Activewear Inc. GIL raised its 2026 earnings and cash-flow outlook after second-quarter results showed faster-than-expected synergy capture and a sizable tariff-refund benefit. The company now expects adjusted earnings of $4.65-$4.75 per share, up from $4.20-$4.40 previously.
The stronger profit outlook comes despite revenue being expected at the low end of the prior $6-$6.2 billion range. That mix puts the focus on margin expansion, HanesBrands integration and how much of the tariff benefit can support earnings beyond 2026.
Gildan now projects an adjusted operating margin of about 21.8% for 2026 compared with its previous view of about 20%. Free cash flow is expected to reach roughly $1 billion, up from the prior forecast of more than $850 million. Management also expects about $220 million of International Emergency Economic Powers Act tariff refunds in 2026, with most anticipated in the third quarter.
The refund is not entirely a one-time lift. Roughly half relates to tariffs previously paid on products made in the Dominican Republic-Central America-United States Free Trade Agreement region. Following U.S. tariff-policy changes, qualifying apparel is no longer subject to those tariffs, creating a structural benefit. Gildan plans to reinvest a significant portion of the nonrecurring refund into brand building, retail marketing, product innovation and packaging.
Gildan Activewear, Inc. Price and Consensus
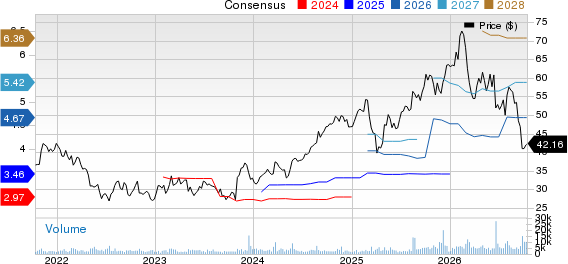
Gildan Activewear, Inc. price-consensus-chart | Gildan Activewear, Inc. Quote
Integration savings provide another earnings lever. Gildan remains on pace for about $100 million of synergies in 2026 and continues to target roughly $250 million of annual run-rate cost synergies over the next three years. Most 2026 synergy-capture initiatives had already been implemented by the end of the second quarter, while manufacturing, distribution and information-technology optimization remained in progress.
Second-quarter results underscored that the earnings story is stronger than the sales picture. Net sales from continuing operations rose 72.3% to $1.58 billion, largely reflecting the HanesBrands acquisition, while adjusted earnings increased 32% to $1.28 per share. Adjusted operating margin was 22.3%. Wholesale sales slipped 1.5% year over year as Gildan reduced inventory across customer channels, while retail demand remained soft.
Tariff refunds are also shaping results elsewhere in apparel. Columbia Sportswear Company COLM recognized a substantial tariff-refund benefit in its second quarter and raised its 2026 profit outlook, highlighting how trade-policy changes can materially affect sector margins. Kontoor Brands, Inc. KTB, another apparel peer, raised its 2026 adjusted earnings outlook after second-quarter revenue from continuing operations increased 19%, showing that brand execution and portfolio changes remain important alongside tariff effects.
Balance-sheet repair remains a constraint. Gildan ended the first half with about $4.7 billion of net debt and leverage of 3.2 times pro forma adjusted EBITDA. The planned sale of HanesBrands Australia for about $490 million is expected to help reduce debt and move leverage toward the midpoint of Gildan’s 1.5-2.5 times target range.
The bottom line is that Gildan’s higher 2026 outlook rests on a combination of recurring integration savings, a structural tariff benefit and a sizable nonrecurring refund, while soft retail demand and elevated debt remain counterweights. The stock currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Image Source: Zacks Investment Research
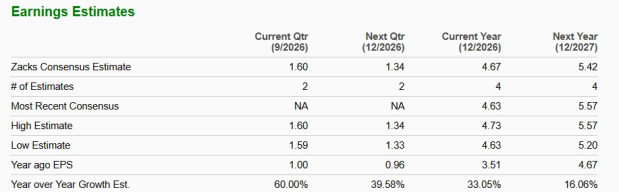
GIL also has a VGM Score of A, with a Value Score of B, Growth Score of B and Momentum Score of B. Those favorable Style Scores point to balanced characteristics across valuation, growth and momentum, but the Zacks Rank #3 suggests a more neutral near-term earnings-estimate backdrop. Together, they support a measured view rather than a clear directional signal.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Gildan Activewear, Inc. (GIL): Free Stock Analysis Report
Columbia Sportswear Company (COLM): Free Stock Analysis Report
Kontoor Brands, Inc. (KTB): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).