

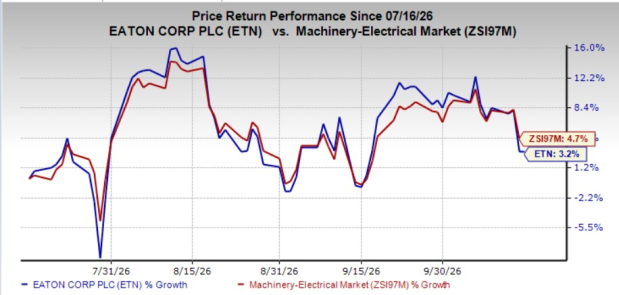
Shares of Eaton Corporation ETN have gained 3% in the past three months, underperforming the industry’s 4.7% increase.
Eaton’s underperformance likely reflects concerns about margin compression, rising input costs and its premium valuation.
Eaton, a diversified power management company and a global technology leader in electrical components and systems, is gaining from rising electrification and data center demand.
ETN vs Industry in 3 Months
Image Source: Zacks Investment Research
Industrial tech stocks like Emerson Electric Co. EMR and Powell Industries POWL have gained 15.8% and lost 28.1%, respectively, in the past three months.
Are Eaton Shares Expensive?
Eaton shares are trading at a premium to the industry. The company’s forward 12-month price-to-earnings of 26.34X is higher than its industry’s 23.12X and above the median of 24.31X over the last five years.
Image Source: Zacks Investment Research
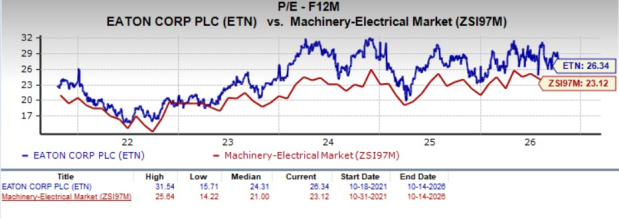
A premium valuation reflects stronger structural growth and higher-quality earnings, driven by electrification, AI/data-center power demand, grid modernization and aerospace. Eaton’s strong backlog, leading positions in mission-critical electrical markets and improving margins reinforce expectations for sustained above-industry growth and profitability.
Eaton shares are more expensive than industrial tech stocks like Emerson Electric and Powell Industries.
The Case for Eaton
Eaton is well positioned to capitalize on several long-term growth drivers, including grid modernization, data center expansion, industrial automation, the energy transition and a recovery in aerospace markets. Its growing backlog reflects healthy customer demand and reinforces its position as a leading provider of mission-critical power management solutions.
Innovation and sustainability remain central to Eaton’s long-term growth strategy. The company plans to invest approximately $3 billion in research and development over the next decade to advance its technologies and strengthen its product portfolio. Additionally, Eaton is investing more than $242 million in a new manufacturing facility in North Little Rock, AR, to expand production capacity and address rising demand for critical-power infrastructure.
Strategic acquisitions are further enhancing Eaton’s presence in attractive, higher-margin markets. The company recently agreed to acquire COL Group from Oaktree’s Power Opportunities strategy for €810 million ($923 million). The transaction will strengthen Eaton’s European power distribution platform by adding medium-voltage technologies and manufacturing capacity, positioning it to benefit from increasing demand from data center and utility customers. Earlier acquisitions, including Fibrebond, Resilient Power, Ultra PCS and Boyd, are also supporting growth, expanding technological capabilities and contributing to margins.
Artificial intelligence remains a significant growth opportunity as data centers require greater power capacity, reliability and energy efficiency. Eaton is expanding its presence across the electrical power value chain while benefiting from healthy demand in utilities, commercial aerospace and defense. This diversified end-market exposure reduces dependence on individual industries and supports long-term business resilience.
Operational efficiency and disciplined capital allocation are additional priorities. Eaton is focusing on productivity improvements, portfolio optimization and investments in high-growth markets. The planned separation of its Mobility business is expected to sharpen its strategic focus on higher-growth, higher-return opportunities. Meanwhile, more than $1 billion in capacity investments and approximately two dozen Electrical Americas projects should support incremental revenue growth as new facilities become operational.
For 2026, Eaton expects organic growth of 11–13%, segment operating margins of 24.1–24.5% and adjusted earnings per share of $13.40–$13.60. These targets reflect management’s confidence in sustained demand, operational improvements and the company’s ability to capitalize on structural growth opportunities across its core markets.
Encouraging Estimates for Eaton
The Zacks Consensus Estimate for 2026 and 2027 revenues indicates a 19.3% and 10.9% year-over-year increase, respectively. The same for 2026 and 2027 earnings implies a 12.4% and an 18.4% year-over-year increase, respectively. The expected long-term earnings growth rate is pegged at 12.7%.
Optimistic Sentiment on Eaton
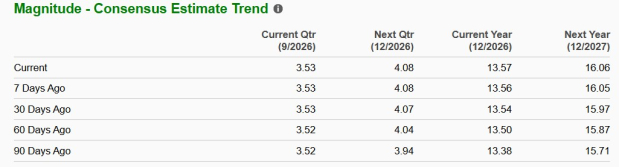
The Zacks Consensus Estimate for ETN’s 2026 and 2027 earnings per share has moved 0.2% and 0.66% north, respectively, in the last 30 days.
Image Source: Zacks Investment Research
The Zacks Consensus Estimate for Emerson’s 2026 bottom line witnessed no movement, but that for 2027 moved north in the last 30 days.
However, for Powell, the consensus estimate for 2026 and 2027 witnessed no movement in the same time frame.
Parting Thoughts on ETN
Eaton continues to deliver solid performance across its core businesses, supported by strong demand from expanding data center infrastructure. Continued research and development investments are fostering innovation, enhancing its product portfolio and addressing changing customer requirements. Strategic acquisitions are further strengthening Eaton’s technological capabilities and presence in high-growth markets.
Favorable earnings estimate revisions, healthy investment returns and a growing backlog support its long-term prospects. However, the stock’s premium valuation and mixed analyst sentiment keep us on the sidelines. Therefore, a wait-and-see approach appears appropriate for this Zacks Rank #3 (Hold) stock. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Eaton Corporation, PLC (ETN): Free Stock Analysis Report
Emerson Electric Co. (EMR): Free Stock Analysis Report
Powell Industries, Inc. (POWL): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).