

GE Aerospace GE raised its 2026 financial outlook and sharpened expectations for commercial services growth in 2027 on its third-quarter earnings call. Management cited a substantial maintenance backlog despite higher fuel costs pressuring airlines.
Executives also addressed parts shortages, engine retirements and GE9X production costs. The discussion focused on execution and future margins beyond the earnings beat.
GE Raises Full-Year Guidance Across Key Measures
Chief financial officer Rahul Ghai said that GE now expects 2026 adjusted revenue growth of 19-20%, up from a high-teens forecast. Operating profit guidance rose to $10.9-$11 billion.
GE also lifted adjusted EPS guidance to $8-$8.10 and free cash flow guidance to $9.1 billion-$9.4 billion. Ghai cited stronger services demand, higher profits and improved cash conversion.
Third-quarter adjusted EPS of $2.25 exceeded the Zacks Consensus Estimate of $2.02. Adjusted revenues of $13.29 billion topped the $12.65 billion estimate, while operating margins expanded 220 basis points to 22.5%.
GE Aerospace Price, Consensus and EPS Surprise
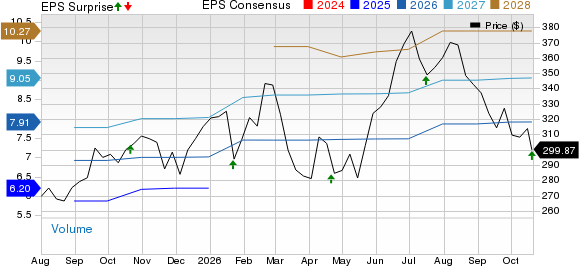
GE Aerospace price-consensus-eps-surprise-chart | GE Aerospace Quote
GE Aerospace Sees Services Momentum Extending Into 2027
Chairman and chief executive officer H. Lawrence Culp said that commercial services revenues should grow at a low-double-digit rate in 2027, backed by more than $170 billion in backlog and a growing installed engine base.
A Bernstein analyst questioned whether elevated fuel prices and airline profitability pressures could undermine maintenance demand. Culp acknowledged the difficult environment but emphasized that much of next year's work is tied to flight cycles already completed.
A Citi analyst asked whether exceptionally low CFM56 retirements could rebound. Culp mentioned that retirements were tracking below 2% in 2026 and could rise in 2027, while demand supported roughly 2,400 shop visits.
GE Confronts Backlogs and Spare Parts Delinquencies
Culp credited FLIGHT DECK practices with improving supplier output and repair throughput. Material input has grown sequentially for 10 consecutive quarters, while internal shop visit output reached another record.
However, a Wolfe Research analyst pressed management about increasing spare parts delinquencies. Ghai said that services orders rose 23%, leaving demand strong enough to push unfilled orders higher despite better material availability.
Culp wants to reduce delinquency even as backlog expands. He noted that faster turnaround times helped bring LEAP-related aircraft groundings to nearly zero since the summer.
GE Aerospace Details the GE9X Margin Trade-Off
Responding to a Wells Fargo analyst, Ghai projected approximately $300 million in additional year-over-year GE9X losses in 2027. Higher engine shipments will more than offset expected reductions in cost per unit.
He nevertheless expects company margins in 2027 to remain aligned with 2026, supported by an expected $3.5-$4 billion increase in services revenue and modest defense margin expansion. Management expects margin expansion from 2028 as GE9X pressures ease and LEAP services mature.
A Jefferies analyst also questioned the GE9X certification timeline. Culp said that upgraded mid-seal engines have been delivered to Boeing since August, with certification targeted by year-end 2026, subject to Federal Aviation Administration approval.
GE Expands Engine Capacity and Defense Opportunities
Culp described the planned acquisition of Consolidated Precision Products as a way to expand critical casting capacity and accelerate cooling and durability improvements. He stressed that the supplier would continue serving other industry customers.
In defense, Ghai highlighted a five-year F414 support contract worth up to $2.9 billion and a backlog exceeding $30 billion. He expects high-single-digit Defense and Propulsion Technologies revenue growth in 2027.
Culp also highlighted progress on the F143 missile engine and XA102 adaptive-cycle engine programs. The company continues investing more than $3 billion annually in research and development.
GE Aerospace Maintains an Execution-Led Approach
Culp repeatedly centered management's priorities on safety, quality, delivery and cost, in that order. Supplier performance, shop productivity and engine durability remain important to supporting airline customers.
Management's outlook hinges on converting demand into deliveries and services revenues while managing GE9X costs, fuel-price pressure and supply constraints.
GE's Zacks Rank and Style Scores Send Mixed Signals
GE currently has a Zacks Rank #2 (Buy), reflecting a favorable earnings-estimate-revision signal for the near term. Its Value Score of D indicates weaker value characteristics, while its Growth Score of C represents a middle-range assessment of growth prospects. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Momentum Score of F indicates unfavorable price-momentum characteristics, while the composite VGM Score of F reflects a weak combination of value, growth and momentum factors. These scores temper the favorable Rank signal. The Zacks Rank can change as analysts revise earnings estimates following the reported results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
GE Aerospace (GE): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).