

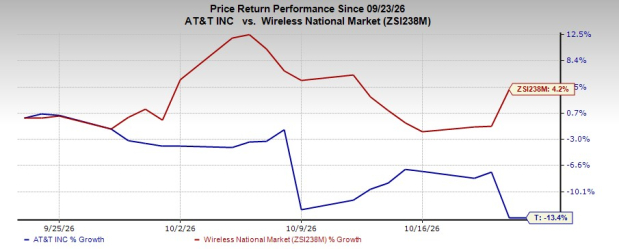
AT&T Inc. T shares have fallen 13.4% in the past four weeks even as third-quarter 2026 operating trends improved. The pullback raises the question of whether valuation now better compensates investors for the company’s execution risks.
Image Source: Zacks Investment Research
Fiber expansion, wireless subscriber gains and a higher earnings outlook support the case for stabilization. Elevated leverage, promotional spending and continued legacy declines keep the setup from becoming a straightforward buying call.
AT&T’s One-Month Slide Tests the Bull Case
AT&T reported third-quarter adjusted earnings of 65 cents per share, up 20.4% year over year, while revenues increased 5.3% to $32.32 billion. Both measures topped the Zacks Consensus Estimate.
AT&T Inc. Price, Consensus and EPS Surprise
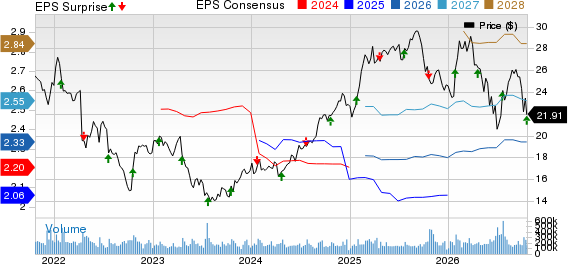
AT&T Inc. price-consensus-eps-surprise-chart | AT&T Inc. Quote
Management also raised its 2026 adjusted earnings outlook to around $2.40 per share from $2.25-$2.35. The stronger operating picture contrasts with the recent share weakness, though the decline should not be tied to any single factor.
T’s Fiber Momentum Still Supports Service Growth
AT&T added 769,000 Internet connections across consumer and business accounts, including 442,000 fiber additions and 327,000 fixed wireless additions. Advanced home Internet service revenues increased 23.4% year over year.
Fiber reach rose to 39.7 million locations. AT&T remains on track to exceed 40 million locations by year-end 2026, giving the company a broader base for convergence with wireless services.
AT&T’s Wireless Gains Face Promotion Pressure
Wireless service revenues rose 5% year over year and AT&T added 379,000 postpaid phone subscribers. Postpaid phone churn reached 0.92%, up from 0.86% in the second quarter.
Promotional discounts and introductory fiber pricing remain a trade-off. Fiber average revenue per user declined 4% year over year. T-Mobile US TMUS is expanding its broadband portfolio through fiber partnerships, adding another competitive route into home Internet. Verizon Communications Inc. VZ continues to pursue mobility and broadband convergence, making its network expansion another relevant benchmark for AT&T.
T’s Debt Load Limits Near-Term Financial Flexibility
Net debt climbed to $149.8 billion after the $23 billion EchoStar spectrum purchase. Net debt to adjusted EBITDA increased to 3.13X from 2.68X in the second quarter.
AT&T still targets leverage in the 2.5X range during 2029. Capital investment, dividends, repurchases and customer acquisition spending all compete for cash, making debt reduction an important part of the recovery case.
AT&T’s Valuation Leaves Room for a Reassessment
AT&T trades at 2.1X trailing 12-month enterprise value-to-sales, below its five-year median of 2.3X. The multiple also sits well below the Zacks sub-industry at 8.2X, the sector at 8.3X and the S&P 500 at 5.7X.
The valuation discount is paired with projected current-fiscal-year EPS growth of 9.9%. That combination leaves room for a reassessment if operating gains persist, but execution and deleveraging remain central to sustaining a higher valuation.
AT&T’s Mixed Signals Favor a Balanced View
The lower share price and discounted valuation improve the entry-point argument, but AT&T still carries enough financial and operating risk to warrant a measured stance. Fiber and wireless growth support the case, while leverage and pricing pressure limit near-term flexibility.
The stock currently carries a Zacks Rank #3 (Hold). AT&T has a Value Score of A, Momentum Score of A and VGM Score of A, but its Growth Score of C is less favorable. The mix points to attractive value and momentum characteristics without the stronger earnings-revision signal associated with a top-ranked stock. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
AT&T Inc. (T): Free Stock Analysis Report
Verizon Communications Inc. (VZ): Free Stock Analysis Report
T-Mobile US, Inc. (TMUS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).