

Western Digital Corporation WDC reported first-quarter fiscal 2027 non-GAAP earnings of $4.64 per share, which surpassed the Zacks Consensus Estimate of $4.09. The bottom line increased 161% year over year and 30% sequentially, exceeding the high end of management’s guidance of $4 (+/- 15 cents).
The company reported quarterly revenue of $4.38 billion, up 55% year over year and 17% sequentially on the back of robust customer demand and favorable pricing trends. The figure beat the consensus mark of $4.16 billion.
Western Digital Corporation Price, Consensus and EPS Surprise
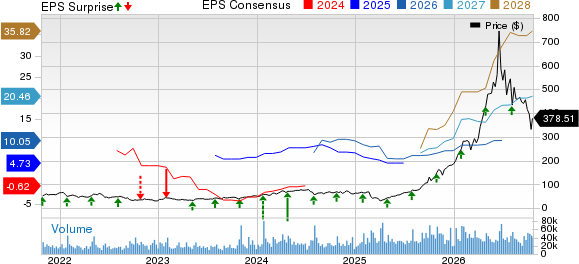
Western Digital Corporation price-consensus-eps-surprise-chart | Western Digital Corporation Quote
Western Digital shipped 248 exabytes in the quarter, up 22% year over year and 8% sequentially. Nearline products remained the primary growth driver as the company advanced its product transitions. WDC is ramping up its latest-generation ePMR drives, with capacities up to 40TB, and plans to introduce HAMR technology in the first half of calendar 2027. These developments are expected to support stronger year-over-year growth in exabyte shipments. Adoption is advancing faster than in previous technology transitions, with WDC expecting the new platform to account for nearly 30% of nearline shipments in the fiscal second quarter and 50% in the fiscal third quarter of 2027.
Western Digital's board of directors declared a quarterly cash dividend of 17.5 cents per share, representing a 17% increase from the previous dividend, payable on Dec. 17, 2026, to shareholders of record as of Dec. 4, 2026. The dividend increase highlights the company's financial momentum and its commitment to returning capital to shareholders.
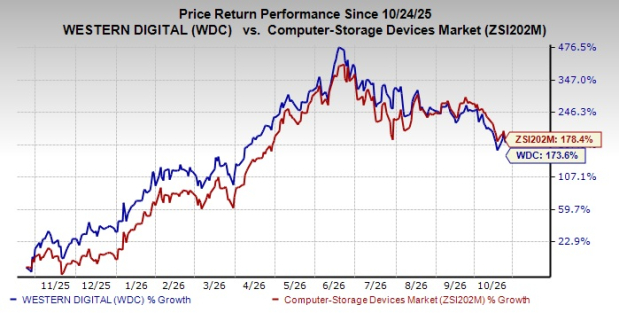
In the past year, shares have gained 173.6% compared with the Zacks Computer-Storage Devices industry’s rise of 178.4%.
Image Source: Zacks Investment Research
Quarter in Detail
Cloud end market revenue reached $3.9 billion (88% of total revenue), rising 54% year over year. Growth was driven by sustained demand for high-capacity nearline HDDs, including the initial ramp-up of its latest ePMR platform. Strong pricing trends further reflect the value and total cost of ownership (TCO) benefits the company offers its customers.
Revenues from the Client end market (7%) were up 119% year over year to $320 million.
Revenues from the Consumer end market (5%) surged 19% year over year to $193 million.
Margins
Non-GAAP gross margin expanded to 58.1%, up 1,420 basis points (bps) year over year with incremental gross margin exceeding 80%. A favorable mix of higher-capacity drives, disciplined operational execution and stronger pricing across its portfolio drove the improvement. The company also reported a 28% year-over-year increase in average price per terabyte, accelerating from the high-teens growth recorded in the previous quarter.
Non-GAAP operating margin rose to 49.1% from 30.4% in the year-ago quarter, highlighting its ability to sustain profitability improvements.
WDC reported non-GAAP operating income of $2.15 billion, up 152% year over year, driven by strong revenue growth, higher gross margins and improved operating leverage.
Non-GAAP operating expenses were $391 million, improving 130 bps sequentially, reflecting stronger operating leverage.
Balance Sheet & Cash Flow
As of Oct. 2, 2026, cash and cash equivalents were $1.3 billion compared with $1.6 billion reported as of Jul 3, 2026.
WDC ended the quarter with $789 million of debt.
Western Digital generated $1.6 billion in cash from operations compared with $672 million in the prior-year quarter. Free cash flow amounted to $1.4 billion in the quarter under review, up 130%.
WDC returned $1.1 billion to shareholders through share buybacks and dividends, underscoring the sustainability of free cash flow generation and its commitment to creating long-term shareholder value.
WDC's Fiscal Q2 2027 Guidance Signals Continued Growth
Western Digital expects its strong performance to continue in the second quarter of fiscal 2027, led by robust exabyte growth and improved pricing. At the midpoint of its guidance, the company expects revenue of $5.1 billion (+/- $100 million), representing a sequential increase of approximately 16% and a year-over-year rise of 69%.
Management projects non-GAAP gross margin of 60-61%, fueled by a favorable shift toward higher-capacity drives and a strong pricing environment.
Non-GAAP EPS is expected to reach $5.8 (+/- 20 cents).
WDC expects operating expenses to be between $400 million and $410 million for the fiscal second quarter, reflecting a sequential increase due to higher spending on product qualification activities.
WDC’s Zacks Rank
Currently, Western Digital has a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Recent Performances
Valero Energy Corporation VLO reported third-quarter 2026 adjusted earnings of $23.90 per share, up 553% from $3.66 a year ago. Revenues climbed 43.3% year over year to $46.10 billion from $32.17 billion, beating the Zacks Consensus Estimate by 23.29%.
The results benefited from substantially stronger refining margins and improved profitability across the Renewable Diesel and Ethanol segments. Refining throughput averaged 2.97 million barrels per day, down from 3.09 million barrels per day a year earlier.
Quest Diagnostics Incorporated DGX reported third-quarter 2026 adjusted earnings of $3.00 per share, up 15.4% year over year. The figure beat the Zacks Consensus Estimate by 5.3%. Revenues rose 10% year over year to $3.10 billion, surpassing the Zacks Consensus Estimate by 1.7%. Growth was supported by strong testing demand across physician, hospital and consumer channels, with organic requisition volume increasing 14.4%.
International Business Machines Corporation IBM reported strong third-quarter 2026 results, with adjusted earnings rising 11% year over year to $2.95 per share. The figure beat the Zacks Consensus Estimate of $2.88 by 2.4%. Revenues increased 4.7% to $17.10 billion, surpassing the consensus mark of $16.87 billion by 1.4%. Software revenues increased 8.2% year over year to $7.80 billion, up 8.7% at constant currency. Hybrid Cloud revenues grew 11%, supported by Red Hat, while Data jumped 20% at constant currency, benefiting from Confluent's performance.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Western Digital Corporation (WDC): Free Stock Analysis Report
International Business Machines Corporation (IBM): Free Stock Analysis Report
Quest Diagnostics Incorporated (DGX): Free Stock Analysis Report
Valero Energy Corporation (VLO): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).