

Comcast Corporation CMCSA outlined an extensive operational restructuring during its third-quarter 2026 earnings call, emphasizing cost reductions, customer retention and wireless expansion amid intensifying broadband competition.
Although adjusted earnings exceeded the Zacks Consensus Estimate, management acknowledged continued pressure on broadband profitability. Peacock's improving performance and the planned NBCUniversal separation remain important strategic priorities.
Comcast Beat Earnings Estimates Amid Revenue Pressure
Comcast reported adjusted earnings of $1.07 per share, exceeding the Zacks Consensus Estimate of 98 cents by 9 cents. However, adjusted earnings declined 4% from $1.12 in the year-ago quarter.
Quarterly revenues totaled $29.29 billion, marginally below the Zacks Consensus Estimate of $29.3 billion. Reported revenues declined 6.1% year over year, although pro forma revenues increased 0.5%.
Comcast Corporation Price, Consensus and EPS Surprise
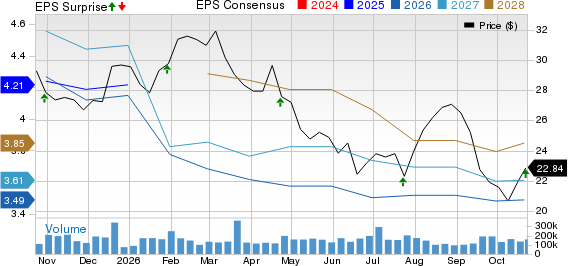
Comcast Corporation price-consensus-eps-surprise-chart | Comcast Corporation Quote
Chief financial officer Jason Armstrong highlighted $4.2 billion in free cash flow. Adjusted EBITDA declined 5.8% to $9.1 billion, reflecting ongoing financial pressures despite improvement in certain operating businesses.
CMCSA Faces Intensifying Broadband Competition
Co-CEO Michael Cavanagh acknowledged persistent competitive pressure from fixed wireless providers and aggressive fiber promotions. Management continues prioritizing simpler pricing, customer retention and service improvements.
Comcast lost 144,000 broadband subscribers during the quarter compared with 91,000 a year earlier. Domestic broadband revenues declined 4.7%, reflecting lower average rates and subscriber losses.
During the Q&A session, a MoffettNathanson analyst questioned whether competitors' recent pricing increases indicated improving conditions. Armstrong maintained that competition remained intense, citing fiber promotions offering gigabit services for $30-$40 monthly.
Comcast Expands Wireless and Premium Adoption
Connectivity & Platforms CEO Steven Croney emphasized wireless expansion as central to Comcast's customer retention strategy. The company added 368,000 wireless lines, bringing its total to 10.6 million.
Approximately 70% of customers receiving promotional free wireless lines convert into paying relationships. Premium unlimited plans accounted for approximately 40% of postpaid phone connections, compared with 30% in the preceding quarter.
Responding to a Citigroup analyst, Croney highlighted further expansion opportunities. Wireless penetration reached nearly 18% of residential broadband customers, while Comcast serves approximately 7% of addressable wireless lines within its footprint.
CMCSA Plans Significant Operating Restructuring
Armstrong announced plans for a fourth-quarter restructuring charge exceeding $1 billion, supporting organizational simplification and operational changes entering 2027.
Management identified cost improvement opportunities totaling billions of dollars over time. Initiatives include organizational redesign, accelerated artificial intelligence adoption and improved customer service efficiency.
During discussions with an Evercore ISI analyst, Armstrong emphasized reinvestment rather than cost reductions alone. Potential growth opportunities include premium wireless services, enterprise solutions and longer-term edge computing initiatives.
Comcast Sees Peacock Profitability Improve
Peacock generated $261 million in adjusted EBITDA, improving $478 million year over year. Revenue reached $1.8 billion, while paid subscribers increased 17% to 48 million.
Cavanagh highlighted stronger distribution revenue, advertising performance and successful implementation of a subscription price increase. Subscriber levels remained stable sequentially.
In response to a UBS analyst’s questions about profitability, Cavanagh cautioned that quarterly results could fluctuate depending on the timing of content rights. He expects continued annual profitability improvement and identified the upcoming YouTube Premium bundle as an opportunity to reach additional audiences.
CMCSA Expects Theme Park Recovery in Late 2027
Theme park revenues declined 4.4%, while adjusted EBITDA fell 17.1%. Management attributed the weakness primarily to softer Orlando demand and continued challenges in Japan.
Cavanagh identified marketing execution and capacity constraints at Epic Universe as additional pressures. Management is responding with targeted promotions, revised park packages and operational improvements.
During a Goldman Sachs analyst's questions, Cavanagh indicated that Orlando weakness could persist through the first half of 2027. Management expects overall theme park performance to return to growth during the second half.
Comcast Maintains Focus on Execution
Cavanagh reaffirmed plans to separate NBCUniversal and Sky by mid-2027. Armstrong reiterated that share repurchases remain suspended at least through the separation to preserve financial flexibility.
Management's near-term priorities center on broadband retention, wireless monetization, restructuring execution and positioning both businesses for independent operations.
What Zacks Rank and Style Scores Indicate for CMCSA
CMCSA currently carries a Zacks Rank #4 (Sell), reflecting an unfavorable near-term earnings estimate revision outlook. Its Value Score of A indicates attractive valuation characteristics, while its Growth Score of C and Momentum Score of D reflect less favorable growth and price momentum characteristics. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The stock's VGM Score of B reflects a favorable combined assessment of value, growth and momentum. However, its weaker Zacks Rank tempers those positive style signals. The Zacks Rank can change as analysts revise earnings estimates following the latest quarterly results.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Comcast Corporation (CMCSA): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).