

BXP, Inc. BXP is slated to report third-quarter 2026 results on Oct. 27, after market close. The company’s quarterly results are likely to display a year-over-year increase in revenues and funds from operations (FFO) per share.
In the last reported quarter, this office real-estate investment trust (REIT) reported FFO per share of $1.78, outpacing the Zacks Consensus Estimate of $1.71. The quarterly results reflected healthy leasing activity and higher occupancy.
Over the preceding four quarters, BXP’s FFO per share surpassed the Zacks Consensus Estimate thrice and missed in the remaining period, with the average beat being 0.92%. This is depicted in the graph below:
BXP, Inc. Price and EPS Surprise
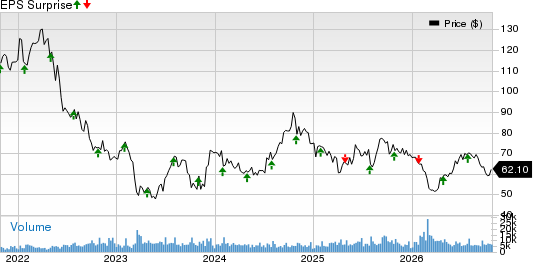
BXP, Inc. price-eps-surprise | BXP, Inc. Quote
US Office Market in Q3
Per a Cushman & Wakefield report, the U.S. office market continued to recover in the third quarter of 2026, supported by improving demand fundamentals. Net absorption was slightly positive at 49,700 square feet, while the four-quarter rolling total reached 15.5 million square feet. Overall absorption has been positive for five consecutive quarters, while Class A absorption has been positive in seven of the past eight quarters. The recovery was broad-based, with 52 of the 92 U.S. office markets tracked by Cushman & Wakefield Research recording positive net absorption over the past year.
National office vacancy declined 30 basis points (bps) year over year to 19.8%, while Class A vacancy fell 60 bps. Overall vacancy declined by more than 100 bps in one-fourth of U.S. markets, with the largest year-over-year declines concentrated in gateway and gateway-tangential markets. Meanwhile, Class A vacancy declined in 53 markets, with reductions exceeding 100 bps in more than one-third of U.S. markets. On the supply front, new office construction remains scarce. Deliveries through the first three quarters of 2026 totaled 7.1 million square feet, marking the lowest three-quarter total in more than 30 years.
BXP’s Factors at Play and Q3 Projections
BXP is poised to gain from the growing preference for premier office spaces among tenants and its ability to offer such spaces. This is likely to have had a positive impetus on its leasing activity, boosting its top line in the to-be-reported quarter.
Moreover, the company is likely to have continued executing its capital recycling strategy in the third quarter of 2026, using proceeds from land, residential and non-strategic office dispositions to fund development and redevelopment while reducing leverage.
However, some pressure points persist. Competitive leasing conditions in certain markets, along with higher operating and redevelopment costs tied to asset-repositioning efforts, could have tempered margin expansion in the quarter.
The Zacks Consensus Estimate for third-quarter revenues is pegged at $839.9 million, implying a 3.7% increase from the prior-year quarter’s reported number.
BXP’s activities in the to-be-reported quarter were inadequate in garnering analysts’ confidence. The Zacks Consensus Estimate for third-quarter FFO per share has declined a cent to $1.80 over the past two months. However, it suggests a 3.5% rise from the year-ago quarter’s tally.
What Our Quantitative Model Predicts for BXP
Our proven model predicts a surprise in terms of FFO per share for BXP this quarter. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the chances of an FFO beat, which is the case here.
BXP has an Earnings ESP of +0.04% and currently carries a Zacks Rank of 3. You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
Other Stocks That Warrant a Look
Here are two other stocks from the broader REIT sector — Ventas VTR and Host Hotels & Resorts HST — you may want to consider, as our model shows that these also have the right combination of elements to report an FFO beat this quarter.
Ventas is slated to report quarterly numbers on Oct. 27. VTR has an Earnings ESP of +0.70% and a Zacks Rank of 3 at present. You can see the complete list of today’s Zacks #1 Rank stocks here.
Host Hotels is slated to report quarterly numbers on Nov. 4. HST has an Earnings ESP of +3.20% and a Zacks Rank of 3 at present.
Note: Anything related to earnings presented in this write-up represents funds from operations (FFO), a widely used metric to gauge the performance of REITs.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
BXP, Inc. (BXP): Free Stock Analysis Report
Host Hotels & Resorts, Inc. (HST): Free Stock Analysis Report
Ventas, Inc. (VTR): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).