

GoDaddy GDDY is scheduled to report third-quarter 2026 results on Oct. 29.
For the third quarter of 2026, GoDaddy expects revenues between $1.315 billion and $1.335 billion. The midpoint implies year-over-year growth of 5%. The Zacks Consensus Estimate for third-quarter revenues is pegged at $1.33 billion, suggesting a 4.89% year-over-year rise.
The consensus mark for earnings is pinned at $1.82 per share, which has increased by a penny over the past 30 days. This indicates 20.53% growth from the year-ago quarter’s reported figure.
GoDaddy’s earnings beat the Zacks Consensus Estimate in all the trailing four quarters, delivering an average surprise of 6.39%.
GoDaddy Inc. Price and EPS Surprise
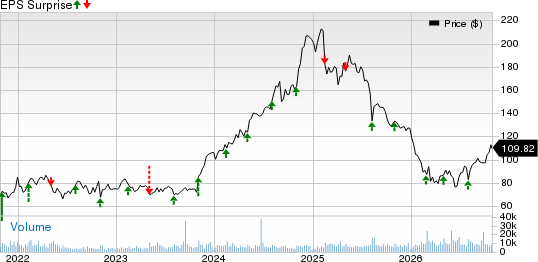
GoDaddy Inc. price-eps-surprise | GoDaddy Inc. Quote
Let us see how things are likely to have shaped up for GDDY prior to the announcement.
Key Factors to Note for GDDY’s Q3 Release
GoDaddy is expected to have benefited from growing adoption of its AI-powered Airo platform, strength in Applications & Commerce, resilient domain registrations and renewals and continued pricing and bundling initiatives in the third quarter of 2026.
The accelerating adoption of Airo, its agentic AI operating system for small businesses, has been noteworthy. In the second quarter, Airo’s annualized bookings run rate surged fivefold to $50 million from $10 million in the preceding quarter. Higher customer engagement, improved free-to-paid conversion rates and growing token consumption are likely to have supported monetization. The company’s efforts to integrate Airo into its domain purchase funnel and expand marketing activities are expected to have strengthened customer acquisition.
The Applications & Commerce segment is expected to have benefited from growing demand for integrated digital solutions, including AI-powered website creation, commerce, payments and customer engagement tools. The segment’s revenues increased 11% year over year to $515 million in the second quarter. GoDaddy expects low-double-digit revenue growth in this segment for the third quarter. The integration of additional commerce capabilities into Airo and increased product attachment among existing customers are likely to have supported the segment’s performance. The Zacks Consensus Estimate for Applications & Commerce segment revenues is pegged at $532 million, indicating a 10.6% year-over-year rise.
GoDaddy’s Core Platform segment is expected to have benefited from healthy domain registration and renewal activities, particularly across.COM and higher-priced non-.COM top-level domains. Continued pricing optimization, bundling initiatives and resilient customer retention are likely to have supported revenues. Management expects Core Platform revenues to increase in the low-single-digit range in the third quarter. The Zacks Consensus Estimate for Core Platform revenues is pinned at $795 million, suggesting 1.40% year-over-year growth.
GoDaddy’s profitability is expected to have benefited from operating leverage, disciplined cost management and AI-driven productivity improvements across customer care, technology development and administrative functions. Management projects a normalized EBITDA margin of approximately 33% for the third quarter. However, moderating bookings from traditional website-building and professional services offerings, tough year-over-year comparisons in the domain aftermarket business and increased AI-related investments might have partially offset these positives.
What Our Model Says
Per the Zacks model, the combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. That’s the exact case here.
GoDaddy currently has an Earnings ESP of +3.22% and a Zacks Rank #3. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Other Stocks to Consider
Here are some companies worth considering, as our model shows that these have the right combination of elements to beat on earnings in their upcoming releases:
AMETEK AME has an Earnings ESP of +0.20% and a Zacks Rank #1. You can see the complete list of today’s Zacks #1 Rank stocks here.
AMETEK shares have gained 18.2% year to date. AMETEK is set to report third-quarter 2026 results on Nov. 3.
Affirm AFRM has an Earnings ESP of +11.03% and a Zacks Rank #2 at present.
Affirm shares have lost 6.7% year to date. Affirm is scheduled to report first-quarter fiscal 2027 results on Nov. 5.
Cametek CAMT has an Earnings ESP of +0.85% and a Zacks Rank #2 at present.
Cametek shares have gained 15.9% in the year-to-date period. Cametek is set to report third-quarter 2026 results on Nov. 4.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power .
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>Want the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
GoDaddy Inc. (GDDY): Free Stock Analysis Report
AMETEK, Inc. (AME): Free Stock Analysis Report
Camtek Ltd. (CAMT): Free Stock Analysis Report
Affirm Holdings, Inc. (AFRM): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).