

Texas Instruments Incorporated TXN delivered a strong improvement in profitability in the third quarter of 2026, raising hopes that its gross margin can climb further. The semiconductor maker reported a gross margin of 64.2%, up from 57.4% in the year-ago quarter and 61.4% in the previous quarter.
Texas Instruments’ third-quarter gross profit rose 43% year over year to $3.89 billion, outpacing the 28% increase in revenues to $6.06 billion. Higher sales volumes supported the improvement, while better factory utilization, pricing and product mix also helped. These trends suggest that stronger demand can translate into better profitability when production facilities operate more efficiently.
Growth across key markets offers additional support. Industrial revenues increased more than 40% year over year, while automotive revenues grew at a mid-teens rate. Data center revenues surged about 95%, reflecting rising demand for chips used in expanding computing infrastructure. Continued strength in these markets could help TXN maintain higher production levels and spread manufacturing costs across more units.
Texas Instruments' 300-millimeter wafer manufacturing strategy could also support cost efficiency as output rises. Per the company, an unpackaged chip built on 300-millimeter wafers costs approximately 40% less than one built on 200-millimeter wafers. Texas Instruments has available cleanroom capacity in its Richardson, Sherman and Lehi facilities. Management plans to install additional equipment according to demand, supporting dependable supply and cost efficiency as production volumes increase.
For the fourth quarter of 2026, the Zacks Consensus Estimate for revenues and earnings indicates year-over-year growth of 37.7% and 94.5%, respectively. These projections imply continued business activity, which could further expand Texas Instruments’ margins.
How Do TXN’s Competitors Compare on Gross Margin?
Analog Devices, Inc. ADI is a close competitor in analog chips and signal-processing technology. In the third quarter of fiscal 2026, ADI’s revenues rose 40% year over year to $4.02 billion, while its GAAP gross margin increased to 67.3% from 62.1% in the year-ago quarter.
Its adjusted gross margin reached 72.5% from 69.2% in the year-ago quarter, highlighting strong profitability. These results put Analog Devices ahead of TXN’s 64.2% gross margin.
Microchip Technology Incorporated MCHP is another competitor, supplying microcontrollers and embedded-control chips. In the first quarter of fiscal 2027, revenues grew 38% year over year to $1.49 billion.
Microchip Technology’s GAAP gross margin improved to 63.2% from 53.6% in the year-ago quarter, while its non-GAAP gross margin reached 63.8% from 54.3%. Higher factory utilization and recovering demand supported the improvement.
Both companies show how stronger demand and manufacturing efficiency can lift margins. Analog Devices’ higher reported margin sets a competitive benchmark, while Microchip Technology’s performance highlights the benefits of better factory utilization.
TXN’s Price Performance, Valuation and Estimates
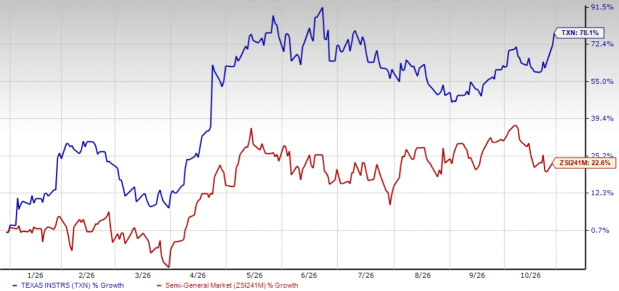
Shares of Texas Instruments have surged 78.1% year to date compared with the Zacks Semiconductor - General industry’s 22.6% growth.
Texas Instruments YTD Price Return Performance
Image Source: Zacks Investment Research
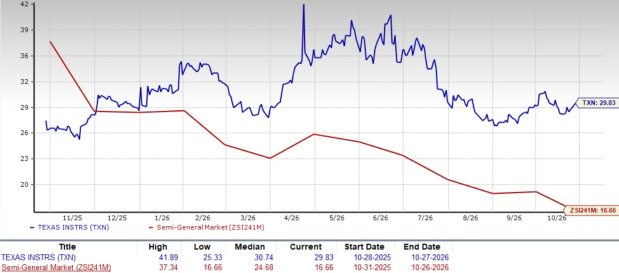
From a valuation standpoint, TXN trades at a forward price-to-earnings ratio of 29.83, significantly higher than the industry’s average of 16.66.
Texas Instruments Forward 12-Month P/E Ratio
Image Source: Zacks Investment Research
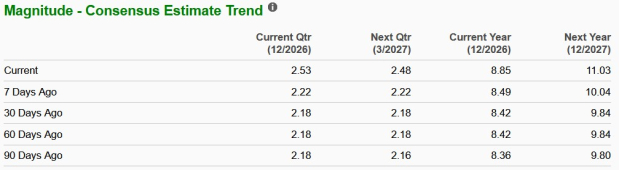
The Zacks Consensus Estimate for Texas Instruments’ 2026 and 2027 earnings implies a year-over-year increase of 62.4% and 24.7%, respectively. Estimates for 2026 and 2027 have been revised upward over the past seven days.
Image Source: Zacks Investment Research
Texas Instruments currently sports a Zacks Rank #1 (Strong Buy). You can see the complete list of today’s Zacks #1 Rank stocks here.
Zacks' Research Chief Names "Stock Most Likely to Double"
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren't winners, but this one could far surpass earlier Zacks' Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Texas Instruments Incorporated (TXN): Free Stock Analysis Report
Analog Devices, Inc. (ADI): Free Stock Analysis Report
Microchip Technology Incorporated (MCHP): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).