

Flex Ltd. FLEX has added EPC Power at a time when its Cloud and Power Infrastructure business is scaling rapidly on AI-related demand. The acquisition adds power-conversion expertise that could deepen the planned Axiom platform across critical data center infrastructure.
The opportunity is meaningful, but so are the demands. Flex must integrate another acquired business, fund heavy capacity investment and manage higher interest expense while preparing Axiom for a planned separation in calendar first-quarter 2027.
FLEX Adds Critical Power Technology
EPC Power adds power-conversion capabilities and engineering expertise relevant to next-generation 800-volt data center systems and solid-state transformers. That technology fits directly with the electrical demands of denser AI infrastructure, where efficient power delivery is becoming a larger part of system design.
The acquisition also gives Flex another specialized asset inside its Power portfolio. Management expects EPC Power to be accretive to fiscal 2027 earnings, indicating that the deal is intended to contribute financially even before Axiom becomes an independent company.
Flex Is Building an End-to-End Platform
EPC Power extends a portfolio that already includes embedded power, compute integration and thermal-management capabilities. Electrical Power Products added power control and protection, while JetCool and Crown Technical Systems expanded liquid-cooling and critical-power offerings.
That broader model also raises the competitive bar. Jabil Inc. JBL offers rack-level data center infrastructure spanning compute, power and liquid cooling. Celestica Inc. CLS is also expanding AI data center hardware and networking platforms. Axiom’s advantage will depend on turning its wider portfolio into faster deployment, attractive economics and consistent execution for customers.
FLEX Expects the Deal to Lift Earnings
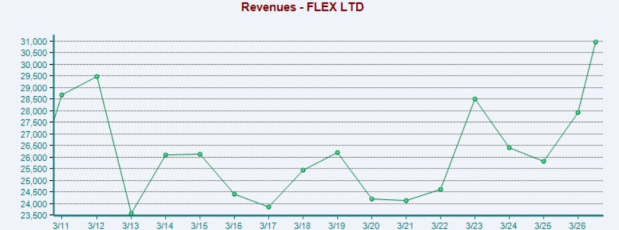
Flex has incorporated recent acquisitions into higher fiscal 2027 expectations. The company now projects revenues of $34.9-$35.9 billion and adjusted earnings of $4.84-$5.16 per share, with Cloud and Power Infrastructure revenues expected to increase 75-85%.
The underlying business is already expanding quickly. Second-quarter fiscal 2027 Cloud and Power Infrastructure revenues rose 54% to $2.51 billion, while adjusted operating margin widened 240 basis points to 10.7%. Management expects the segment’s adjusted operating margin to reach 11.5-11.7% for the year.
Image Source: Zacks Investment Research
Flex Takes on More Financial Complexity
The EPC Power transaction involved $4.4 billion of acquisition debt. Flex expects net proceeds from a planned $2 billion sale of Axiom convertible preferred stock to repay about $2 billion of that borrowing, but management still expects elevated interest expense until the transaction is completed.
Capital spending adds another pressure point. Flex expects fiscal 2027 capital expenditures of $1.5-$1.6 billion and free cash flow conversion of about 40%. Long-term debt stood at $5.21 billion as of Sept. 25, 2026, compared with $3.75 billion at fiscal 2026-end, leaving less room for execution missteps during the expansion.
FLEX’s Ratings Keep Expectations Grounded
The EPC Power deal strengthens the strategic logic behind Axiom by adding another layer to Flex’s power, cooling and compute platform. The earnings outlook and segment margin expansion support the growth case, but debt, capital intensity and integration needs keep the payoff dependent on disciplined execution.
FLEX currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
It has a Value Score of B, Growth Score of B, Momentum Score of C and VGM Score of B. The B scores point to favorable characteristics across several investment styles, while the C Momentum Score is more neutral. Because the Style Scores are designed to complement the Zacks Rank, the combined signal supports a balanced view rather than an aggressive near-term call.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpWant the latest recommendations from Zacks Investment Research? Today, you can download 7 Best Stocks for the Next 30 Days. Click to get this free report
Flex Ltd. (FLEX): Free Stock Analysis Report
Jabil, Inc. (JBL): Free Stock Analysis Report
Celestica, Inc. (CLS): Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).